
Family Holdings #3 - Distribution and infrastructure determine the AI battle at Alphabet and Brookfield


This week's topics:
Brookfield is taking a fundamental step into AI infrastructure with the launch of cloud company Radiant. By now combining its existing positions in energy, real estate and data centres with its own cloud application, the group is making the AI chain operational internally. In a market where AI is increasingly constrained by physical and energy-related limitations, Brookfield is positioning itself as an active infrastructure provider rather than merely a capital provider. This strategy opens up opportunities for structural value creation, but also brings clear execution risks, particularly on the energy and nuclear side.
In a personal interview, Warren Buffett looks back on his life, investment philosophy and philanthropic choices. Together with his children, he discusses the values that have shaped his success, the influence of mentors such as Charlie Munger, and why discipline, integrity and simple kindness matter more than sheer intellect.
In Brief:
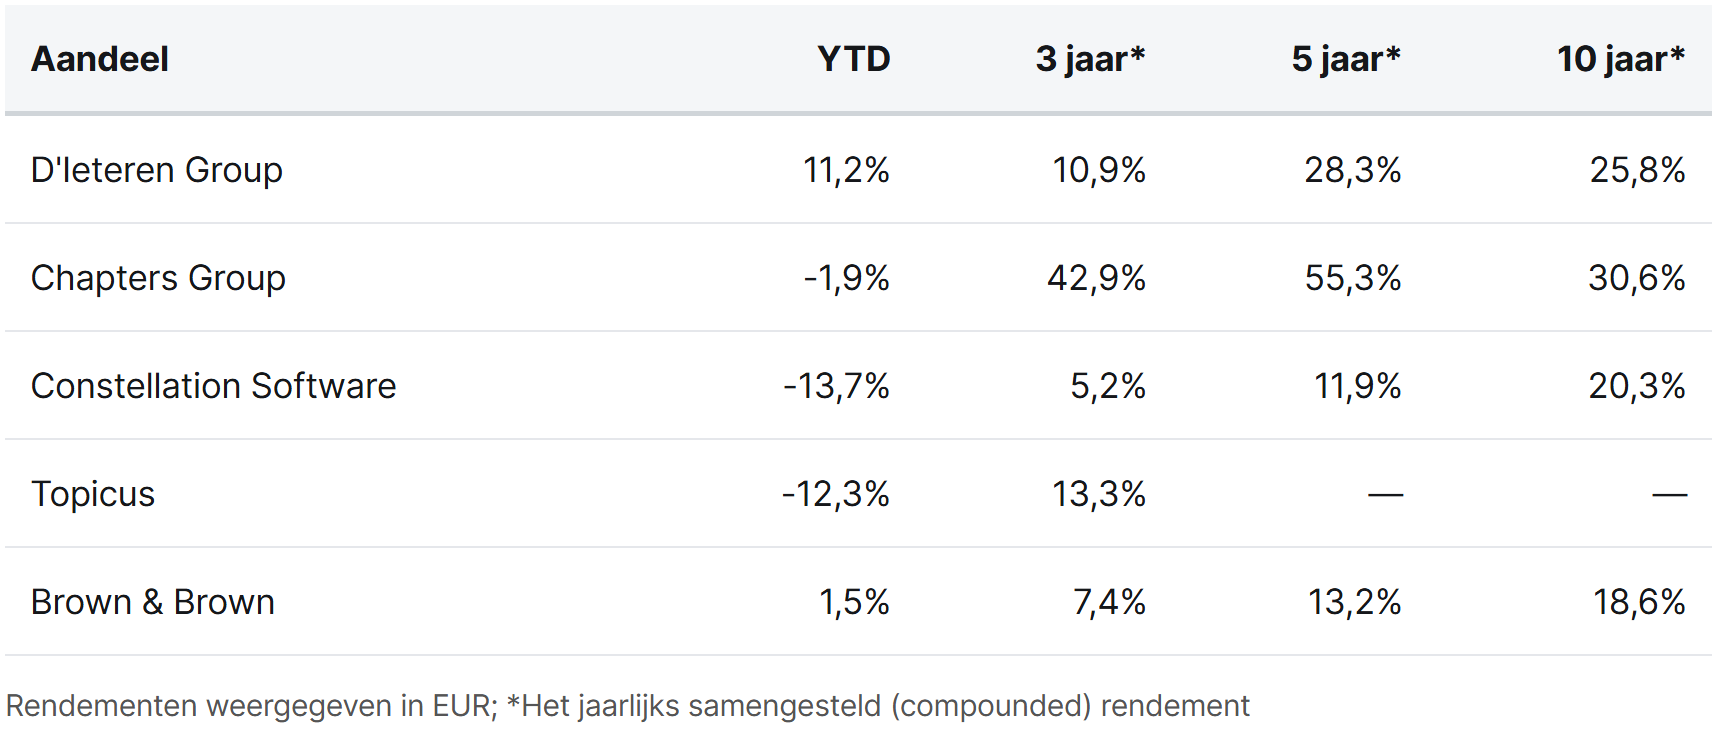
D'Ieteren Group (Brussels: DIE) announced that its subsidiary PHE has entered exclusive negotiations to acquire 51% of the Spanish parts distributors Polaris and Regueira, together accounting for approximately €340 million in revenue in 2025. In addition, strong analyst optimism around D'Ieteren emerged this week. Berenberg initiated coverage of the stock with a buy rating and a price target of €224, with the bank highlighting the strong cash flow visibility, dominant market positions and value creation within Belron. Bank of America also raised its price target, from €175 to €199, while maintaining its buy rating. The analysts point to the robust intrinsic value of the portfolio and apply a holding company discount of approximately 30%.
Chapters Group (Hamburg: CHG) is investing millions in Germany's Fuxam, a fast-growing provider of all-in-one campus and learning management software for universities, colleges and training institutions. The investment strengthens Chapters' position in the education software sector. In addition, a governance restructuring took place within the management BV: through Stanza Management Beteiligungen, shares worth €4.06 million were sold, after which CEO Jan-Hendrik Mohr, chairman Mathias Saggau and supervisory board member Edda Heidbrink jointly bought back shares worth over €2.2 million.
Constellation Software (Toronto: CSU) made two acquisitions through its Harris division. The company acquired GlobalMeet, a leading platform for enterprise webcasting and interactive virtual events, with around 115 employees. It also purchased K-Ecommerce and Orckestra from KKR, two complementary e-commerce and omnichannel platforms from Canada.
Topicus (Toronto: TOI) further expanded its automotive vertical with the acquisition of the UK's Qube Automotive, a provider of aftersales, data and reporting software for international vehicle manufacturers. Qube supports OEMs with insights across the full vehicle and customer lifecycle, and offers solutions for trade parts sales, parts logistics and web-based reporting. With the addition of Qube, Topicus now has six automotive software businesses within the UK & Ireland region, further strengthening its position in this vertical niche.
Brown & Brown (New York: BRO) acquired the UK's Sure Insurance Services through its subsidiary Nexus Underwriting, the market leader in insurance solutions for medical travel and medical tourism. Sure will continue to operate under Millstream, with founder Alison Thornberry on board.
D'Ieteren Group, Chapters Group, Constellation Software, Topicus and Brown & Brown are currently trading on the Toronto and Brussels exchanges at prices of EUR 170.20, EUR 40.70, CAD 2,818.38, CAD 112.77 and USD 79.88 per share, respectively.
Alphabet is winning the AI battle through unprecedented distribution deals
The recent news flow around Alphabet revolves almost entirely around one theme: Gemini. Not so much because of technical model updates, but because of something far more fundamental: distribution. In a market where there is still barely any visibility on structural revenue models and margins for large language models, one anchor remains in practice, namely market share and the degree of exposure among end users. Whoever succeeds in making their model part of daily use on a large scale creates habituation and lowers the willingness to switch. In today's fast-changing AI landscape, distribution may therefore well be the most valuable form of future value creation.
It was precisely on this point that Alphabet took an important strategic step forward last week relative to competitors such as OpenAI. Samsung Electronics announced its intention to double the number of devices running Gemini, from around 400 million to 800 million in 2026. That strategic choice was explicitly confirmed by co-CEO TM Roh, who stated: "We will apply AI as quickly as possible across all our products, features and services."
Roh views any hesitation among consumers primarily as temporary: "While AI technology may raise some doubts right now, it will become far more widespread within six to twelve months."
The same week brought confirmation of earlier rumours that Apple will use Gemini as the foundation underpinning the renewed Siri. This gives Alphabet access to an installed base of more than two billion active devices, a scale that is exceptional even within Big Tech. What makes this partnership particularly striking is its economic structure. According to market rumours, Google receives around one billion dollars a year for this deal, a clear win-win scenario for Alphabet. The largest electronic ecosystem in the world chooses your model as the default, and instead of having to pay for that, you also get paid for it. It sounds almost too good to be true.
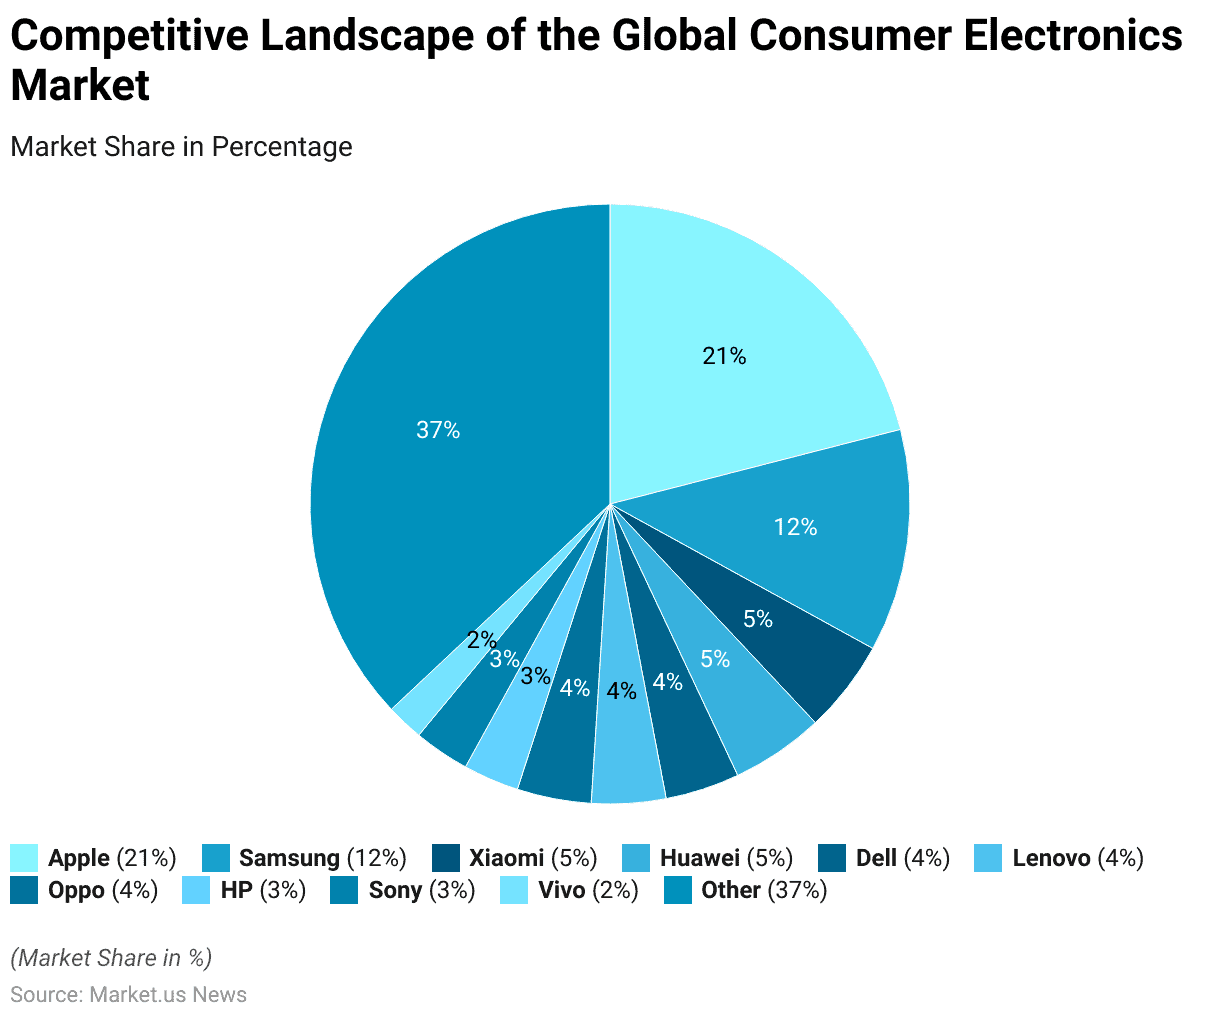
The fact that Gemini is now reaching consumers not only through Samsung but also through Apple translates into serious scale. Samsung accounts for around 12% of the global consumer electronics market, while Apple represents around 21%. Together, that amounts to an estimated 33% of all electronic devices worldwide that come into direct or indirect contact with Gemini.
That scale naturally raises questions too. Elon Musk called the partnership an "unreasonable concentration of power". Alphabet already has a longer history of investigations and proceedings relating to abuse of power and dominant market positions. Both in the United States and in Europe, the company has repeatedly faced antitrust cases. Against that backdrop, it is not inconceivable that regulators will in time turn their attention to Gemini as a new, potential form of digital infrastructure monopoly.
First Global AI Tracker of 2026
— Similarweb (@Similarweb) January 7, 2026
Gen AI Website Worldwide Traffic Share, Key Takeaways:
→ Gemini surpassed the 20% share benchmark.
→ Grok surpasses 3% and is approaching DeepSeek.
→ ChatGPT drops below the 65% mark.
🗓️ 12 Months Ago:
ChatGPT: 86.7%
Gemini: 5.7%… pic.twitter.com/D1lNf1G5sr
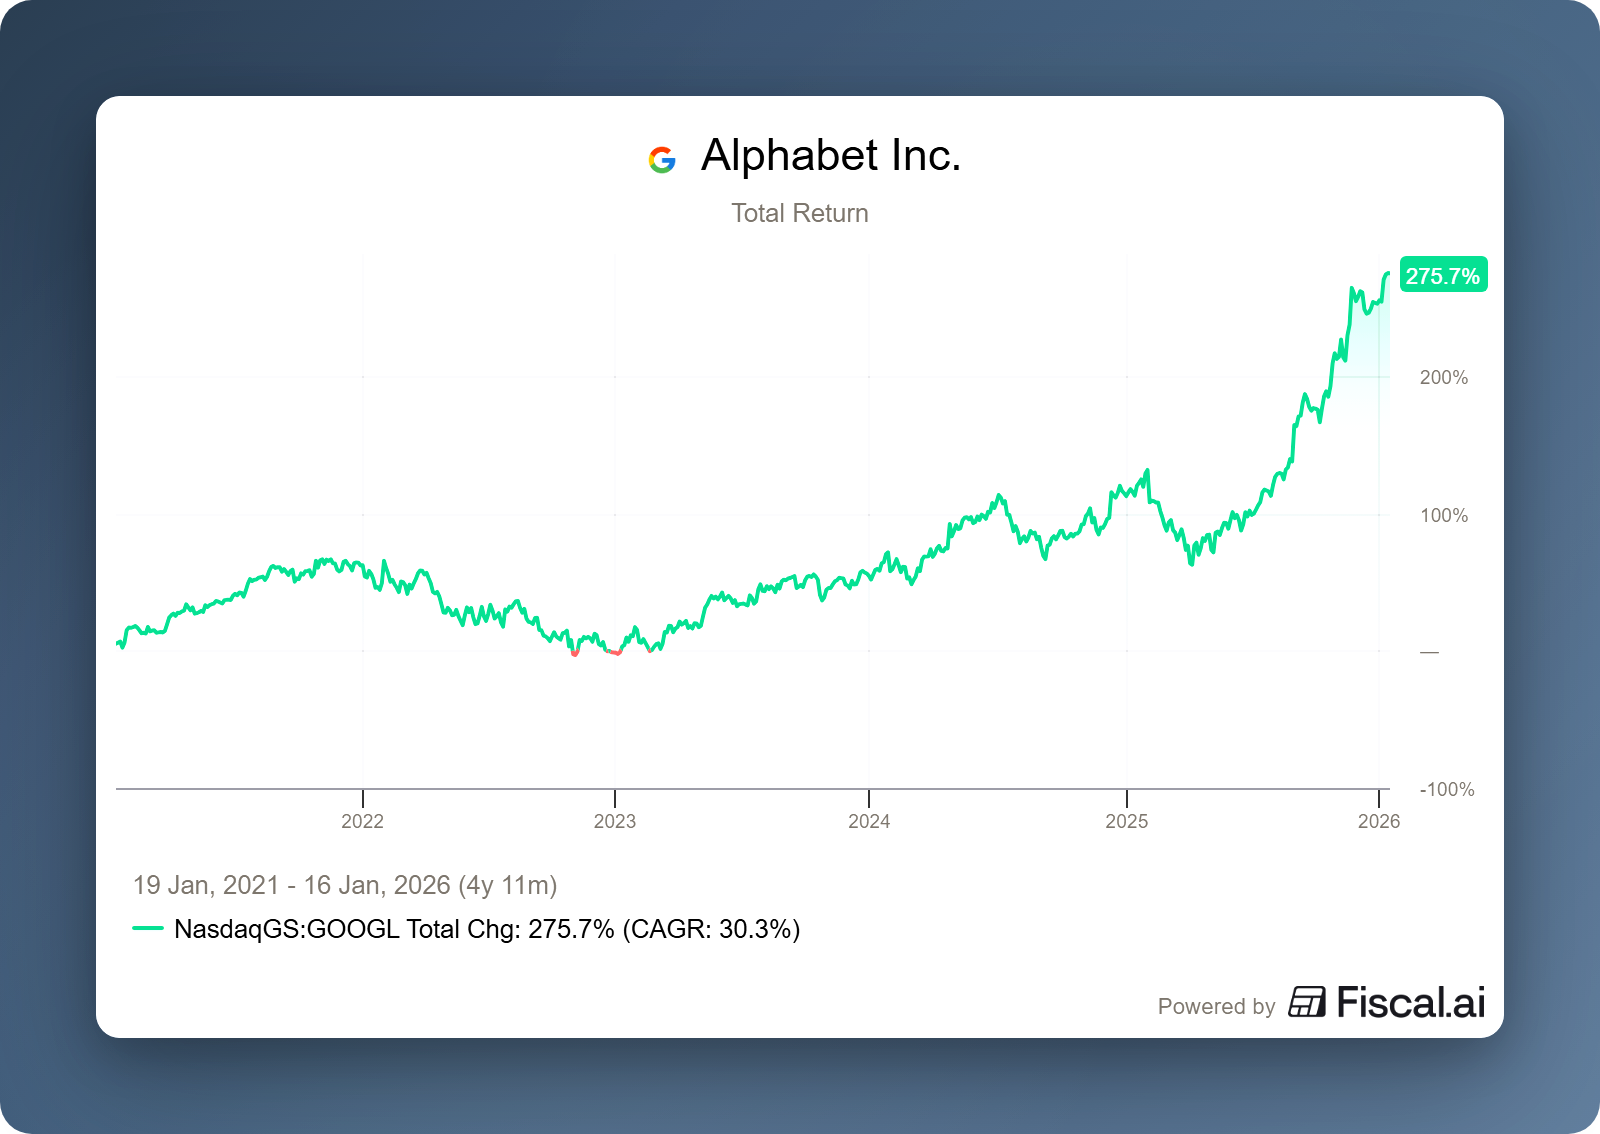
These concerns stand in sharp contrast to the speed at which Gemini is gaining ground. According to data from Similarweb, Gemini broke through the 20% market share mark in generative AI traffic for the first time in 2026, with its share now standing at around 21.5%. That still compares with a dominant, though declining, position for GPT at around 64.5%. The market has not let this development go unnoticed. Alphabet recently overtook Apple to become the second-largest listed company in the world. At the same time, it joined a very exclusive group as only the fourth company ever to reach a market capitalisation of more than $4 trillion.
Alphabet is currently trading on the New York stock exchange at a price of USD 329.96 per Class A share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Brookfield completes the AI chain with its cloud business
The step Brookfield (New York: BN) recently took in AI infrastructure is difficult to compare with the moves of classic technology companies. Where most players approach AI from software, models and applications, Brookfield is taking a fundamentally different angle. With the launch of cloud company Radiant and a new $10 billion AI fund, the group is shifting from capital provider to active owner that can now also genuinely put its physical AI infrastructure to internal use.
That shift is driven by an increasingly visible reality within AI. The bottleneck lies less in algorithms and increasingly in physical constraints. Computing power is energy-intensive, data centres are capital-intensive, and reliable power supply can no longer be taken for granted. Across the market, AI capex is growing explosively, while returns remain uncertain due to rising energy costs, grid congestion and logistical complexity. Brookfield is tackling this problem at the source by managing infrastructure, energy and compute in-house, and says this enables it to structurally reduce the costs of AI development compared with competitors.
According to Sikander Rashid, Brookfield's global head of AI infrastructure, the company is explicitly targeting governments and businesses that want to store data locally and retain control over their infrastructure. “We want to be able to build and operate these compute clusters ourselves, rather than being dependent on, say, five different partners in five different markets,” said Rashid. Radiant plays a key role in this. The cloud company gets priority access to data centres developed under the AI fund, with projects in France, Qatar and Sweden, among others. This allows Brookfield to plan capacity from its own portfolio of utilities and renewable energy.
With this move, Brookfield is explicitly entering the playing field of established cloud players such as Google, Microsoft and Amazon, but also of newer AI cloud companies such as CoreWeave and Nebius. Notably, many other private equity players are avoiding exactly this step. Operating AI clouds itself requires large investments in expensive chips and brings operational risks. Where players such as Blackstone limit themselves to financing cloud companies, Brookfield has chosen to operate itself. A remarkable choice, but one that is easy to understand given Brookfield's existing asset base. The group is already one of the largest owners of land, data centres and energy assets in the world, including one of the largest portfolios of solar and wind energy. In addition, Brookfield is the largest shareholder of Westinghouse, a builder of nuclear reactors.
 CapexAndChill
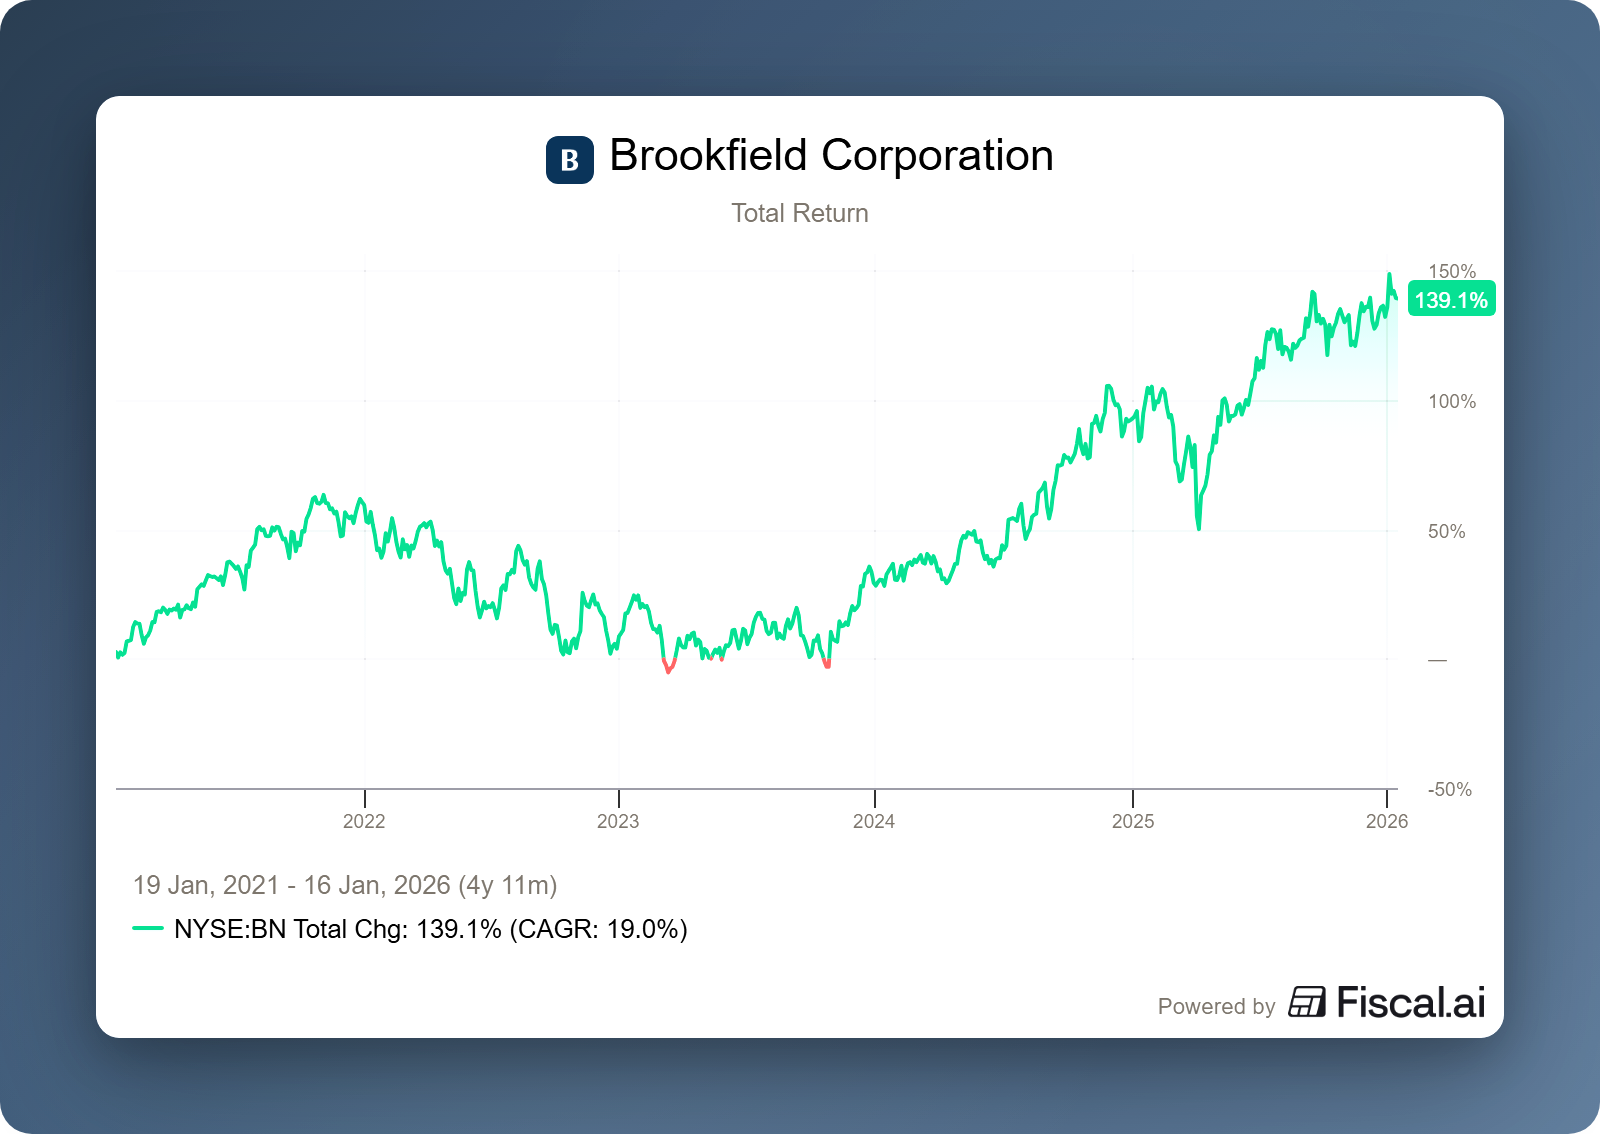
In a recent deep dive, investor CapexAndChill argues that it is precisely on this latter point that significant value creation could still emerge going forward, provided execution succeeds. In this context, he points to the special structure of the partnership with the US government, which can partly hedge political and regulatory risks, while at the same time stressing that nuclear projects remain exceptionally sensitive to execution, timing and cost control. For anyone wanting to delve further into the subject, this piece is a valuable addition.
Brookfield Corporation is currently trading on the New York stock exchange at a price of USD 47.31 per share.
Interview with the Buffett family
In this interview, Warren Buffett reflects on his impressive life, recalling memories of his early fascination with statistics and his switch from horse racing to the stock market. He discusses at length his business evolution, the shortcomings of modern corporate governance, and the crucial lessons he learned from mentors such as Tom Murphy and Charlie Munger.
A central theme is his philanthropic vision, in which he explains why he entrusts the management of his fortune to his three children. His children themselves speak about their modest upbringing, their cooperation with one another, and the enormous responsibility that this inheritance brings with it. Finally, Buffett emphasises that personal success does not stem from intelligence alone, but above all from discipline, integrity and showing simple kindness.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts of it, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your investment. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is indicative only and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



