
Family Holdings #12 - The AI hype is free, the bill is not


This week's topics:
The managers of the Scottish Mortgage Investment Trust describe the current AI transition as the most impactful shift ever and position the trust as a broadly diversified 'insurance policy' across the entire value chain. A standout success story within the portfolio is SpaceX, which, following strong value increases, now accounts for 15.4% of the trust. In order to remain decisive on new 'moonshots' despite strict limits on private holdings, management is proposing a policy change that creates additional investment headroom. According to managers Slater and Burns, this gives the trust an essential advantage over passive index trackers: exclusive access to the crucial growth phase of private AI pioneers such as Anthropic, well before they reach the public market.
In Brief:
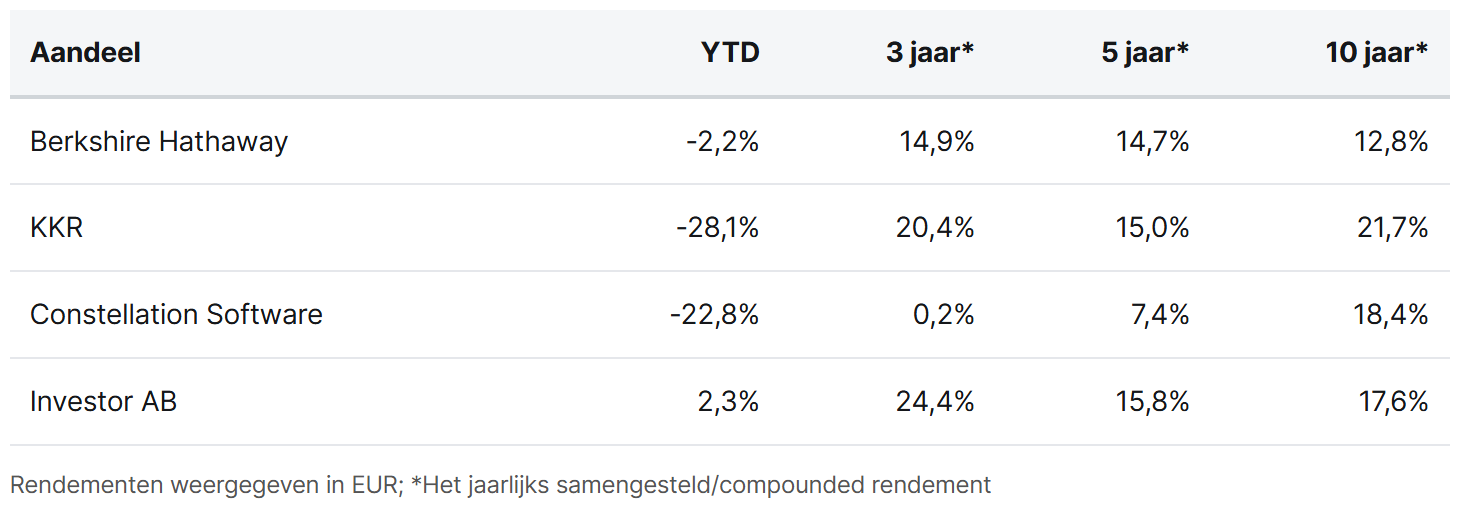
Berkshire Hathaway (New York: BRK.B) got off to a flying start with its recently announced share buyback programme. Immediately after the official announcement, the holding company opened its wallet to buy back the first shares. A recent filing shows that in the first few days the company spent a whopping $226 million to buy back 'just' 309 Class A shares.
KKR (New York: KKR) is on the verge of realising a substantial profit from the sale of cooling technology company CoolIT. The company took a majority stake in 2023 at a valuation of $270 million. CoolIT is reportedly set to be sold at a valuation of between $4.5 and $5 billion. In addition, the company is investing up to $310 million in a first investment for the fund dedicated to the Climate Transition in India. KKR is acquiring a majority stake in the electric bus platform PMI Electro and Allfleet India, which plans to roll out a fleet of more than 5,000 buses.
Constellation Software (Toronto: CSU) saw three of its platform companies complete new acquisitions. Subsidiary Volaris acquired US-based Compose, a provider of cloud-based software for policy and procedure management. Vela, meanwhile, closed no fewer than three acquisitions in Brazil: Alfasig (tax documentation), Alpino Tecnologia (invoicing) and ERP Praeter (management systems). Jonas was also active; through subsidiary Vesta, it acquired Hungary's SK Trend. This insurance technology company offers a front- and back-office platform for intermediaries and marks Jonas's fourth acquisition in Hungary.
The management of the Swedish family holding company Investor AB (Stockholm: INVE.B) is once again showing strong confidence in its own course. Both CEO Christian Cederholm and director Thomas Kidane expanded their holdings this week, with purchases of SEK 1 million and SEK 0.7 million respectively. At subsidiary Atlas Copco too, CEO Vagner Rego sent a clear signal by buying SEK 1.5 million worth of shares.
Berkshire Hathaway, KKR, Constellation Software and Investor AB are currently trading on the exchanges of New York, Toronto and Stockholm at prices of USD 483.57 (B share), USD 89.90, CAD 2,509.57 and SEK 338.00 per share, respectively.
Tencent's AI bill lands on Prosus's doorstep
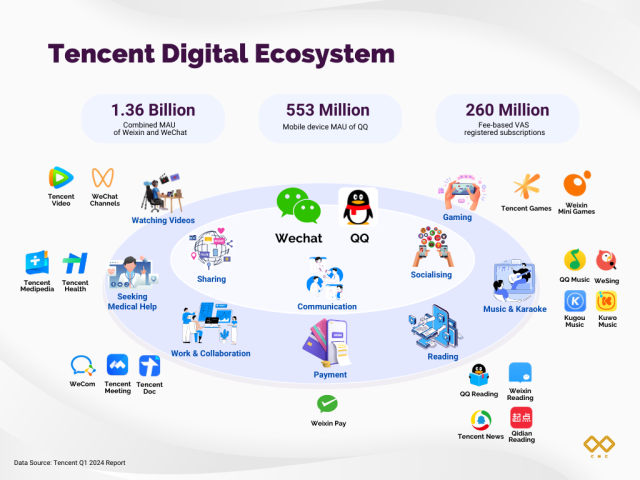
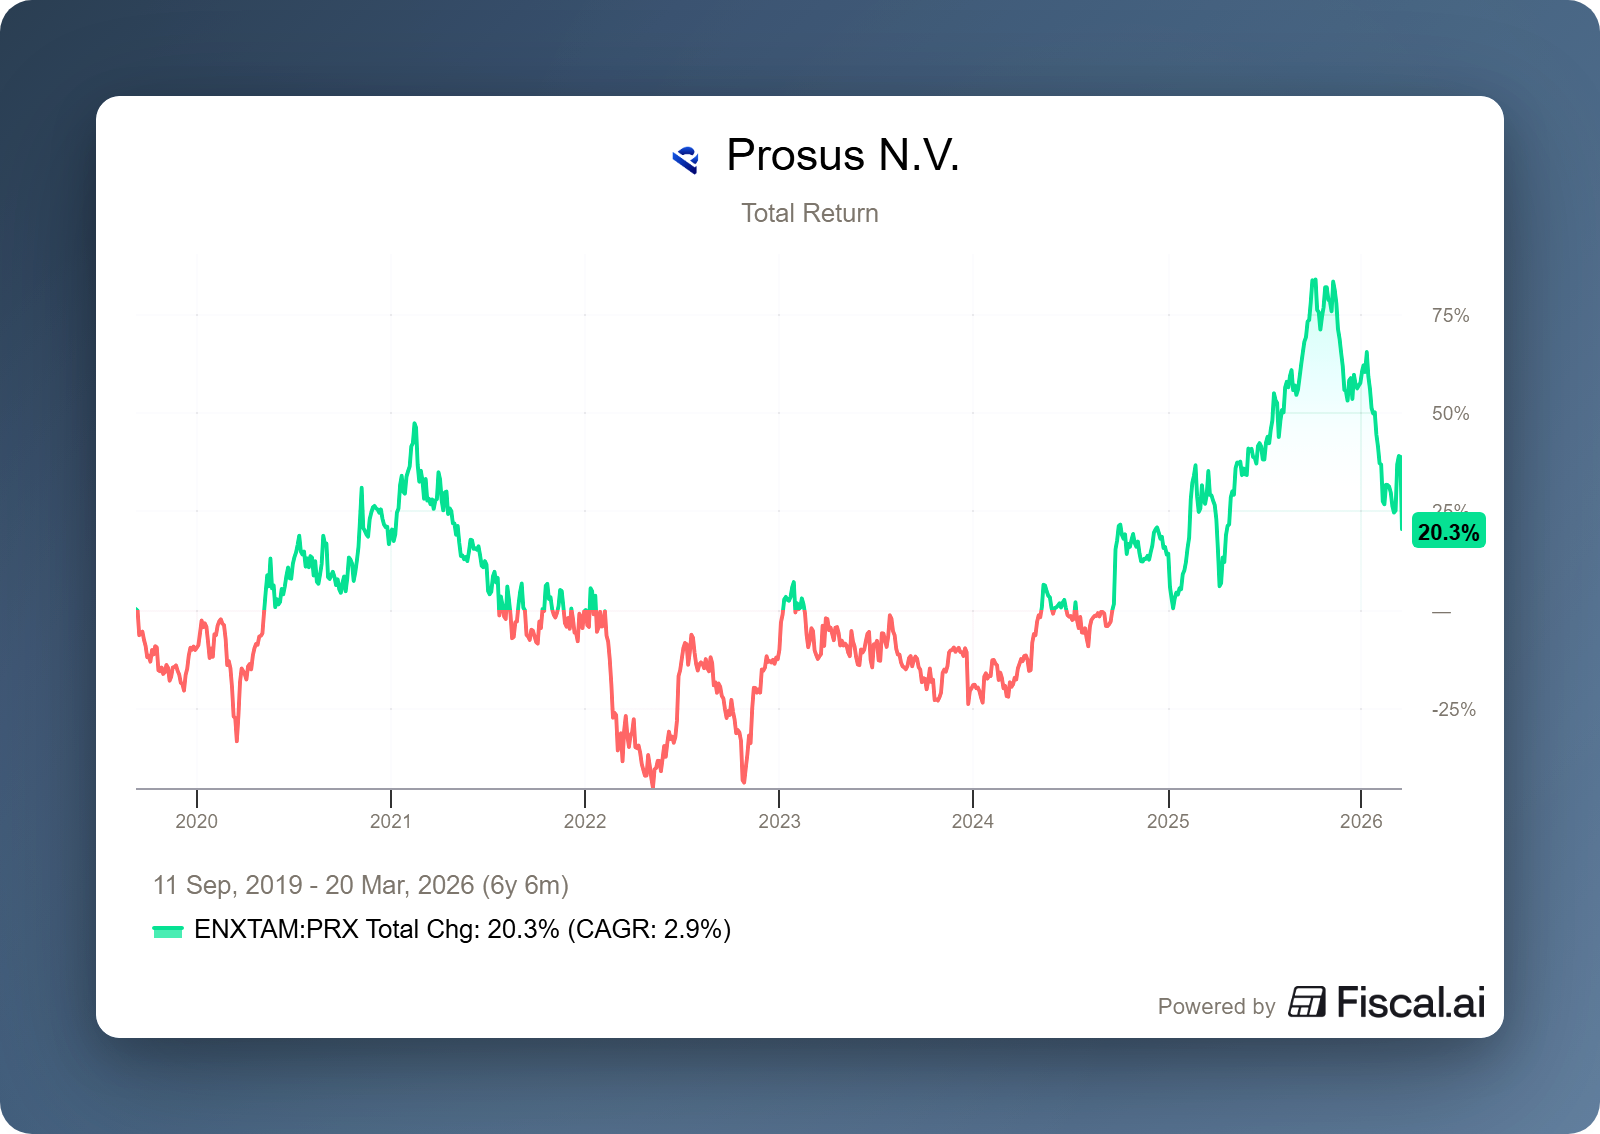
For shareholders in the Dutch investment holding company Prosus (Amsterdam: PRX), Tencent's results are the key gauge of intrinsic value. With a stake representing roughly 80% of Prosus's intrinsic value, Tencent acts as the primary driver behind the return profile. The 2025 results show a company that is financially robust and now intends to press ahead through larger AI investments.
A quick look at the numbers
Tencent closed the 2025 financial year with a set of robust results that exceeded market expectations at the operational level. Total annual revenue rose 14% to RMB 751.8 billion, and gross profit increased by as much as 21%. The company has thus been consistently proving for several years now that it can grow profit faster than revenue, causing profit margins to rise structurally.
Rather than simply chasing volume, management is succeeding in converting users within the WeChat ecosystem (Weixin) more effectively into profitable services. The fundamentals underpinning key growth pillars therefore remain undiminished:
International expansion: The gaming division outside China has by now become a fully-fledged growth engine. With annual revenue surpassing the $10 billion mark for the first time, driven by 33% year-on-year growth, the company's reliance on its home market in China is declining. This is fundamentally positive for the company's risk profile.
Advertising efficiency: Thanks to the integration of AI algorithms, Tencent is able to serve more relevant advertisements, which translates directly into higher prices per advertisement and a greater willingness among advertisers to shift budgets towards Tencent.
Cloud coming of age: A crucial turning point this year is that the cloud operations were profitable over a full financial year for the first time, with an operating profit of approximately $726 million. It proves that years of investment in infrastructure are finally starting to pay off.
The market likes AI applications, but not AI investments
Despite these strong operational results, the stock market reacted critically, causing the share price to fall by more than 7%. The dissatisfaction is not aimed at yesterday's figures, but at management's choices for tomorrow regarding AI investments.
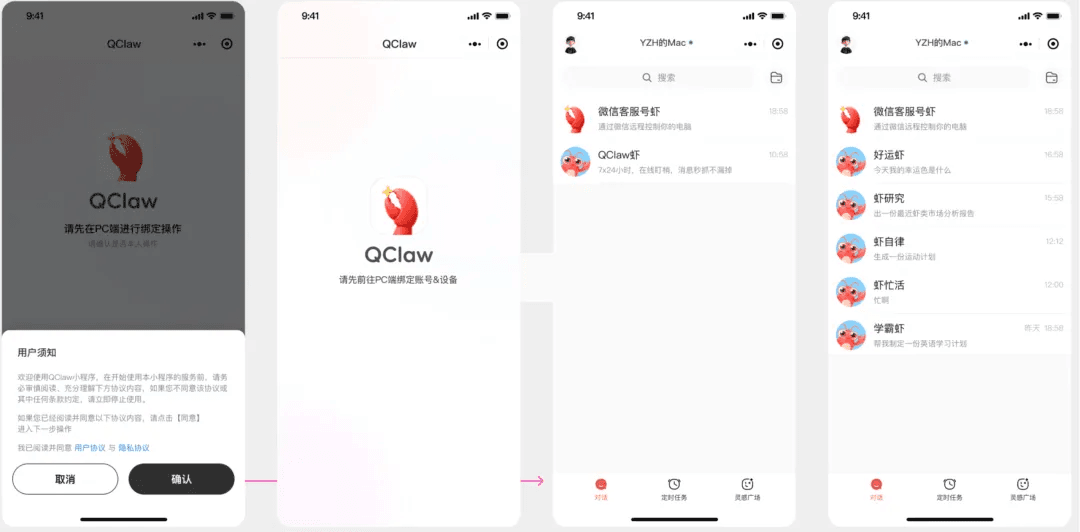
The contrast with the week before the results is stark. Back then, the share price rose sharply on news of the sponsorship of the OpenClaw community and the launch of QClaw, an AI assistant that has since entered public beta. This "digital version of yourself" is deeply integrated into WeChat and allows users to perform complex tasks on their computer via their smartphone. Now that Tencent has officially announced it will scale up AI investments (both opex and capex) to record levels in 2026, the market suddenly reacted with displeasure. The reason for this is that management has decided to moderate the volume of share buybacks compared with 2025 in order to finance these multi-billion-dollar investments.
The fundamental question is whether Tencent is striking the right balance between capital allocation and innovation at this point in the AI cycle. On the one hand, there is the conviction that Tencent should not have to choose between investing and rewarding shareholders at all. With a 'triple-A' balance sheet, a net cash position of $15 billion and a substantial investment portfolio, its financial firepower is enormous. Precisely because there is currently scepticism about AI spending and the share price is under pressure, buying back its own shares seems lucrative at this moment. Tencent could even justify taking on a modest debt position in order to win the AI race while simultaneously benefiting from the historically low valuation by aggressively buying back its own shares.
On the other hand, the risk of falling behind in the AI race is many times greater than the short-term gain from buybacks. In the technology sector, the return on share buybacks ultimately amounts to nothing if a company loses its growth trajectory to the competition. From that perspective, strengthening the operational foundation is a necessary survival strategy that safeguards the company's 'moats' over the long term.
Although the call for a more aggressive buyback programme at these share price levels is understandable, the strategic rationale for the current focus on AI integration appears sound. Moreover, the market impact of the lower buybacks is partly offset by the fact that Prosus is currently selling fewer Tencent shares to finance its own share buyback programme, which somewhat neutralises the pressure on Tencent's share price. Now that Tencent is clearly choosing to go on the offensive in 2026, this may cause considerable volatility in the short term, but at the same time it strengthens the foundation under Prosus for years to come.
Prosus ended the trading week on the Amsterdam stock exchange at a price of EUR 40.02 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Scottish Mortgage as insurance against change
The managers of Scottish Mortgage Investment Trust (London: SMT) describe the current AI transition as the most impactful technological shift the world has ever seen. According to managers Tom Slater and Lawrence Burns, it is crucial for investors not to bet on one specific segment, but to spread exposure across the entire value chain. In a recent series of updates, they gave insight into how they are positioning the investment holding company as an "insurance against change".
During an extensive Q&A session, the managers went into more detail on the specific choices within the portfolio, the challenges surrounding private holdings, and their view on the future of tech giants. Curious about the full interview? Watch the complete Q&A video here:

A luxury problem with SpaceX
One of the most pressing questions for investors in Scottish Mortgage is how the holding company deals with its very biggest successes. SpaceX has now grown to 15.4% of the total portfolio, which brings a luxury problem with it: the trust applies a self-imposed limit of 30% for private (non-listed) holdings. Due to the enormous increase in SpaceX's value, exposure to private companies has grown to 37.3%, meaning the holding company is formally above its limit.
Because the breach has come about through the increase in value of existing positions rather than additional purchases, it is permitted within the policy, and the fund is not forced to sell holdings. However, it does bring the constraint that the holding company cannot make any new private purchases under its own rules as a result. Management therefore confirmed that they are looking at an adjustment to the policy in order to clear the way for new 'moonshots'. To create more flexibility, the board proposed a concrete policy adjustment this week. Although the general 30% limit for the managers will remain in place, under the new rules the trust would gain the ability to invest up to £250 million extra in private companies, even if exposure already exceeds 30%.
With rumours of a SpaceX IPO in the course of 2026, a large part of the portfolio would automatically shift from 'private' to 'public'. It seems unlikely that Scottish would sell its entire stake at an IPO; the investment holding company is known for holding on to winners for years on the public market, as long as the growth potential remains intact. In the case of SpaceX, Lawrence Burns only sees this growth path broadening further, partly due to the close integration with xAI. According to Burns, this integration would allow SpaceX to control the entire AI value chain, with space providing the solution to the enormous energy and cooling constraints facing data centres on earth.
Although this vision of the future forms the basis for the current valuation for many investors, it remains very much an open question how SpaceX is going to make the enormous launch costs and the complex technical challenges of hardware maintenance in a vacuum profitable.
Why not invest in AI via an index
A frequently heard argument is that investors also gain exposure to AI (via Nvidia or Microsoft) through a cheap tracker on the Nasdaq or S&P 500. Scottish Mortgage puts forward two crucial advantages of buying shares in the trust instead.
Firstly, access to private markets. Through stakes in companies such as Anthropic (a direct competitor of OpenAI), the trust offers access to the 'frontier' of AI models that are out of reach for ordinary investors. Burns on Anthropic: "The recent sell-off in software names was driven by Anthropic's latest 'agent' product. That gives you a sense of the disruptive power. We simply don't yet know where the limits of this impact lie."
Secondly, diversification across the entire 'stack'. Where trackers often lean heavily on hardware (Nvidia), Scottish also invests in the infrastructure and application layer. The goal is not to track the index, but to own the winners of the future before the rest of the market discovers them.
A third crucial argument is the structural shift whereby companies are postponing an IPO for longer and longer. As private markets have matured and enormous amounts of capital are available for large deals, the need to go to the public market for financing has diminished. This has major consequences for index investors, since a company's most explosive growth phase increasingly takes place entirely out of sight of the public market.
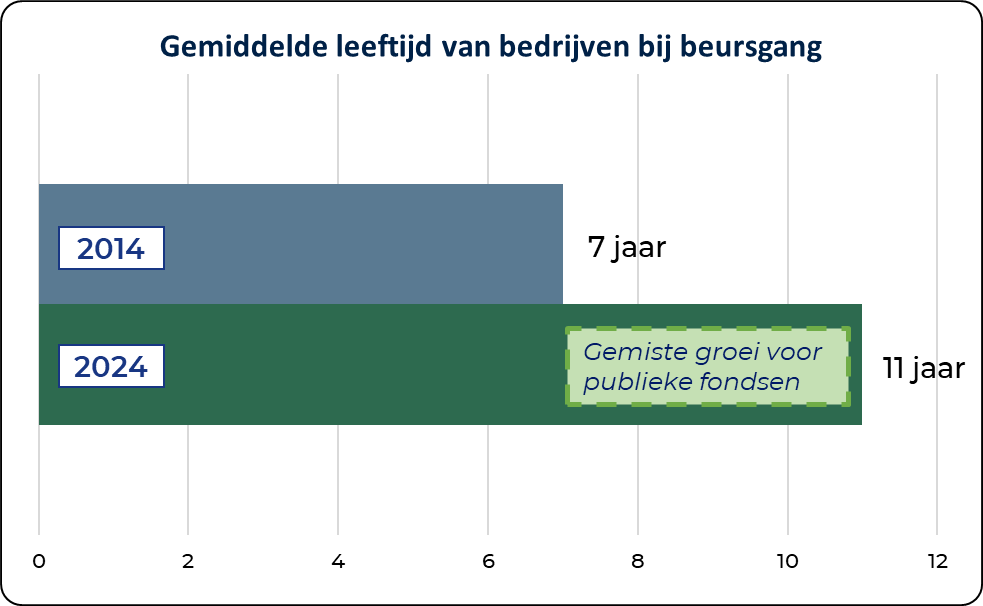
Whereas a company used to go public to raise capital for expansion, this now only happens once the model has already been fully proven and scaled. As a result, the index investor only gets in at a company's 'maturity' and misses the years in which the greatest value creation takes place. Scottish Mortgage thus offers access to a phase of the economy that simply remains invisible to regular tracker funds.
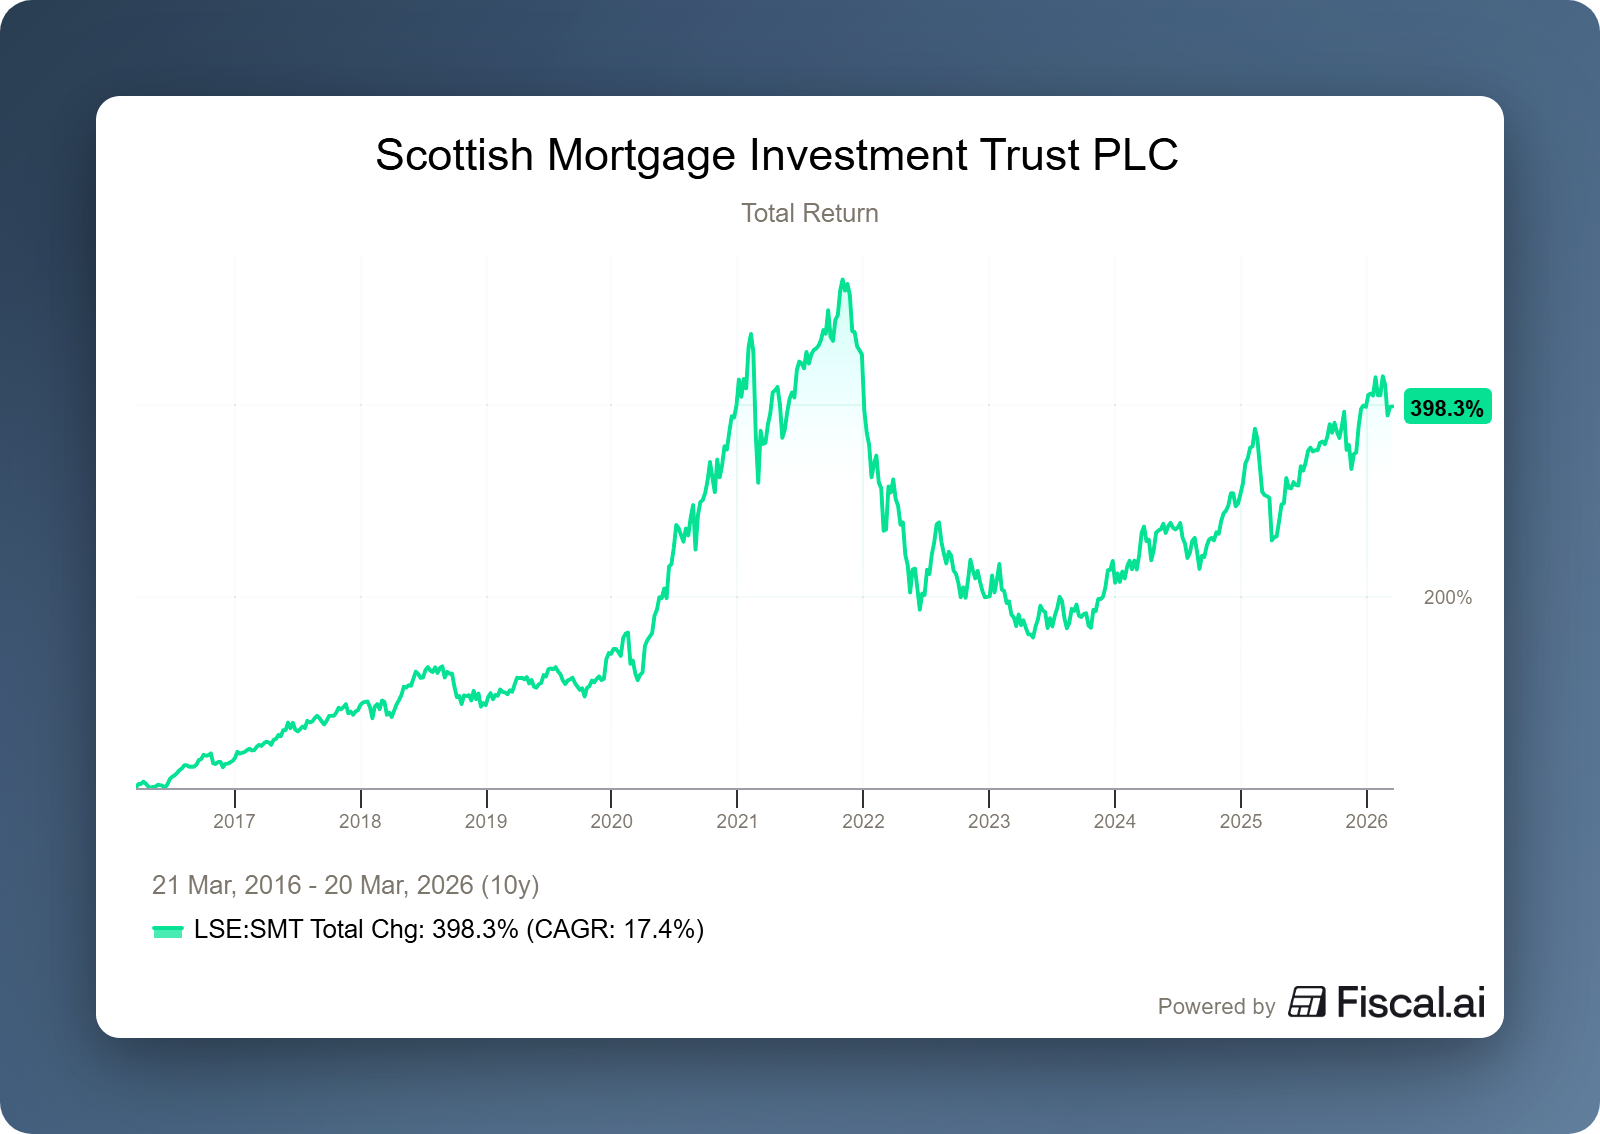
Scottish Mortgage Investment Trust ended the trading week on the London Stock Exchange at a price of GBP 11.70 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you begin investing. The value of your investments may fluctuate. Past performance offers no guarantee for the future. You may lose (part of) your investment. Tresor Capital disclaims any liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



