
Economy & Markets #19 - "Emerging Markets" beat Europe, climate doom scenarios shelved

This week's topics:
Are the stock markets in a melt-up? Are there signs of overheating?
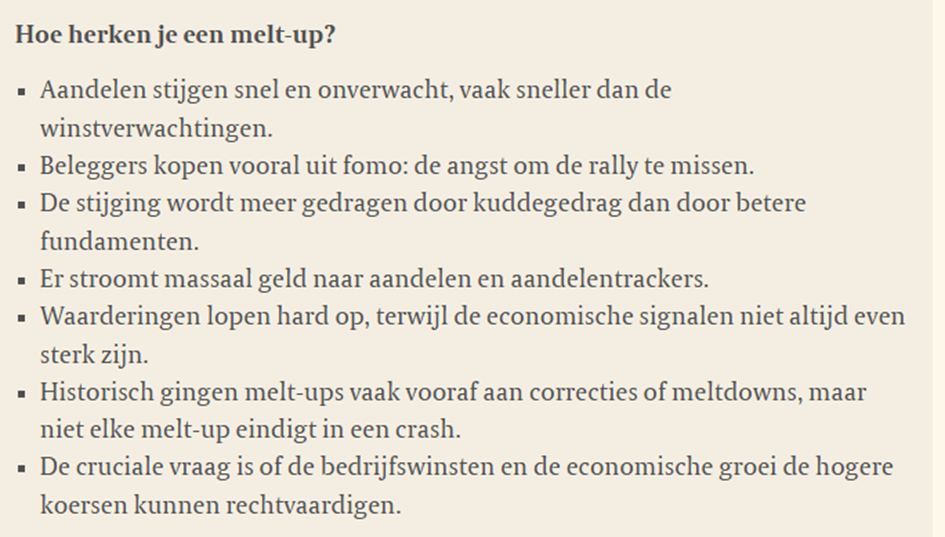
De Tijd argues that global stock markets may be in a "melt-up": a phase in which equities rise rapidly due to euphoria and fear of missing out, rather than fundamental valuation. Technology and semiconductor stocks in particular are being propelled upward by optimism around AI. Typical signs of such a melt-up include strong price momentum, massive inflows into popular themes, rising valuations, and investors increasingly ignoring risks.
It is often said that if you cannot cope with sharp price declines, you are better off not investing at all. This idea, that volatility is simply part of investing, is often attributed to Warren Buffett. But the reverse question is at least as relevant: how should investors deal with sharp price increases?
If you find it hard to be bullish during a bull market maybe the stock market is not for you.
— J.C. Parets (@JC_ParetsX) May 6, 2026
That is an important distinction. Rising markets, just like sharp price corrections, are not automatically irrational. Sometimes the market is anticipating real earnings growth, technological breakthroughs or productivity improvements. Investors such as Larry Fink, Paul Tudor Jones, Stanley Druckenmiller and George Soros would probably emphasise that powerful trends can persist for longer than rational valuation models suggest. Momentum can be self-reinforcing, especially when capital flows, earnings expectations and technological narratives feed off one another.
For investors, the art is not to view every strong rise immediately as a bubble, but to recognise when enthusiasm tips over into euphoria. AI could be a structural growth wave, while some share prices are temporarily running too far ahead of themselves. The key question, therefore, is not whether AI will become important, but how much future earnings growth is already priced in. Precisely during a melt-up, discipline remains crucial: moving with the trend, but not losing sight of valuation, cash flows and risk management.
Yardeni remains optimistic about the US
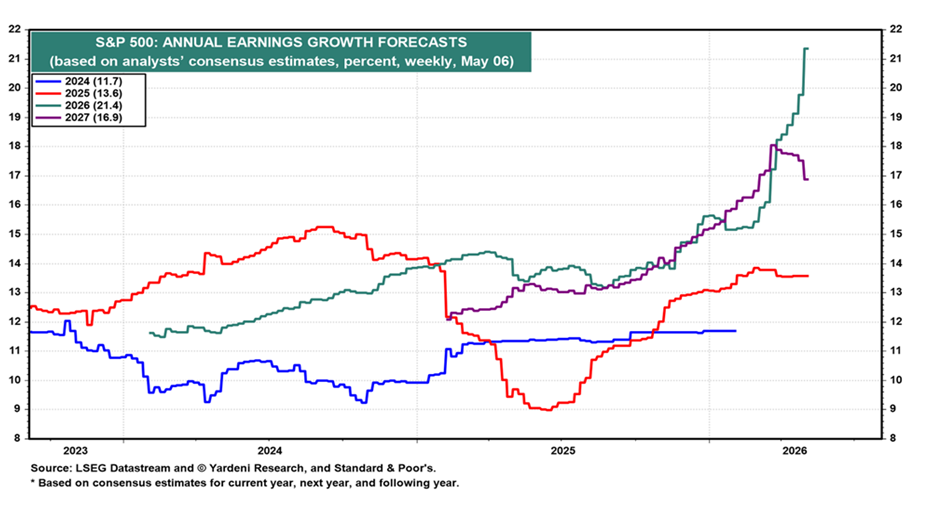
Ed Yardeni points out this week that the current melt-up in equity prices coincides with a strong acceleration in US earnings growth. For this year, S&P 500 earnings are expected to grow by 21.4%, followed by 16.9% next year. Share prices are indeed rising at an unprecedented pace, but so is earnings growth. That makes this rally fundamentally different from a purely speculative multiple expansion. In Yardeni's charts, earnings developments track the Nasdaq almost one-to-one: the market is rising sharply, but underlying earnings are keeping pace almost as strongly. Incidentally, the bulk of the earnings growth is attributable to the Magnificent 7; excluding these names, earnings growth for S&P 500 stocks still stands at 14% year-on-year.
Ed Yardeni is a well-known American economist and market strategist. He built his reputation as a Wall Street economist and became particularly known as one of the sharpest Fed watchers. In the 1980s he also introduced the term "bond vigilantes": bond investors who discipline governments through higher interest rates when fiscal policy becomes too loose. In recent years, Yardeni has been particularly positive about the US. He speaks of the "Roaring Twenties": a decade in which technology, productivity growth and a strong private sector would carry the American economy.
Yardeni also points out that the PEG ratio, i.e. the price-earnings ratio divided by expected earnings growth over the next two years, is currently notably low, with a reading of 1.0. That contrasts sharply with the run-up to the dotcom crisis, when this ratio rose to 1.8.
The comparison with Europe is also relevant in this respect. European equities appear cheaper at first glance, because price-earnings ratios are generally lower than in the US. For example, the STOXX Europe 600 traded at a forward P/E of around 15.9 at the start of 2026. However, this lower valuation must be weighed against significantly lower earnings growth.
Goldman Sachs projects EPS growth of 5% for the STOXX Europe 600 in 2026 and 7% in 2027, or roughly 6% per year on average. For the US, by contrast, Yardeni shows EPS growth of over 21% this year. When you look not only at the P/E ratio but also at expected earnings-per-share growth, a different picture emerges. Europe may then be less cheap than it appears, and on a PEG basis even more expensive than the US. Assuming a forward P/E of 14.67 and average expected earnings growth of around 6%, Europe's indicative PEG ratio comes out at roughly 2.4.
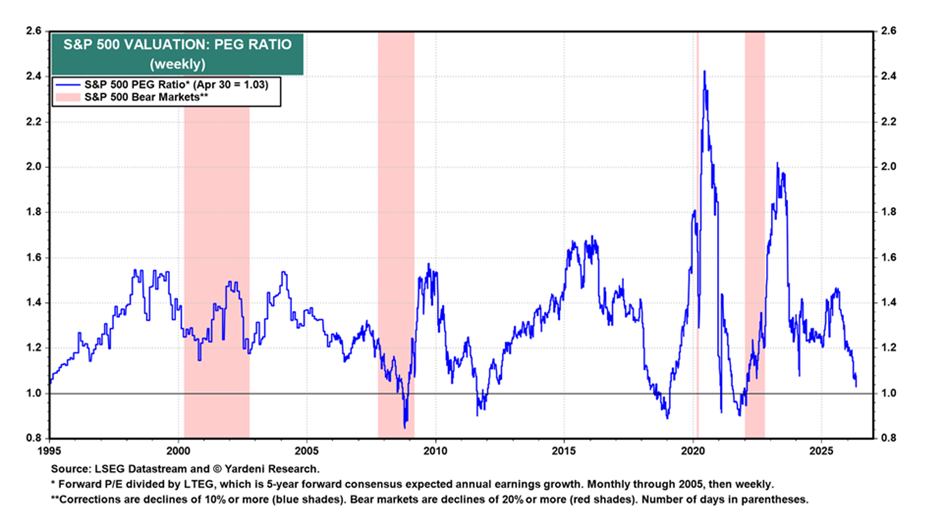
In other words, investors in Europe may pay less for each euro of current earnings, but in return they also get considerably less future earnings growth. As a result, Europe's apparent valuation discount largely disappears once earnings growth is taken into account.
The same report also points out that other cylinders of the US economy are running at full power. The labour market is recovering, despite fears that AI would trigger waves of layoffs, and inflation remains contained. For comparison: the petrol price in the Netherlands is around €2.46 per litre, versus about €1.02 per litre in the US. It is therefore hardly surprising that President Trump, as expected, is distancing himself from the Iran war. The US economy is doing what it is supposed to do: keep running.
Korea and Taiwan show that "emerging markets" are no longer laggard regions
South Korea and Taiwan show that the traditional distinction between developed markets and emerging markets is becoming increasingly blurred. Classically, emerging markets were seen mainly as economies with lower incomes, greater dependence on commodities or cheap manufacturing, less deep capital markets and higher political or currency risks. That picture increasingly fails to fit countries like South Korea and Taiwan.
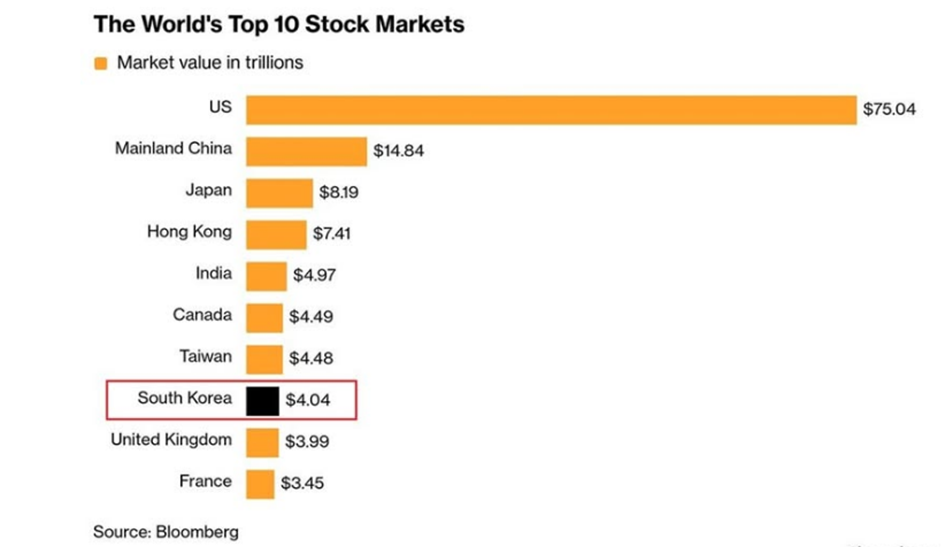
At the end of April 2026, South Korea overtook the United Kingdom as the world's eighth-largest stock market. The total market value of listed Korean companies rose by more than 45% this year to around US$4.04 trillion, while the UK market grew by only about 3% to US$3.99 trillion. As recently as the end of 2024, the UK stock market was roughly twice the size of South Korea's.
That is a structural shift. South Korea and Taiwan are no longer classic emerging markets competing mainly on low wages, cheap manufacturing or rapid industrialisation. They now sit at the heart of the world's most strategic value chain: semiconductors, memory chips, high-bandwidth memory and AI infrastructure. Samsung Electronics, SK Hynix and TSMC are not regional champions but systemic players in the global technology sector.
The driver behind this shift is clear: artificial intelligence. Samsung Electronics and SK Hynix are benefiting strongly from demand for memory chips and high-bandwidth memory for AI data centres. The KOSPI index has risen by around 75% in 2026. Taiwan's TAIEX index gained about 42%, driven mainly by TSMC and the broader AI chip supply chain.
As a result, South Korea and Taiwan are performing far more strongly than classic developed markets such as the United Kingdom, France and Canada. For comparison: the FTSE 100 was up only around 4 to 5% year-to-date at the start of May 2026, while the French CAC 40 moved roughly flat to slightly positive on balance. The Canadian S&P/TSX Composite did perform strongly on an annual basis, rising by around 35%, but clearly lagged South Korea and Taiwan in terms of AI-driven momentum.
This is precisely why the "emerging market" label sits so uncomfortably. South Korea and Taiwan are still classified by MSCI as emerging markets, even though they have long been at the forefront economically, technologically and in terms of market performance. Traditional market labels are lagging behind reality here. These are no longer countries that are merely "emerging"; they form an essential part of the world's AI infrastructure.
FTSE Russell has already gone a step further and classifies South Korea as a developed market. Taiwan is still considered an advanced emerging market there. The difference lies mainly in market accessibility: currency, settlement, foreign registration, short selling and other operational frictions for international investors. In other words, the discussion increasingly concerns not the quality of the economy or the technology, but how easily international investors can gain access to the market.
SK Hynix is also moving in that direction. The company has begun the process for an ADR listing in the US. An ADR, or American Depositary Receipt, makes it easier for international investors to invest in a foreign company via the US market. This would further increase SK Hynix's accessibility and strengthen its visibility among global investors.
Falling token costs are positive for hyperscalers
In Decoding the Agentic Economy – The Coming Inflection in AI Usage and Margins, Goldman Sachs argues that the next phase of AI will revolve mainly around agentic AI: systems that not only provide answers but independently plan, execute and adjust tasks. Think of assistants that book trips, monitor emails, write software code or handle business processes.
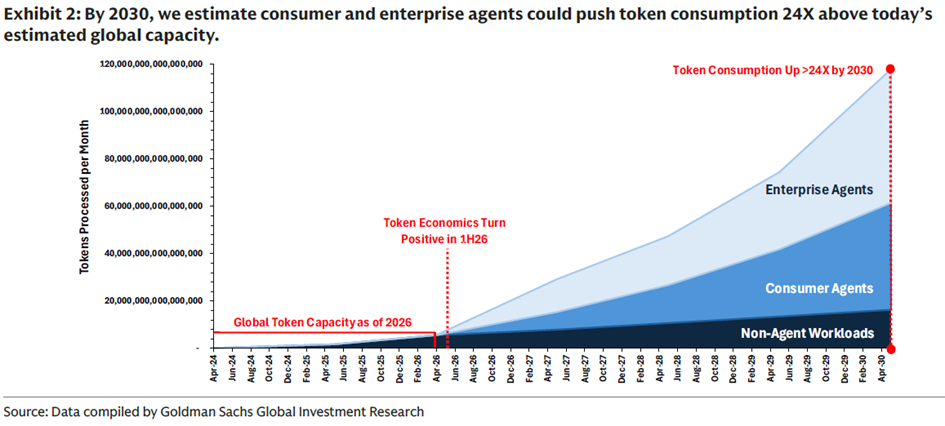
Central to this is the expected explosion in token consumption. The more complex and autonomous AI tasks become, the more tokens are needed. According to Goldman Sachs, global token consumption could rise to around 24 times today's level by 2030. In particular, “always-on” consumer agents and corporate agents could sharply drive up that demand, as they continuously retrieve context, validate decisions and control multiple systems at once.
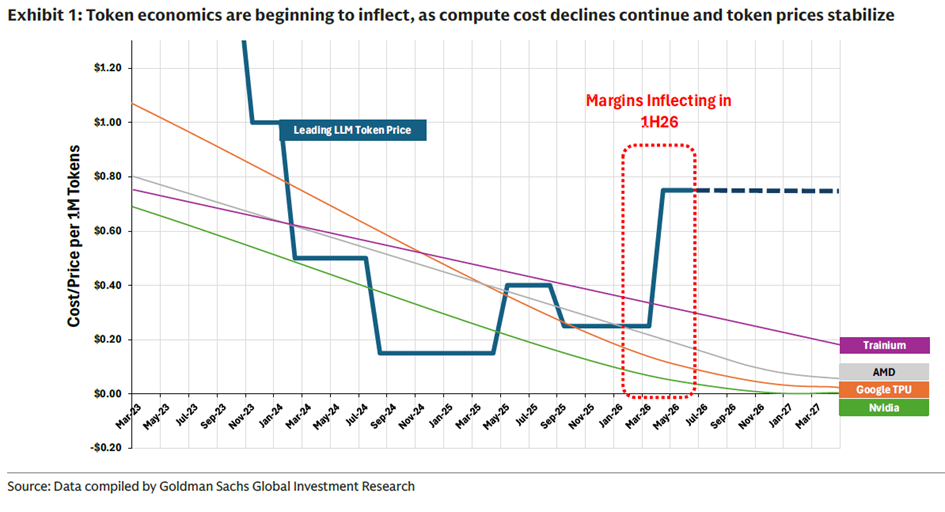
Goldman Sachs sees not only strong growth in AI usage, but also an improvement in the economics of AI. The cost per token is falling rapidly thanks to more efficient chips, better models and higher utilisation of infrastructure, while token prices appear to be stabilising. As a result, additional AI usage can lead not only to more revenue, but also to higher margins.
For hyperscalers such as Amazon, Alphabet/Google and Meta, this could mark an important turning point. In the first AI phase, increased usage was mainly seen as a cost item: more inference, more chips, more power and higher investments in data centres. That picture is now starting to shift. If token volumes rise sharply while the cost per token keeps falling, the large AI investments become economically easier to justify.
On top of that, AI agents can make more intensive use of existing and new infrastructure. Higher utilisation rates lower the effective cost per token and make more complex AI services more profitable, such as agents that run continuously in the background, automate business processes or control multiple systems at the same time.
Finally, scale and proprietary chips strengthen the competitive position of hyperscalers. Companies with their own infrastructure and chips, such as Google's TPUs, Amazon's Trainium and Graviton, can bring down token costs faster than players fully dependent on external compute. That scale advantage could make the AI economy structurally more profitable.
Climate scenarios: from doomsday scenario to more realistic policy and more efficient capital markets?
For years, the IPCC's RCP8.5 or SSP5-8.5 climate scenario played a major role in climate reports, policy, legal proceedings and investment documentation. This scenario assumed prolonged, very high fossil fuel use, especially coal, and a temperature rise towards the end of this century of roughly 4 to 6 degrees Celsius. For what was then the Dutch-British Shell, this extreme scenario meant that the court sought to impose an exact reduction percentage, such as a 45% CO₂ reduction by 2030.
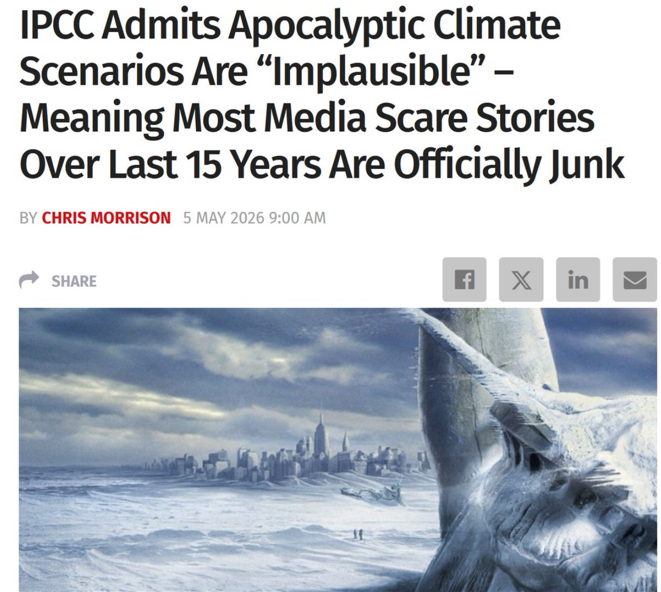
Just this week it emerged that this temperature pathway may no longer be presented as a realistic "business as usual" expectation. That nuance matters for the broader climate debate and policy. As early as 2020, climate researchers Zeke Hausfather and Glen Peters warned in Nature that presenting the highest emissions scenario as the most likely outcome could be misleading.
This is equally relevant for investors. Many institutional portfolios, climate models and ESG products are partly built around this extreme climate scenario, which in hindsight may have been applied too extremely or too simplistically. In theory, markets should continuously re-examine such assumptions. In practice, however, investors, regulators, consultants and policymakers often follow the same dominant narratives. And they turn out to be less inclined to revise a course once it has been (wrongly) set. As a result, there is a risk that climate risks are priced not only economically, but also on policy or emotional grounds.
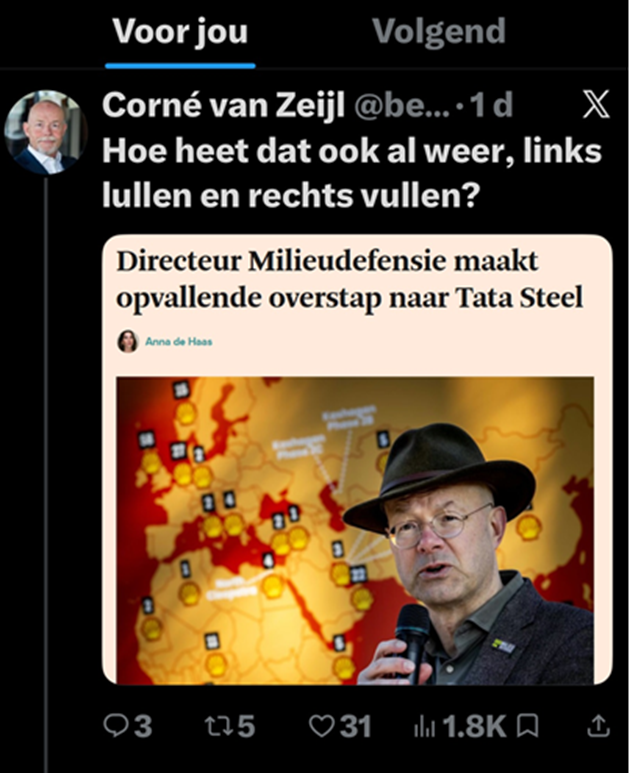
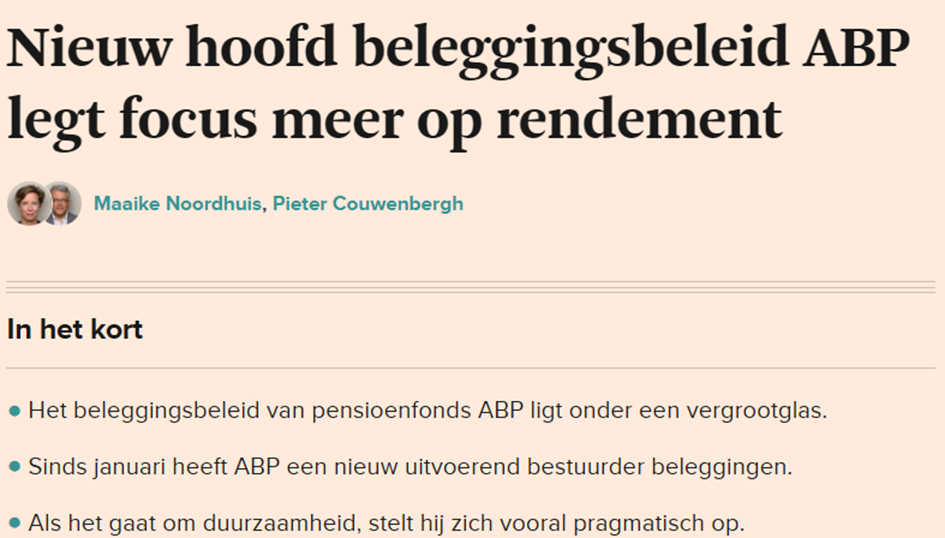
Dutch pension funds have won many sustainability awards in recent years, but in recent months criticism of their lagging returns has been growing. For example, the ABP pension fund posted a negative investment return of -1.6% over 2025. That compares poorly with broad market benchmarks: the MSCI World Index in euros achieved a return of +7.21% on a gross-return basis in 2025, while the Bloomberg Global Aggregate Bond Index EUR Hedged came in at +2.68%. Admittedly, interest-rate hedging is likely the most important return factor in an environment of rising rates. But in addition, active policy, including the exclusion of companies on sustainability grounds, has contributed to the disappointing results.
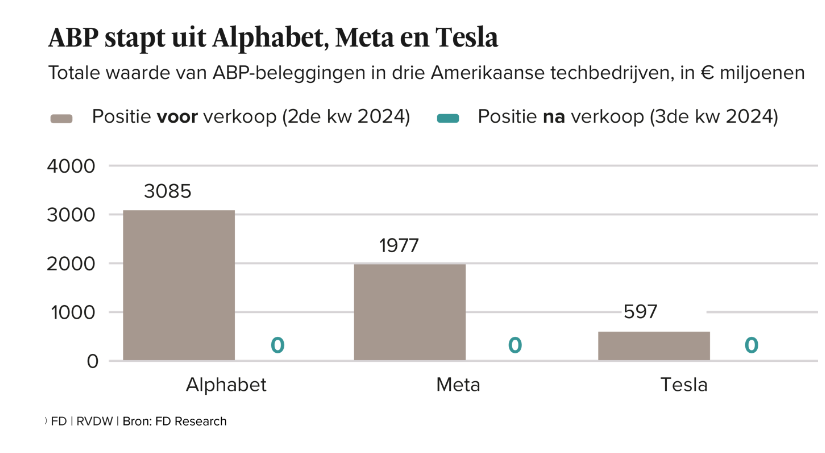
The debate on sustainable pension investing is thus shifting from intention to outcome. At ABP, for instance, critics point out that the rapid divestment from fossil fuel holdings has, in hindsight, cost returns, since oil and gas shares in fact performed strongly after the divestment decisions were made. Some commentators even speak of billions in missed returns. A similar debate is playing out around the exclusion of defence companies on ESG grounds, precisely at a time when geopolitical risks and defence spending have risen sharply.
This shift can also have legal consequences. For states and companies, the diminishing weight given to extreme climate scenarios creates room to question damage projections more critically. Claims that rely heavily on 4 to 6 degrees of warming will need to better justify why such a scenario is still representative today.
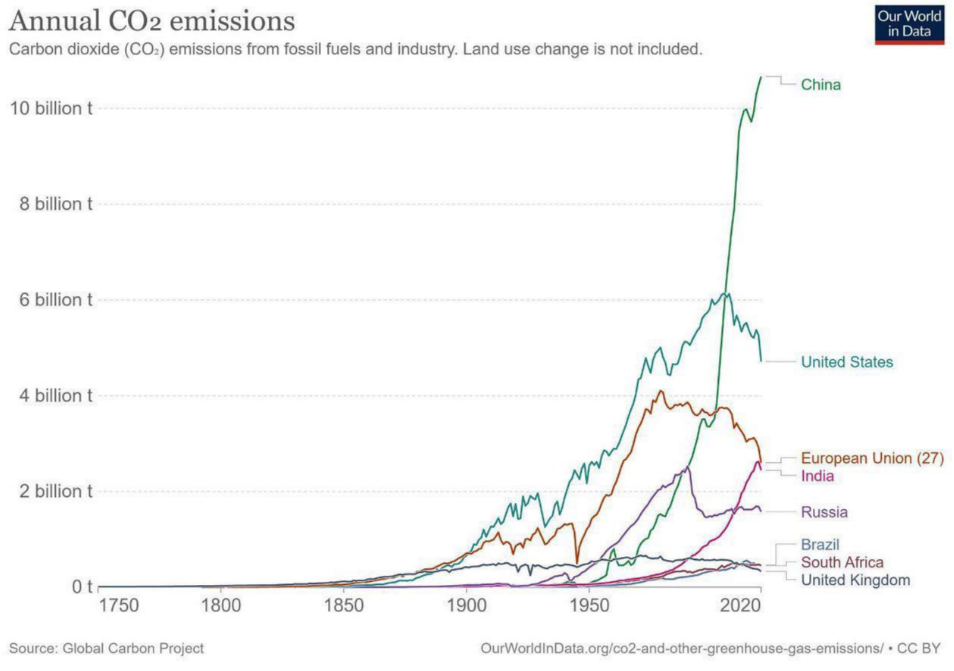
This sharpens the key question: what has the use of these extreme scenarios ultimately delivered? If climate policy, ESG rules and investment decisions are partly based on assumptions that appear increasingly unlikely, then recalibration is necessary. Not to downplay climate risks, but to manage them more realistically, economically and effectively. Simply relocating industrial production from Europe to China benefits no one.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to take up investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or on behalf of their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your investment. Tresor Capital disclaims any form of liability for any imperfections or inaccuracies. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



