
Economy & Markets #18 - Energy unrest and a wobbly Yen cannot stop the American AI rally

This week's topics:
Oil price nears new records as Trump threatens fresh attacks
Anyone who looked at the oil price over the past few weeks could have mistakenly concluded that stabilisation around USD 90 per barrel signalled a de-escalation of the conflict. Nothing could be further from the truth. The Strait of Hormuz remains largely blockaded and strategic reserves in Asia and Europe are being drawn down quickly. There is an estimated production loss of 15 million barrels of crude oil and refined products, such as kerosene, diesel and petrol. This represents a substantial disruption to global supply (roughly 15% outage).
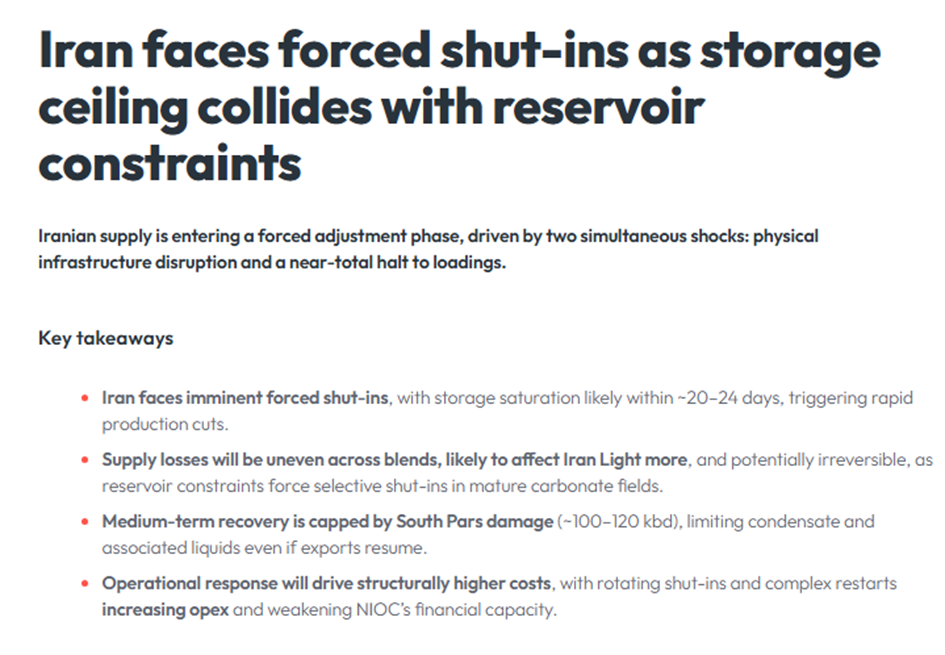
Through the blockade, the United States is seeking to further increase economic pressure on Iran and halt Iranian oil exports. If Iran is unable to export its oil to China and/or India, and is also unable to store it itself, there is a major risk that this will lead to a prolonged production interruption, causing lasting damage to Iranian oil fields. Iran has only limited storage capacity, and years of sanctions may mean it lacks the means to shut down oil fields in a controlled manner and later restart them without significant damage. If pressure in the fields drops or salt water intrudes, production capacity can be permanently lost.
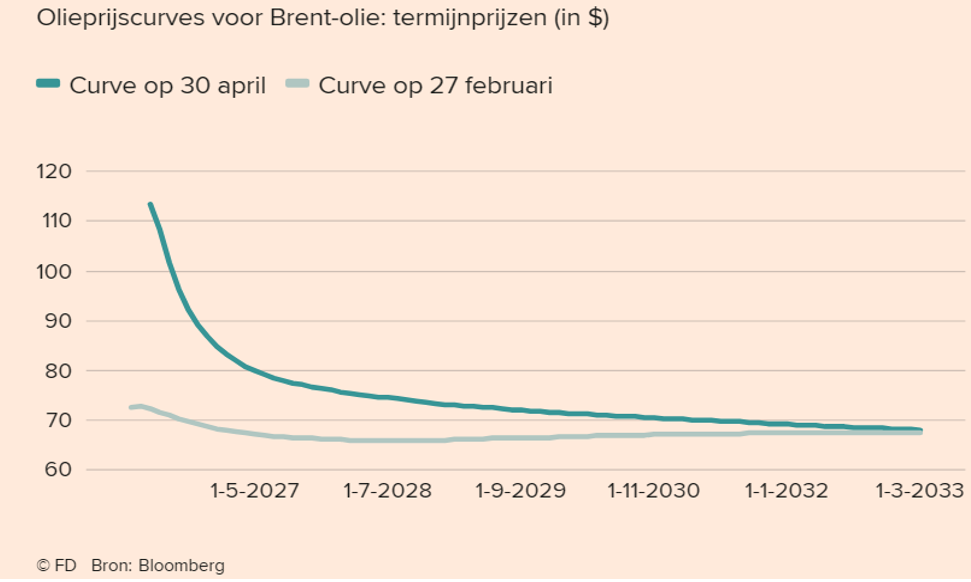
But Trump remains impatient, and now that he has threatened this week to further step up military pressure, oil prices are once again rising rapidly. The underlying market structure also points to persistent stress in the global oil system. The chart below shows that oil is still trading in backwardation: immediate delivery is priced at a premium relative to later delivery. This means the market is willing to pay extra for physical oil in the short term. Such a structure typically points to tightness in the prompt segment of the market and to uncertainty about the short-term availability of barrels.
Refining margins climb along with the oil price
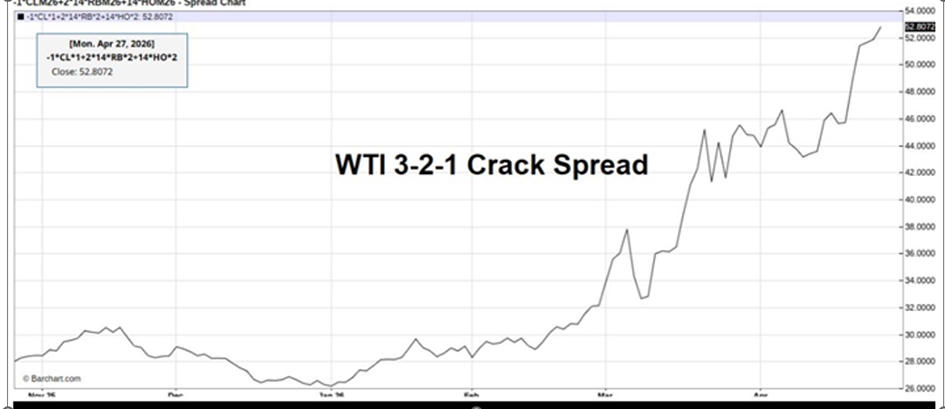
The crack spread below also shows that refining margins, in this case on the US Gulf Coast, have risen sharply. The US Gulf Coast 3-2-1 crack spread stood at around USD 41.75 per barrel in April. Although that is slightly lower than in March, it is still almost twice as high as a year earlier. Diesel and distillate margins in particular remain exceptionally high, pointing to tightness in refined products. These high margins matter more than the oil price alone. They show that the tension in the market is not confined to crude oil, but also extends to the availability of end products such as diesel, petrol and kerosene. When logistics routes come under pressure, transport costs rise, or refineries in Europe and Asia receive insufficient suitable crude oil, regional product shortages can arise.
At the same time, US refiners in particular are benefiting from a favourable combination of factors. They have relatively good access to crude oil and gas from North America, with Canadian oil in particular often trading at a discount to international benchmarks. At the same time, product prices remain high and crack spreads have risen sharply. Demand for petrol and kerosene typically increases in the summer due to the holiday season and higher mobility. In addition, diesel markets remain fragile. According to the EIA, US diesel margins are expected to remain historically high throughout the summer, partly due to persistent international supply pressure. As a result, US refiners have a competitive advantage: relatively cheap input on the one hand and high returns on refined products on the other. This strengthens the position of the United States not only as a major oil producer, but also as an increasingly important exporter of refined oil products.
Gulf states under pressure, cracks in OPEC oil cartel
The crisis surrounding Iran and the Strait of Hormuz affects the Gulf states in two ways. In the short term they benefit from higher oil and gas prices, but at the same time their export routes are becoming more vulnerable. Higher transport costs, insurance premiums and delivery risks make clear how dependent the region remains on safe passage through Hormuz. Countries that can export via pipelines, such as the United Arab Emirates and Saudi Arabia, and to a lesser extent Kuwait, can still partly export their oil and gas (with higher prices providing compensation). Qatar, by contrast, sees its entire gas exports disappear due to the closure of the Strait of Hormuz and damaged production facilities.
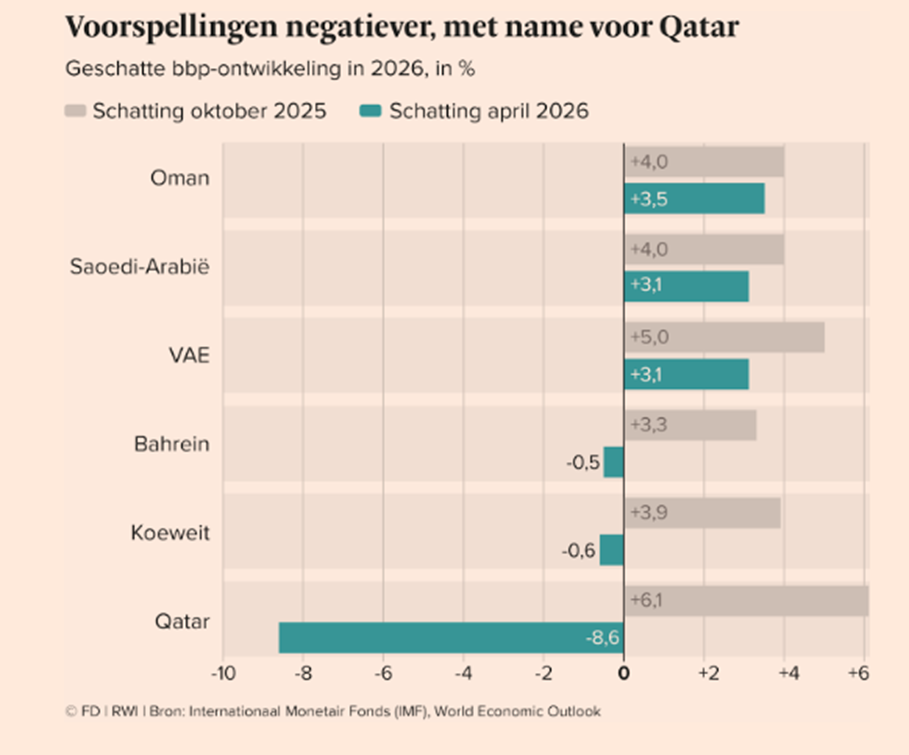
The departure of the United Arab Emirates from OPEC+ fits into this broader shift. The UAE wants more freedom to make use of its own production capacity and to be less bound by quotas that are dominated primarily by Saudi Arabia. Officially, this is described as a strategic and economic reorientation, but at its core it is about greater autonomy in a rapidly changing oil market.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Chinese President Xi prepares for mid-May summit. Growth holds up, risks remain
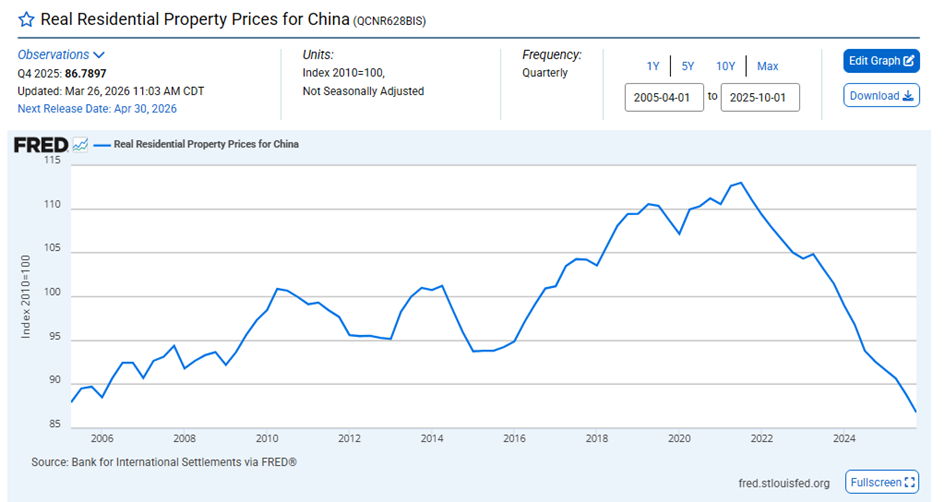
The Chinese economy is performing better than sentiment often suggests. In the first quarter, GDP grew by 5.0% year-on-year, keeping China close to its official target (which, incidentally, is hardly surprising). It is particularly the industrial side of the economy that is strong: industrial production rose by 5.7% in March, while high-tech manufacturing grew by 12.5% in Q1. The underlying picture remains mixed. Growth continues to lean mainly on industry, exports and policy support, while consumers remain cautious. Retail sales rose by only 1.7% year-on-year in March, and the property sector remains a clear drag. China's inflation eased to 1.0% year-on-year in March 2026, down from 1.3% in February. That 1.3% figure had been the highest level in three years. The decline was also larger than the market expectation of 1.2%, pointing to persistently weak price pressure and subdued domestic demand. House prices (see image) also continue to fall. For many Chinese people, a (second) home is the only form of wealth (besides savings), in other words, the structural price decline makes a future pension highly uncertain.
The labour market also gave a worrying signal. Youth unemployment among 16- to 24-year-olds, excluding students, rose from 16.1% in February to 16.9% in March. That was the highest level since November 2025 and broke the declining trend seen since September. Unemployment among the 25- to 29-year-old group, also excluding students, likewise rose, from 7.2% to 7.7%. So despite the energy crises, inflation is low, which points to limited domestic demand and an economy running on overcapacity.
Against this backdrop, Xi Jinping is heading into a summit with Donald Trump from a position of relative strength, though not without vulnerabilities. The key issues are trade, technology, critical minerals and Taiwan. China holds bargaining power through its position in supply chains and rare earths, while the US maintains pressure through tariffs, chip restrictions and sanctions. Trump is relatively strong at the negotiating table. The US remains dominant in technology, capital markets and defence, while recent conflicts have raised questions about the reliability of Chinese weapons systems in countries such as Pakistan, Venezuela and Iran. American high-tech weapons appeared superior to their Chinese counterparts, and Trump could also squeeze energy deliveries to China by blockading the Strait of Hormuz.
Japan caught between a weak yen, interest rates and energy imports
Japan appears to have intervened again to support the yen. Last Thursday, the currency rose by 2.5% within a few minutes. According to rumours, more than USD 70 billion in dollars were sold in the process, although this has not been officially confirmed.
The vulnerability is clear: Japan imports a lot of energy, meaning a weak yen makes oil, gas and commodities more expensive and increases inflationary pressure. At the same time, a stronger yen would require higher interest rates, but that would make financing the high national debt more difficult. The interest rate differential with the US is still 3% higher, which is drawing JPY into the USD.
Japan is thus caught in a bind: higher interest rates at the Bank of Japan (BOJ) support the yen but weigh on the debt position; low interest rates keep the debt affordable but weaken the currency further.
AI capex under the microscope after concerns about OpenAI
Concerns about AI capex increased this week following reporting by The Wall Street Journal on OpenAI. According to the newspaper, OpenAI has reportedly missed internal targets for revenue and user growth, while the company is taking on major commitments for data centres and computing power. This led to significant profit-taking in AI-related stocks, including Oracle, CoreWeave, Nvidia and SoftBank.
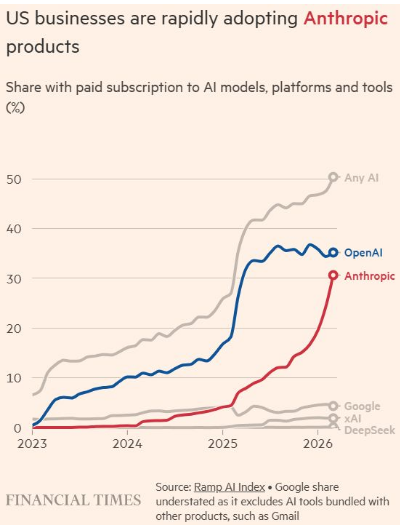
OpenAI pushed back against the negative picture and emphasised that the underlying business remains strong. Nonetheless, the discussion is shifting: it is no longer just about demand for AI computing capacity, but increasingly about who can keep financing the enormous investments in chips, cloud capacity, data centres and power.
AI capex is thus increasingly becoming a balance-sheet issue. For AI labs such as OpenAI and Anthropic, computing power is no longer just an ordinary cost item, but a strategic requirement for staying competitive.
This also explains why, according to Techzine/Bloomberg, Anthropic is exploring a new funding round, possibly at a valuation of USD 900 billion, with early proposals to raise around USD 50 billion.
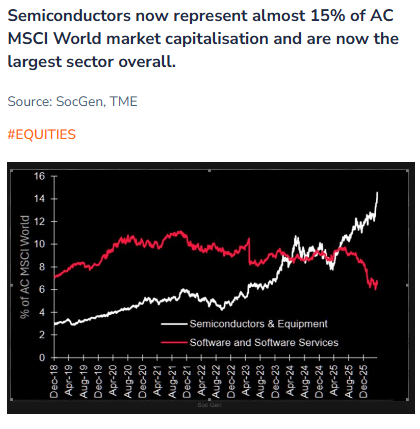
The strong performance of the semiconductor sector underscores that investors still view the AI infrastructure cycle as a structural growth story. The SOXX index is up around 50% this year, while the broader chip rally was also evident in an 18-day winning streak for the PHLX Semiconductor Index. As a result, the discussion is shifting from whether hyperscalers will keep investing to how quickly the entire supply chain can absorb these investments.
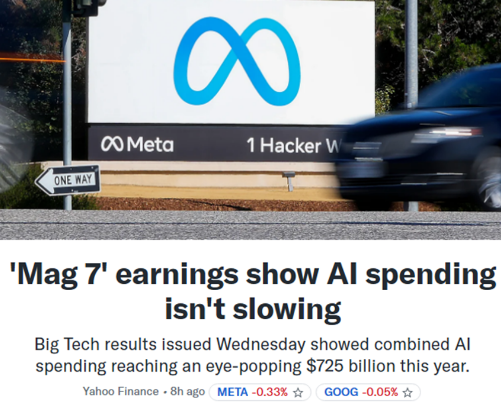
The direct beneficiaries remain producers and suppliers of AI accelerators, high-bandwidth memory, advanced packaging, networking, power management, data centre cooling and related infrastructure. As long as Meta, Alphabet, Microsoft and Amazon keep raising their investment budgets, demand for AI chips and associated infrastructure will remain firmly supported.
At the same time, the AI trade is broadening. The initial market reaction was concentrated mainly in chip companies such as Nvidia, Broadcom, AMD and TSMC, but investors are now also looking at the bottlenecks beyond the chip itself: data centre capacity such as Oracle and Nebius, power supply such as Caterpillar, Schneider Electric and Bloom Energy, cooling such as Schneider, and grid connections through players such as Siemens and ABB.
Capex overview of hyperscalers
All amounts in USD billion. YoY growth is calculated based on the midpoint of the range.
| Company | 2025 Capex | 2026 (New) | Adjustment | YoY Growth | 2027 Indication |
|---|---|---|---|---|---|
| Meta | 72.2 | 125–145 | +10 | +86.9% | No official guidance |
| Alphabet | 91.4 | 180–190 | +5 | +102.4% | Further increase expected |
| Microsoft¹ | ~80 | ~190 | ~+45 | +137.5% | No official guidance |
| Amazon² | ~131.8 | ~200 | No change | +51.7% | No official guidance |
All amounts in USD billion. YoY growth calculated on the midpoint of the range.
AI data centres can only grow if enough reliable electricity is available. It is precisely there that bottlenecks are increasingly arising, because new grid connections, gas-fired power plants and transmission infrastructure require years of planning, permitting and construction time. Due to strong demand for gas turbines from, among others, GE Vernova and Siemens, delivery times are in some cases stretching to several years, with estimates of up to around seven years.
Bloom Energy is a company that is benefiting directly from these delays. The company supplies modular fuel cells that can deliver on-site power to data centres and industrial customers. In doing so, Bloom is addressing one of the biggest bottlenecks within the AI infrastructure cycle: reliable electricity. The market increasingly regards Bloom as a winner of the second phase of the AI trade: not the chip itself, but the power behind the chip.
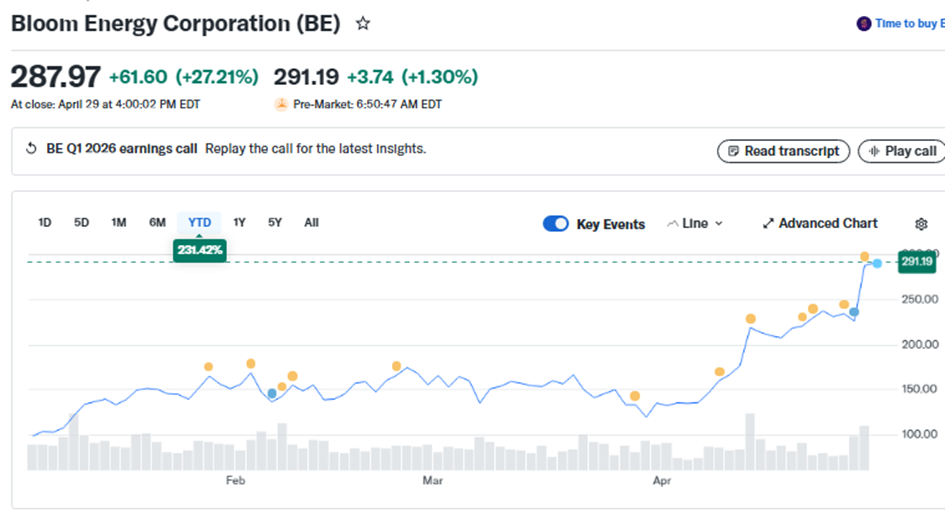
This is also visible in the figures. Bloom reported revenue growth of 130% for the quarter and raised its revenue guidance for 2026 to USD 3.4–3.8 billion, equating to roughly 80% growth. The share price reaction was also substantial: the stock is trading considerably higher this year and has risen very sharply over the past twelve months. Notably, one of the external managers we have selected for clients holds Bloom Energy with a weighting of more than 10% in its portfolio.
Powell remains a factor within the Fed, Warsh moves to the fore
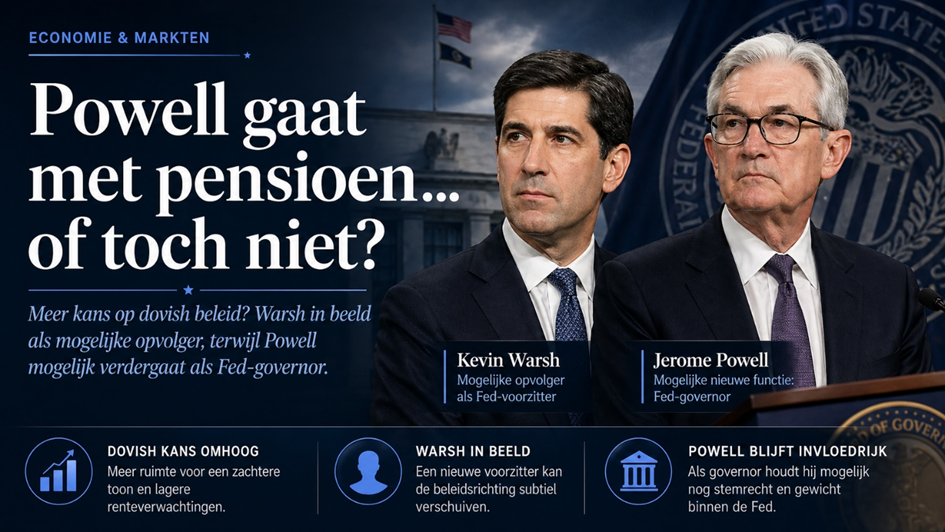
Jerome Powell remains influential within the Fed for the time being, even though his term as Fed Chair ends on 15 May 2026. His separate term as a member of the Board of Governors runs until 31 January 2028, meaning he retains institutional weight even without the chairmanship.
The Fed is keeping its policy rate stable for now within the 3.50–3.75% range. Persistent inflation risks and a resilient US economy make swift rate cuts less likely. At the same time, a rate hike is not immediately obvious either, as long as higher energy prices and other price pressures do not convincingly feed through into underlying inflation.
Kevin Warsh is regarded as Powell's presumptive successor. He is seen as a candidate who may place more emphasis on growth, the labour market and a more clearly defined role for the Fed. That could make the tone somewhat more dovish over time, but does not automatically mean that rate cuts will follow soon. His appointment goes through the Senate; the Senate Banking Committee has already approved his nomination.
For long-term US interest rates, the picture remains less dovish for the time being. As long as the economy stays resilient and inflation risks persist, the 10- and 30-year yields could remain relatively high, at around 4.4–4.5% and roughly 5% respectively, even if the market later starts pricing in more rate cuts.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts of it, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your invested capital. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is indicative only and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



