
Family Holdings #18 - The week of the cloud


This week's topics:
Markel Group saw its market value fall by 7% following an apparently weak first quarter of 2026, marked by a 21% decline in premiums and paper losses on its investment portfolio. However, this contraction is the result of a strategic clean-up in which loss-making divisions (reinsurance) were divested, resulting in significantly improved underlying profitability. On top of that, activist investor Jana Partners is stepping up pressure to spin off the Ventures division and buy back $2 billion worth of shares.
In Brief:
Belgium's Sofina (Brussels: SOF) is seeing the value of its stake in Vinted rise sharply now that the platform has been valued at €8 billion following a secondary share sale of $880 million. This transaction by investors such as EQT and Schroders Capital follows Vinted's impressive 2025 results, in which the company reported revenue of €1.1 billion and profit of €62 million. For Sofina, which has been on board since 2019, this milestone confirms the platform's successful growth from a Baltic startup into a profitable European tech giant.
Martijn van der Vorm, the driving force behind family holding company HAL Trust (Amsterdam: HAL), has passed away at the age of 67. Under his decades-long leadership, HAL grew from a former shipping line into a global investment empire worth €15.5 billion. Van der Vorm was associated with HAL for more than 40 years, 21 of which he served as chairman of the Board of Management. He transformed the capital from the sale of the Holland America Line (1989) into a diverse portfolio with stakes in companies such as Boskalis, Coolblue and Vopak. Partly thanks to this success, the Van der Vorm family is regarded as one of the wealthiest in the Netherlands, with an estimated fortune of €9.4 billion.
Scottish Mortgage Investment Trust (London: SMT) has set out its course for the coming years in a strategic update for the first quarter of 2026. According to the trust, we find ourselves in a new era of artificial intelligence, in which the greatest opportunities are no longer confined to chipmakers alone but are shifting towards innovative software companies and private enterprises.
Constellation Software (Toronto: CSU) continues to expand its global footprint with two strategic acquisitions carried out by its operating groups. Subsidiary Vela has acquired Australia's Eurofield Information Systems (EIS), a specialist in medical information systems for hospitals and insurers. At the same time, the Perseus group has acquired Britain's Starkwood Media Group, which focuses on specialised websites and inventory management systems for the vehicle sector. In addition to these acquisitions, the group is taking a major step in optimising its internal infrastructure with the launch of CSIPay. This new, purpose-built payment platform is now available to all CSI companies and offers full control over the entire process, from onboarding to payout.
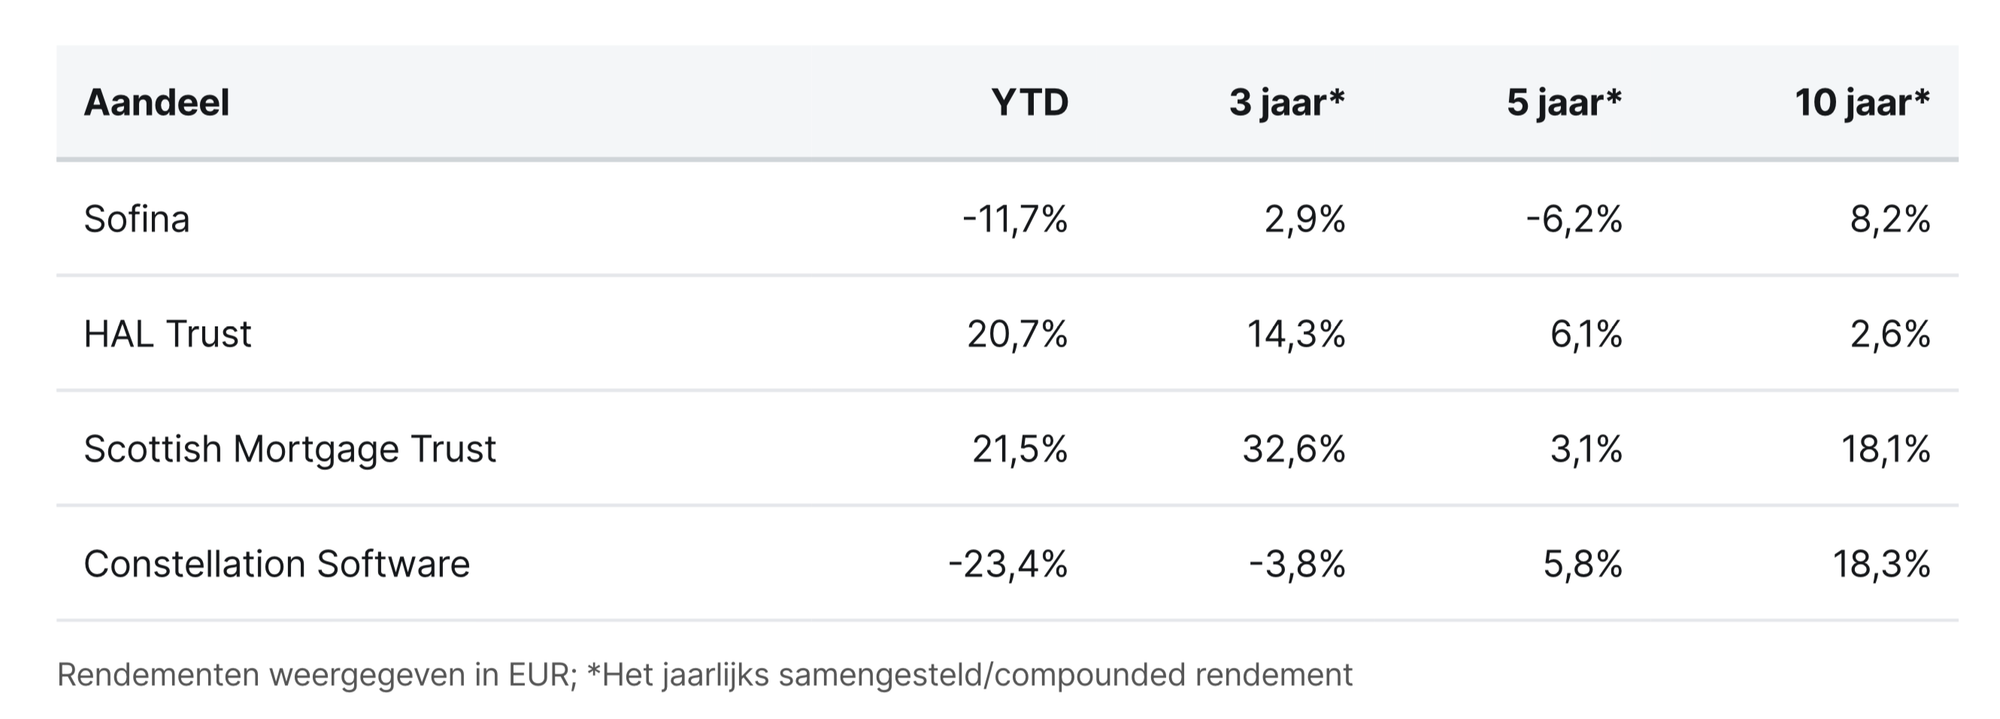
Sofina, HAL Trust, Scottish Mortgage Trust and Constellation Software are traded on the Brussels, Amsterdam, London and Toronto exchanges at prices of EUR 218.00, EUR 170.60, GBP 14.25 and CAD 2,500.00 per share, respectively.
Google Cloud climbs to new heights (again)
It's the way of things: you go for weeks without writing about Alphabet (New York: GOOGL), and then suddenly three weeks in a row. This time it's not new partnerships, but an article about the company's recently published first-quarter 2026 figures. The results came out on Wednesday after the market close, just like Microsoft (New York: MSFT) and Amazon (New York: AMZN), which also reported that day, together accounting for roughly 55% of the global cloud market. An important day that could either strengthen or weaken the AI bull case.
Search is alive and well
Let's start with Alphabet's cash flows. The chart below illustrates beautifully how the company performed this quarter:
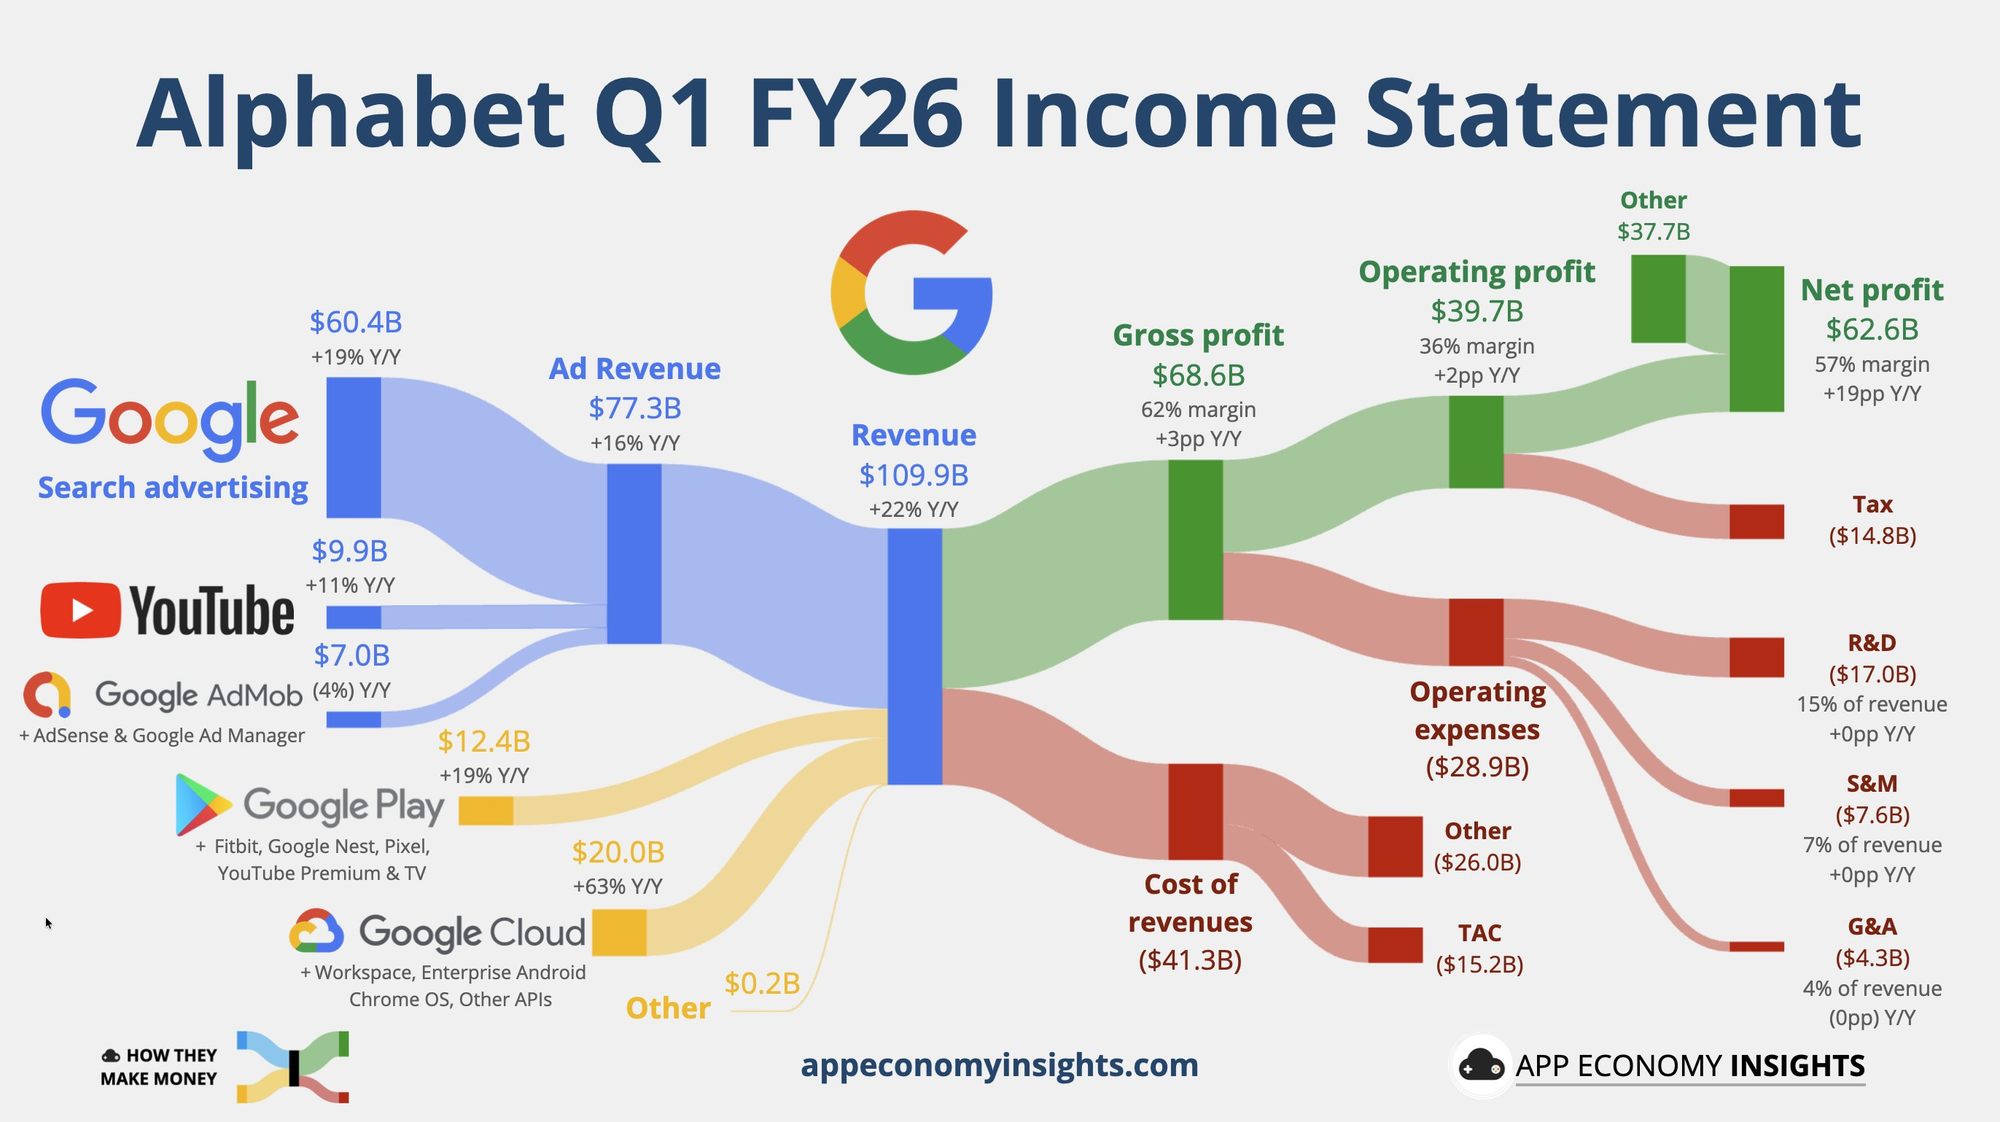
The search engine, which exactly a year ago was still being predicted to be disrupted by Large Language Models (LLMs), has in fact shown enormous acceleration ever since. Revenue from "Google Search & other" rose 19% year-on-year to a whopping $60.4 billion. That means Search is currently generating approximately $663 million in revenue per day (based on the quarterly total).
According to management, this growth is partly due to the successful rollout of AI Overviews and the new "AI Mode". Sundar Pichai emphasised during the conference call that people are returning to Search more often thanks to these AI experiences, and noted that the cost of these AI answers has now fallen by more than 30% thanks to breakthroughs in hardware and engineering.
Google Cloud
The segment everyone was watching closely was Google Cloud. And although analysts had whispered beforehand that there was as much as a 94% chance the figures would beat expectations, Alphabet still managed to surprise the market. Cloud revenue rose by no less than 63% in the first quarter of 2026, to $20.0 billion. Although Microsoft and Amazon also posted strong figures, Alphabet is now recording the highest growth rate of the three major hyperscalers for the second consecutive quarter.
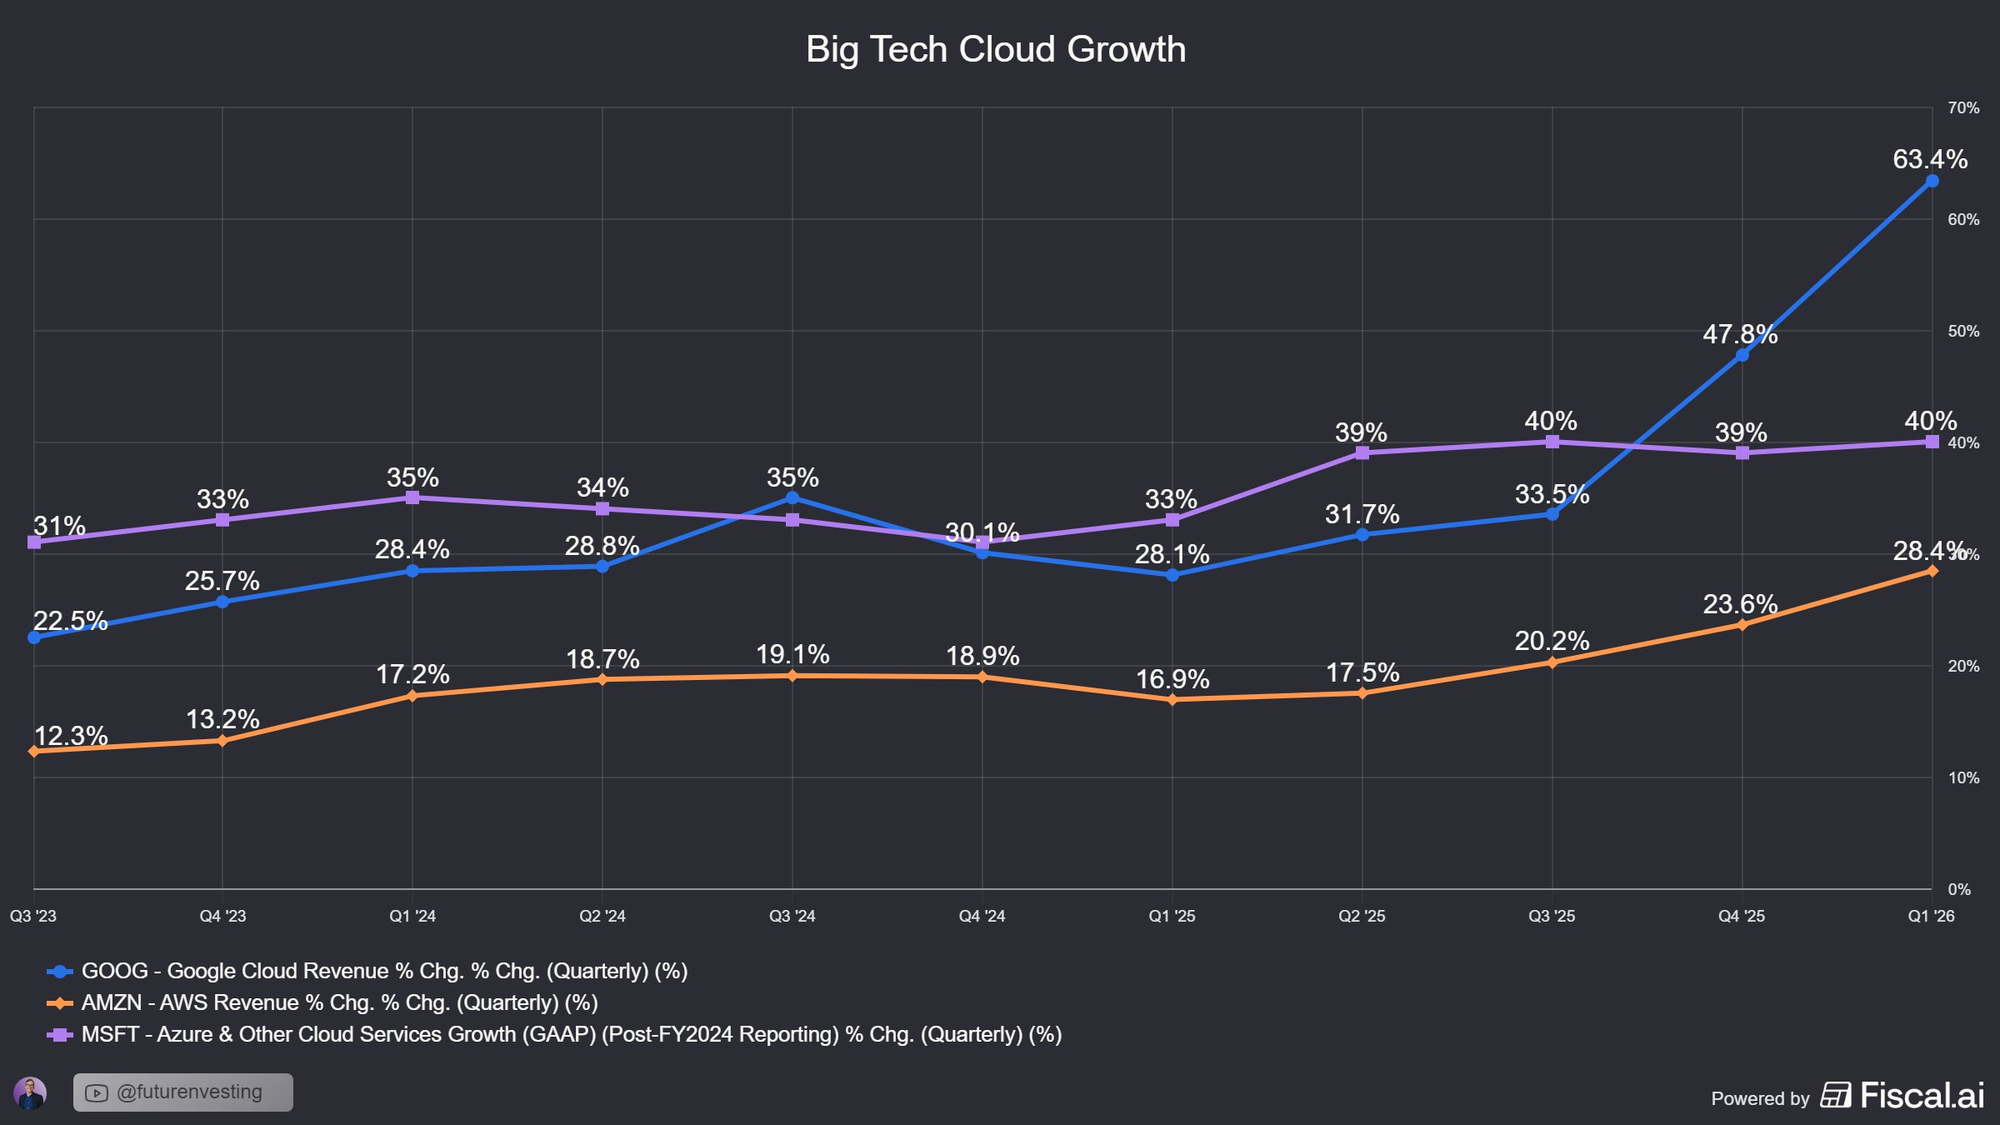
To some extent, that makes sense. Alphabet's cloud division is still the smallest of the three in terms of quarterly revenue: Google Cloud generated $20 billion in revenue last quarter, compared with $38 billion for Amazon (AWS) and $55 billion for Microsoft. Alphabet simply still has the most ground to gain. But the question is no longer whether it will close the gap with its competitors, but how quickly. And if we look at the backlog, the answer is: frighteningly quickly.
The combined cloud backlog of the "Big 3" hyperscalers is currently approaching the astronomical threshold of $1.5 trillion. These are contractually committed future revenues, and the shifts within them can only be described as historic:
| Hyperscaler | Cloud Backlog | Growth (YoY) |
|---|---|---|
| Azure (Microsoft) | $633 billion | +97% |
| Google Cloud (Alphabet) | $466 billion | +398% |
| AWS (Amazon) | $364 billion | +93% |
| Combined total: ~$1.46 trillion | ||
This is a huge milestone for Alphabet. Although AWS currently generates almost twice as much revenue as Google Cloud in absolute terms, Google Cloud has now officially overtaken Amazon when it comes to future orders (backlog). A rise of no less than 398% year-on-year shows that customers are choosing Google Cloud en masse for their long-term contracts. It is proof that companies see enormous value in, and place huge trust in, Google's AI infrastructure. CFO Anat Ashkenazi clarified that this gigantic increase does not stem solely from standard Google Cloud Platform (GCP) contracts.
For the first time, management provided detail on the sale of their in-house produced TPUs (Tensor Processing Units). Alphabet is now signing major hardware deals for these proprietary AI chips.
"Although the majority of the backlog still consists of GCP contracts. If you look at the total backlog, slightly more than half of it will be converted into revenue over the next 24 months. As for the TPU hardware sales, we expect a small percentage of that to come through as revenue later this year, with the bulk in 2027."
This shift creates an entirely new revenue stream that is separate from the traditional cloud subscriptions. The scale of this is considerable, with an expected delivery of 4.3 million units in 2026 and a growth path towards more than 35 million in 2028, the company is tapping into a gigantic market. According to Morgan Stanley, the maths underscores the potential; every 500,000 units sold would already be worth around $13 billion in additional revenue.
"Our cloud revenue would have been higher if we had more compute." - Sundar Pichai
Revaluations of SpaceX and Anthropic clearly visible
If we zoom out again to look at the total cash flows, one item immediately stands out in the top right corner of the chart. The "Other Income" line reported a profit of no less than $37.7 billion. This is the direct result of the revaluations of the stakes in SpaceX and Anthropic that we have written about before, and the room for further upside is far from exhausted. Take Anthropic, for example. Although the last official funding round was still conducted at a valuation of around $380 billion, and that figure probably still serves as the basis for a large part of the current book value, concrete rumours leaked last week that the company is now being valued at somewhere between $900 billion and $1,000 billion.
Google just reported $62.6 BILLION in quarterly profit…
— shirish (@shiri_shh) April 30, 2026
but HALF came from a $37.7B 'paper gain' on private investments in companies like SpaceX and Anthropic.
The reason their VC funding team is top-tier https://t.co/dc6sXFqTpo pic.twitter.com/DT9pmYpGYp
This means that after these enormous paper gains of $37.7 billion, there is a good chance that the actual market value of these stakes is even higher than what is currently reflected on the books.
Conclusion
Despite the euphoria over the growth figures, the fundamental question continues to hang over the market: to what extent do these astronomical investments actually translate one-to-one into additional growth? The initial signals from the hyperscalers are positive, but for now it remains impossible to pinpoint exactly which part of the revenue acceleration can be directly attributed to the new AI infrastructure, and which part is simply riding on a favourable climate.
Meta was immediately punished with a share price drop of 10% when it raised CAPEX by a further $10 billion, and Alphabet also announced that it too will carry out a significant increase in spending in 2027.
Although cash flows allow for it, the current AI race is not being financed solely from own reserves. At Alphabet, we see that the drive to invest is currently outweighing direct cost control. A significant part of the investments is being covered by debt, which is clearly visible on the balance sheet. Long-term debt has risen explosively from $46.5 billion to $77.5 billion, an increase of no less than 66.5%.
Although Alphabet may currently be the best-performing AI player, the pressure to convert this debt and spending into structural profitability is greater than ever.
Alphabet is currently trading on the New York stock exchange at a price of USD 384.96 per Class A share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Markel's quarter was no walk in the park
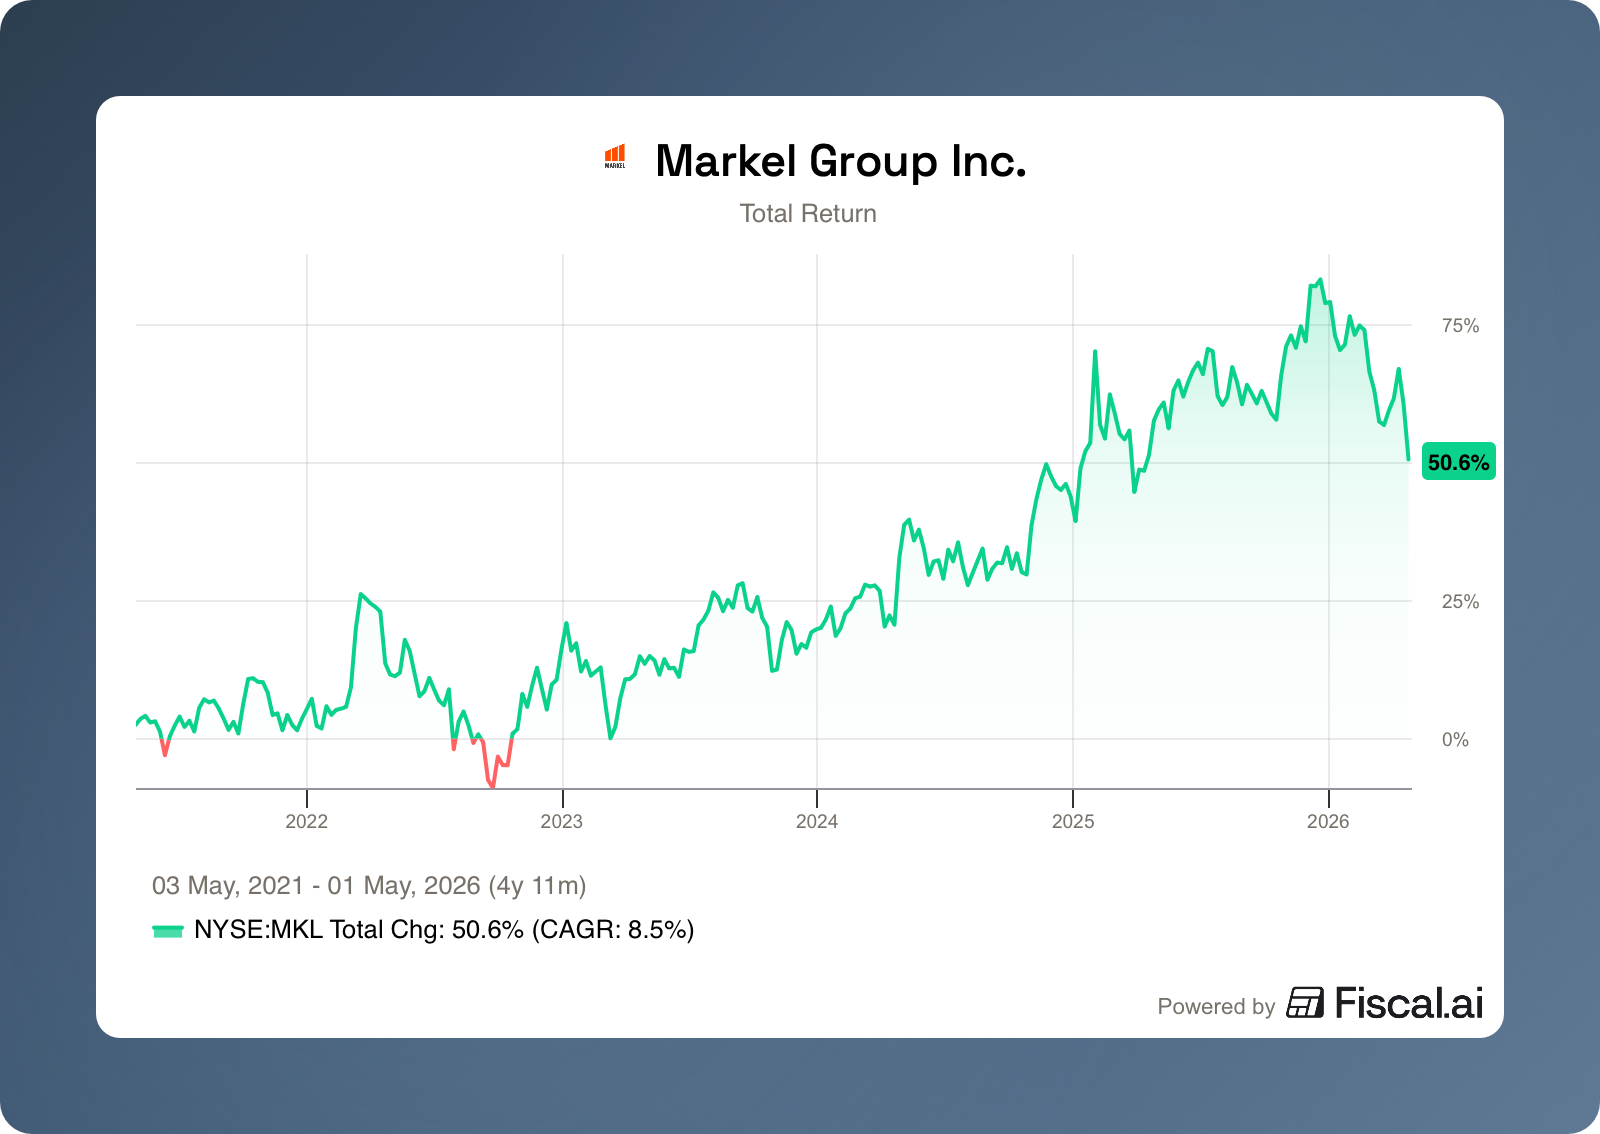
Markel Group (NYSE: MKL) reported its first-quarter 2026 results this week. The share lost more than 7% in the days that followed. At first glance, that looks like a harsh reaction to a quarter in which the combined ratio actually improved. But if you look beyond that single figure, you see what is worrying the market: premium income is falling sharply, rates in key market segments are under pressure, and growth has to come mainly from the international division, a division for which management itself indicated that the current growth rate is not sustainable.
On top of that, news broke this week that activist investor Jana Partners has reignited its campaign against Markel, calling for Markel Ventures to be spun off and for $2 billion worth of the company's own shares to be repurchased.
Insurance
The 21% drop in premium income sounds alarming, but has a simple explanation. Last year, Markel made two major decisions that are now showing up in the figures. First, the company fully wound down its reinsurance division, a division that covered risks for other insurers and had been loss-making for years. Second, its partnership with Hagerty (an insurer for classic cars) was restructured: whereas Markel used to bear the risk itself, it now only makes its licence available in exchange for a fee and passes the risk on. Together, these two decisions take a $774 million bite out of this quarter's premium income.
Adjusted for that, premium income grows by 10%. That is still more moderate than in previous quarters, and that has everything to do with the state of the insurance market.
An insurance cycle works as follows: when there have been few major losses, new capital flows into the market, insurers compete more fiercely for policies, and rates fall. That is exactly what is happening now, particularly in property insurance. CFO Brian Costanzo noted that the concrete figures in property show that rates are currently declining by around 8%-9%. In liability insurance (where the policy covers damage suffered by a customer or third party), rate increases are still present, but are getting smaller, while claims costs keep rising just as fast.
Insurance CEO Simon Wilson was candid about this on the earnings call. He sees new, smaller insurers entering the market with private capital and competing aggressively on price in segments that have caused major losses in the past.
"I will say this, and I can't tell you how much I mean it, we will not follow a casualty market down, and we will not lose discipline in that area."
In practice, this means that Markel lets clients and policies go if the price it receives is not right. That weighs on premium income, but protects profitability. For example, in the US liability market Markel has cut the average insured amounts per policy by more than 20%, and has reduced its exposure to the construction sector from almost half to below 20% of that portfolio.
| Division | Premium Q1 2026 | Change | Combined Ratio |
|---|---|---|---|
| International | $861 mln | +28% | 90% |
| Wholesale & Specialty | $673 mln | -9% | 93% |
| Programs & Solutions | $656 mln | -19%* | 91% |
| * Programs & Solutions grows 12% adjusted for the Hagerty transition. | |||
Markel reported a combined ratio of 93% for this quarter. That is a full three-percentage-point improvement on the 96% of a year ago. And that was despite headwinds:
- The conflict in the Middle East caused $35 million in claims, accounting for 2 percentage points on the combined ratio.
- The run-off reinsurance division, which the company is deliberately exiting, pushed the combined ratio down by another 2 points, with a ratio of 114% of its own.
Add those two one-off effects back in, and you arrive at an underlying combined ratio of around 89%. That is a strong result, and it shows that the strategic shift Markel has carried out over the past year is starting to work. Wilson summed it up with an old industry phrase: "top line is vanity, bottom line is sanity." Loosely translated: high premium income looks good for show, but the true health of an insurer is seen in its profit margin.
The international division was the standout of the quarter, with an impressive combined ratio of 90% and a 28% rise in premium income. These strong figures were driven by expansion into new markets such as Italy, the acquisition of a specialist insurance agent, and the introduction of new contract forms in the London market.
Wilson immediately tempered expectations, however, by pointing to the one-off effect of projects launched in mid-2025 that are only now becoming fully visible in the books. For the rest of 2026, he expects growth to normalise to 13 to 15%.
The investment portfolio
Markel invests a large part of its assets in listed equities, a strategy comparable to that of Berkshire Hathaway. The two largest positions in the portfolio are Berkshire Hathaway itself and Brookfield, with the latter in particular, down around 17%, weighing heavily on the portfolio. In the first quarter, the portfolio as a whole therefore fell by 5.2%, slightly more than the broad equity market, which lost 4.4%. That resulted in a $728 million book loss, which explains the reported operating loss of $273 million.
It is important to understand that these are unrealised losses. Markel has not made any significant changes. The positions are still in place, and now that the equity market has recovered strongly again in the second quarter, the portfolio already looks a lot better. Tom Gayner, who as CEO also oversees the investments, reacted calmly to questions on this and noted that this is normal market volatility, something Markel has decades of experience with.
Activism as an additional source of pressure
At the same time as the presentation of the quarterly results, activist investor Jana Partners this week sent an urgent letter to Markel Group's board. In it, Jana repeats its earlier call to fully divest Markel Ventures, the division that invests in private companies across various sectors such as construction and healthcare. According to the investor, the current combination of insurance operations and private investments creates no unique value, and as a result the share structurally underperforms that of its competitors.
In addition to demanding a split-up, Jana is pressing the insurer to repurchase $2 billion worth of its own shares. This would need to take place through a large-scale buyback programme running in parallel with the requested divestment of the ventures division. Although Jana acknowledges that the results of the insurance division have improved considerably under the new leadership, it argues that the persistently weak share price can no longer be attributed to that division. The share fell by more than 4% over the past year, and Jana contends that the market has simply rejected the current hybrid business model.
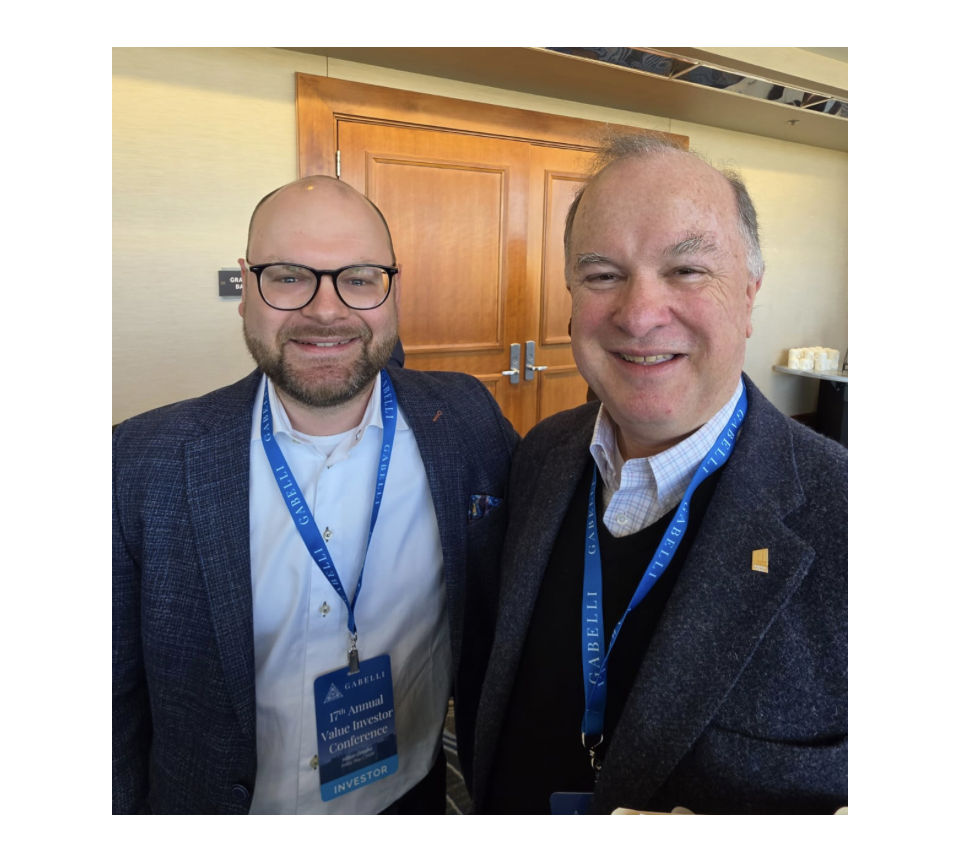
At the annual Gabelli Value Investor Conference in Omaha, Tom Gayner responded directly to the pressure from activist shareholder Jana Partners. In response to a question from Michael Gielkens (Tresor Capital), Gayner indicated that, at a favourable price, he would certainly be willing to carry out a $2 billion share buyback, but he drew a clear line when it came to splitting up the company. Although he acknowledged that the insurance division had underperformed in the past, he stressed that decisive action has since been taken. Under new management, the quality of the insurance portfolio has improved considerably, laying the foundation for recovery.
The fundamental difference with Jana Partners lies in their view of Markel Ventures. Where Jana regards this division as a distraction, Gayner sees it as a crucial form of diversification that generates an additional cash flow to cushion weaker periods in the other business pillars. According to Gayner, Jana simply has a different investment horizon and views the situation from a perspective that is less in line with Markel's culture. He emphasised that entrepreneurs and families sell their businesses to Markel precisely because of the intended long-term partnership; after all, you do not sell a family business to just any bidder. Markel therefore deliberately chooses to act as an active partner, continually strengthening the underlying businesses rather than divesting them.
Markel Group is currently trading on the New York Stock Exchange at a price of USD 1,792.76 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted after written permission and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade in investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your investment. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



