
Family Holdings #4 - Swedish solidity and the Belgian stars



This week's topics:
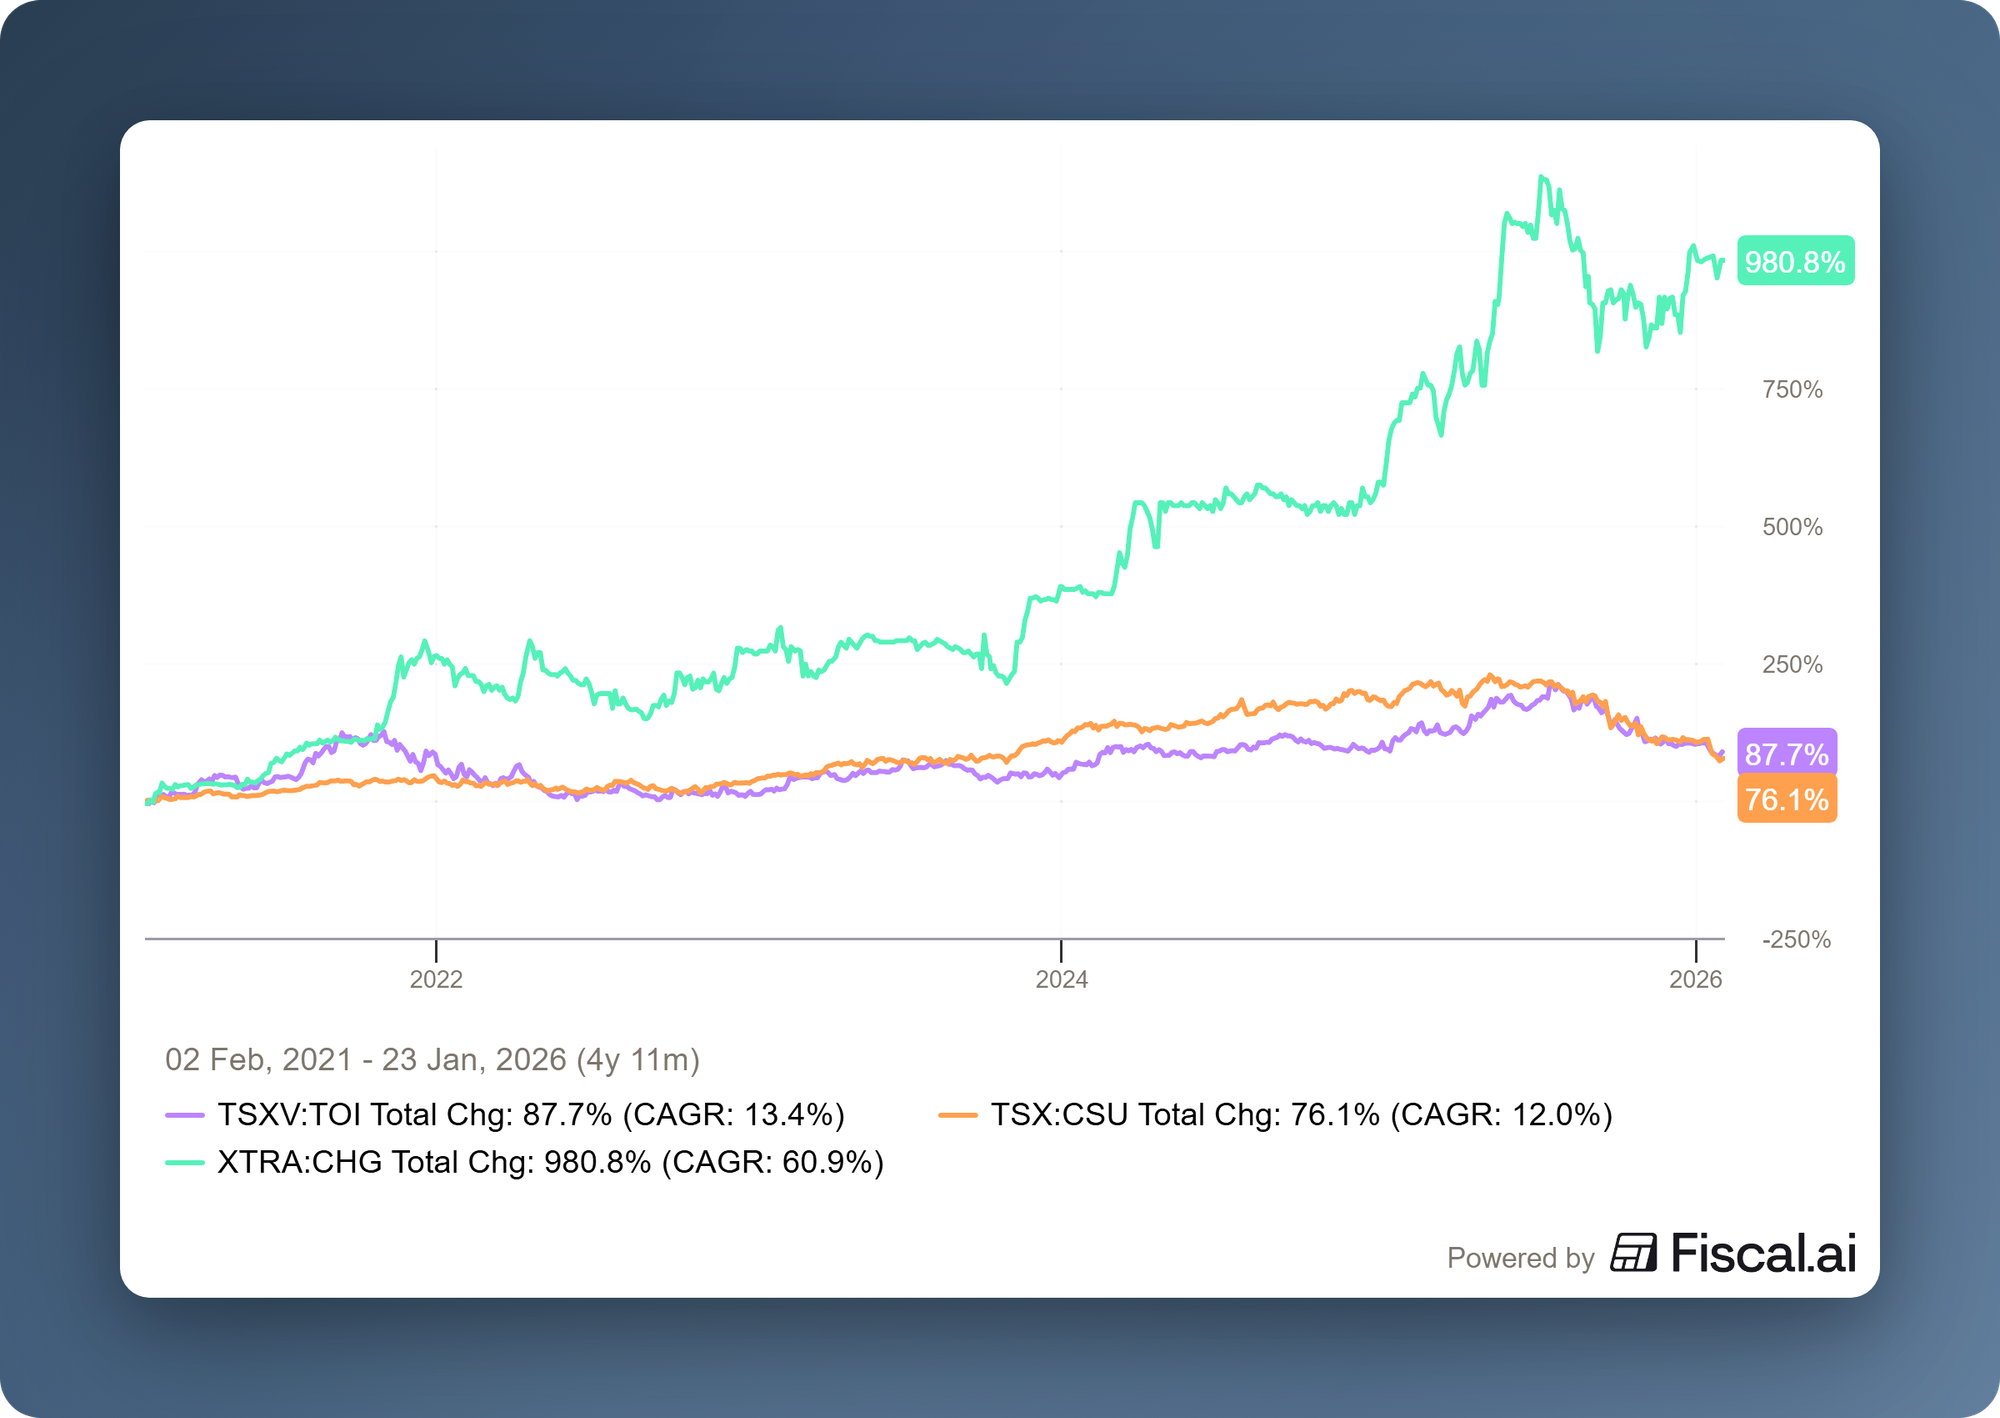
Recent turmoil surrounding AI has fuelled fears that software could in future be built at virtually no cost, and that even specialised niches are no longer protected. That reasoning, however, misses where the real value of Vertical Market Software lies. It is not development costs but mission-critical data, complex regulation, deep integration into workflows and high switching risks that form the moat. For established players such as Chapters Group, Constellation Software and Topicus, AI therefore poses no existential threat, but rather represents a productivity lever that can raise margins and, through lower market valuations, even creates new acquisition opportunities.
Following recent price target increases and news reports, a scenario outlined earlier appears to be becoming reality. Belron, the crown jewel of D'Ieteren, is exploring a possible stock market listing in the second half of 2026. With strong margins, robust cash flows and an experienced CEO at the helm, an IPO would not only unlock value at Belron itself but could also fundamentally call into question the holding company discount at D'Ieteren.
Sofina gave a first glimpse into its 2025 annual figures this week. Reported NAV per share rose slightly to €299, but adjusted for the October capital increase it would have been around €305, roughly 2% lower than at the end of 2024, mainly due to currency effects. Management noted that the portfolio remained stable, with ByteDance as the largest position and Vinted on the rise, while new investments in Oviva and Cerealis show that the first capital from the share issue is already being put to work.
In Brief:
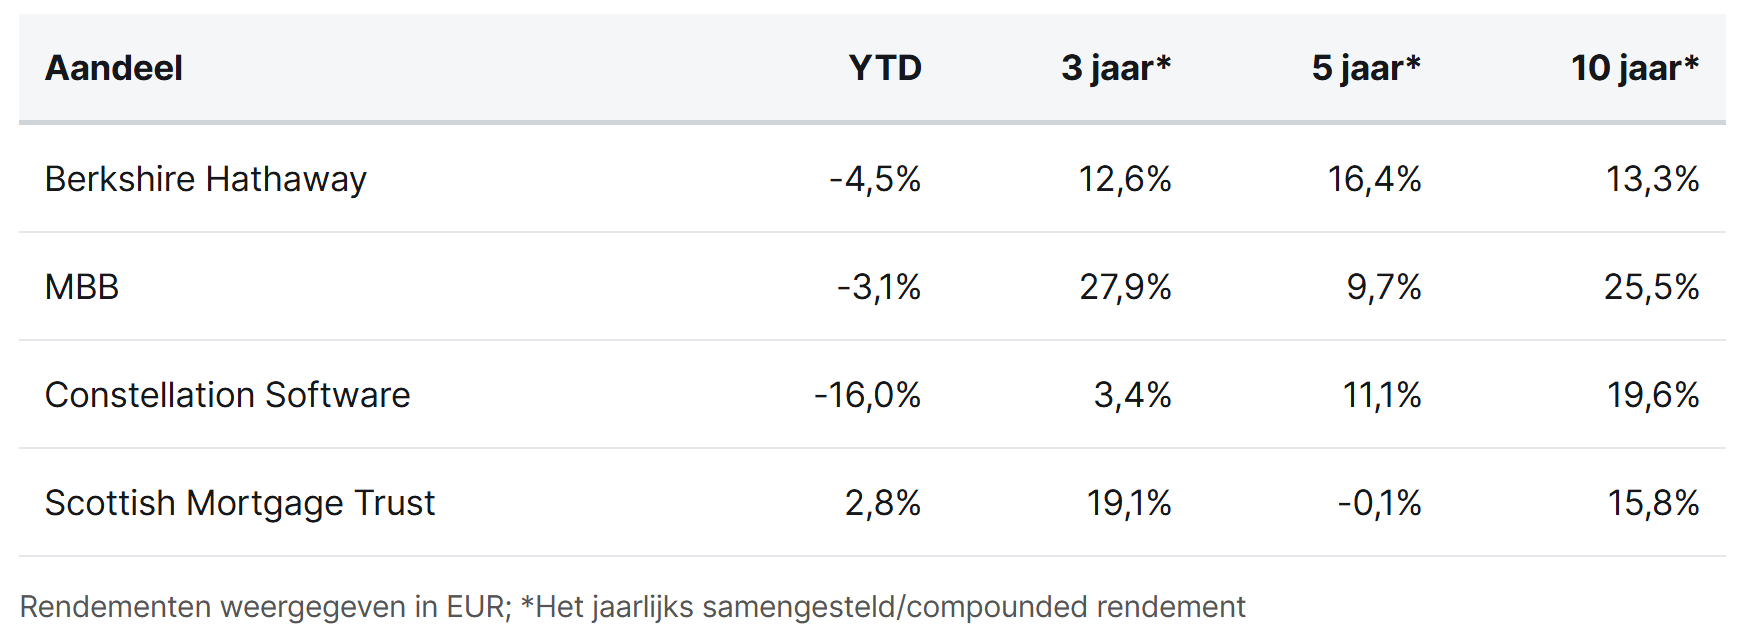
Berkshire Hathaway (New York: BRK.B) is preparing to dispose of its entire 27.5% stake in Kraft Heinz, according to an SEC filing submitted by Kraft Heinz. The document states that Berkshire may sell up to 325 million shares "from time to time". The decision follows public criticism from both Warren Buffett and newly appointed CEO Greg Abel of the planned split-up of Kraft Heinz, for which no shareholder vote was requested. The timing suggests that Abel is pressing ahead with a further clean-up of Berkshire's listed portfolio right from the start of his tenure.
MBB (Frankfurt: MBB) is benefiting from strong figures at subsidiary Aumann, which announced that it will comfortably exceed its profit guidance for 2025. Despite a revenue decline of more than €100 million (due to ongoing pressure on the European automotive sector), Aumann achieved an EBITDA margin of around 14%, some 2.5 percentage points higher than in 2024. The improvement was driven by strong operational performance in Q4, faster-than-expected order fulfilment and lower costs for structural optimisations.
Constellation Software (Toronto: CSU) added two more companies through its divisions. Within Vela, the Juniper Group acquired Singapore-based fintech company Tagit, provider of the open-API banking platform Mobeix, which serves both traditional and challenger banks across Asia, Africa and the Middle East. In addition, Volaris acquired German company ines GmbH, a provider of health information systems for more than 35 clinics and hospitals in Switzerland. The company, based in Konstanz, was founded in 1994 and has around 60 employees.
Scottish Mortgage Trust (London: SMT) counts Zipline among its fast-growing unlisted holdings, accounting for 1.9% of net asset value. Zipline raised $600 million at a valuation of $7.6 billion, underscoring the traction of its autonomous logistics network. With weekly growth of 15% in its US operations, Zipline is strengthening its market leadership through economies of scale and superior technology. This allows it to extend its lead over competitors further and claim a dominant position in last-mile delivery.
Berkshire Hathaway, MBB, Constellation Software and Scottish Mortgage Trust are currently trading on the New York, Frankfurt, Toronto and London stock exchanges at prices of USD 480.28 (B-share), EUR 200, CAD 2,780.81 and GBP 12.10 per share, respectively.
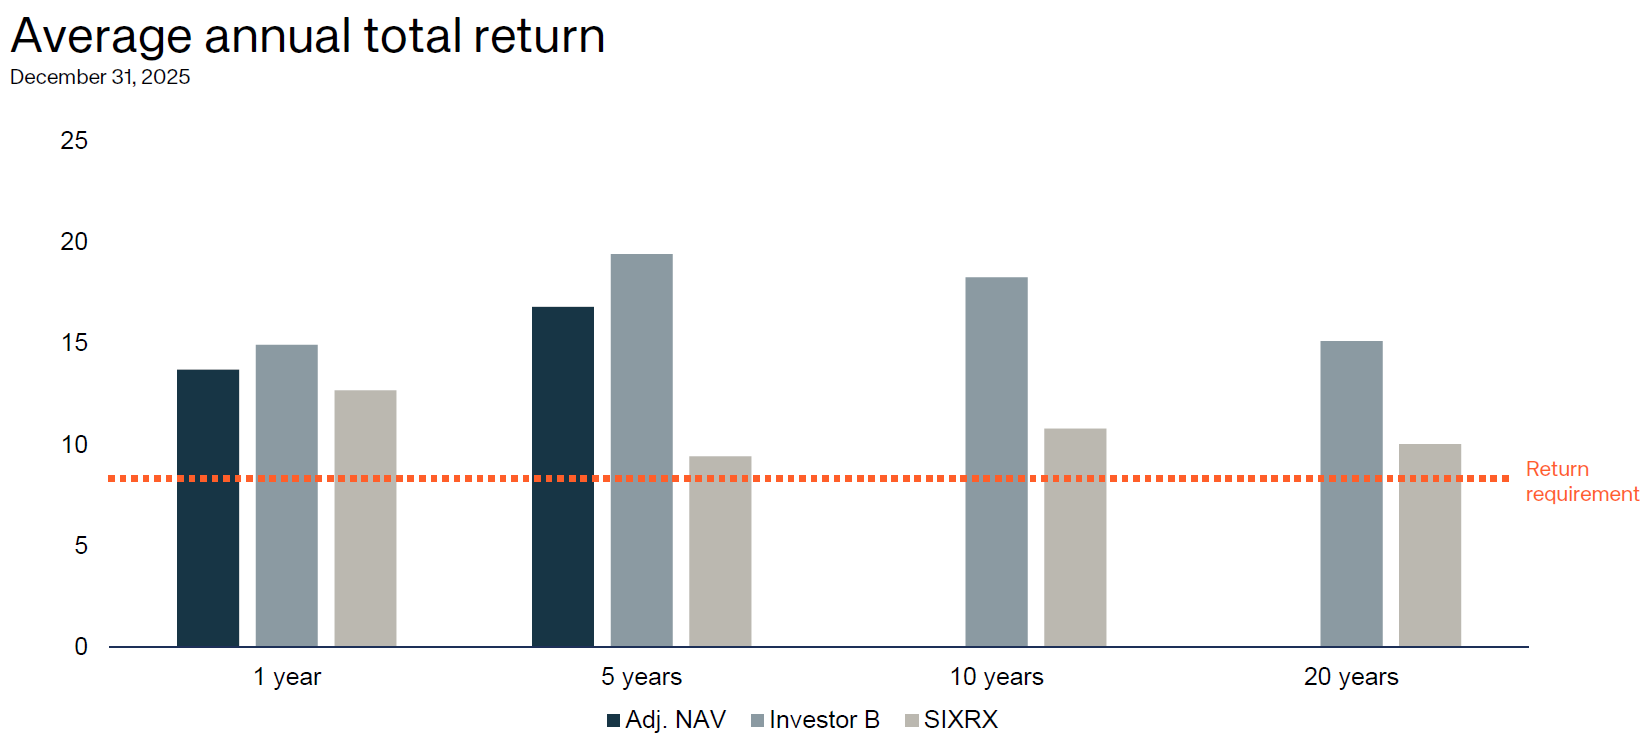
Investor AB demonstrates the value of internal diversification
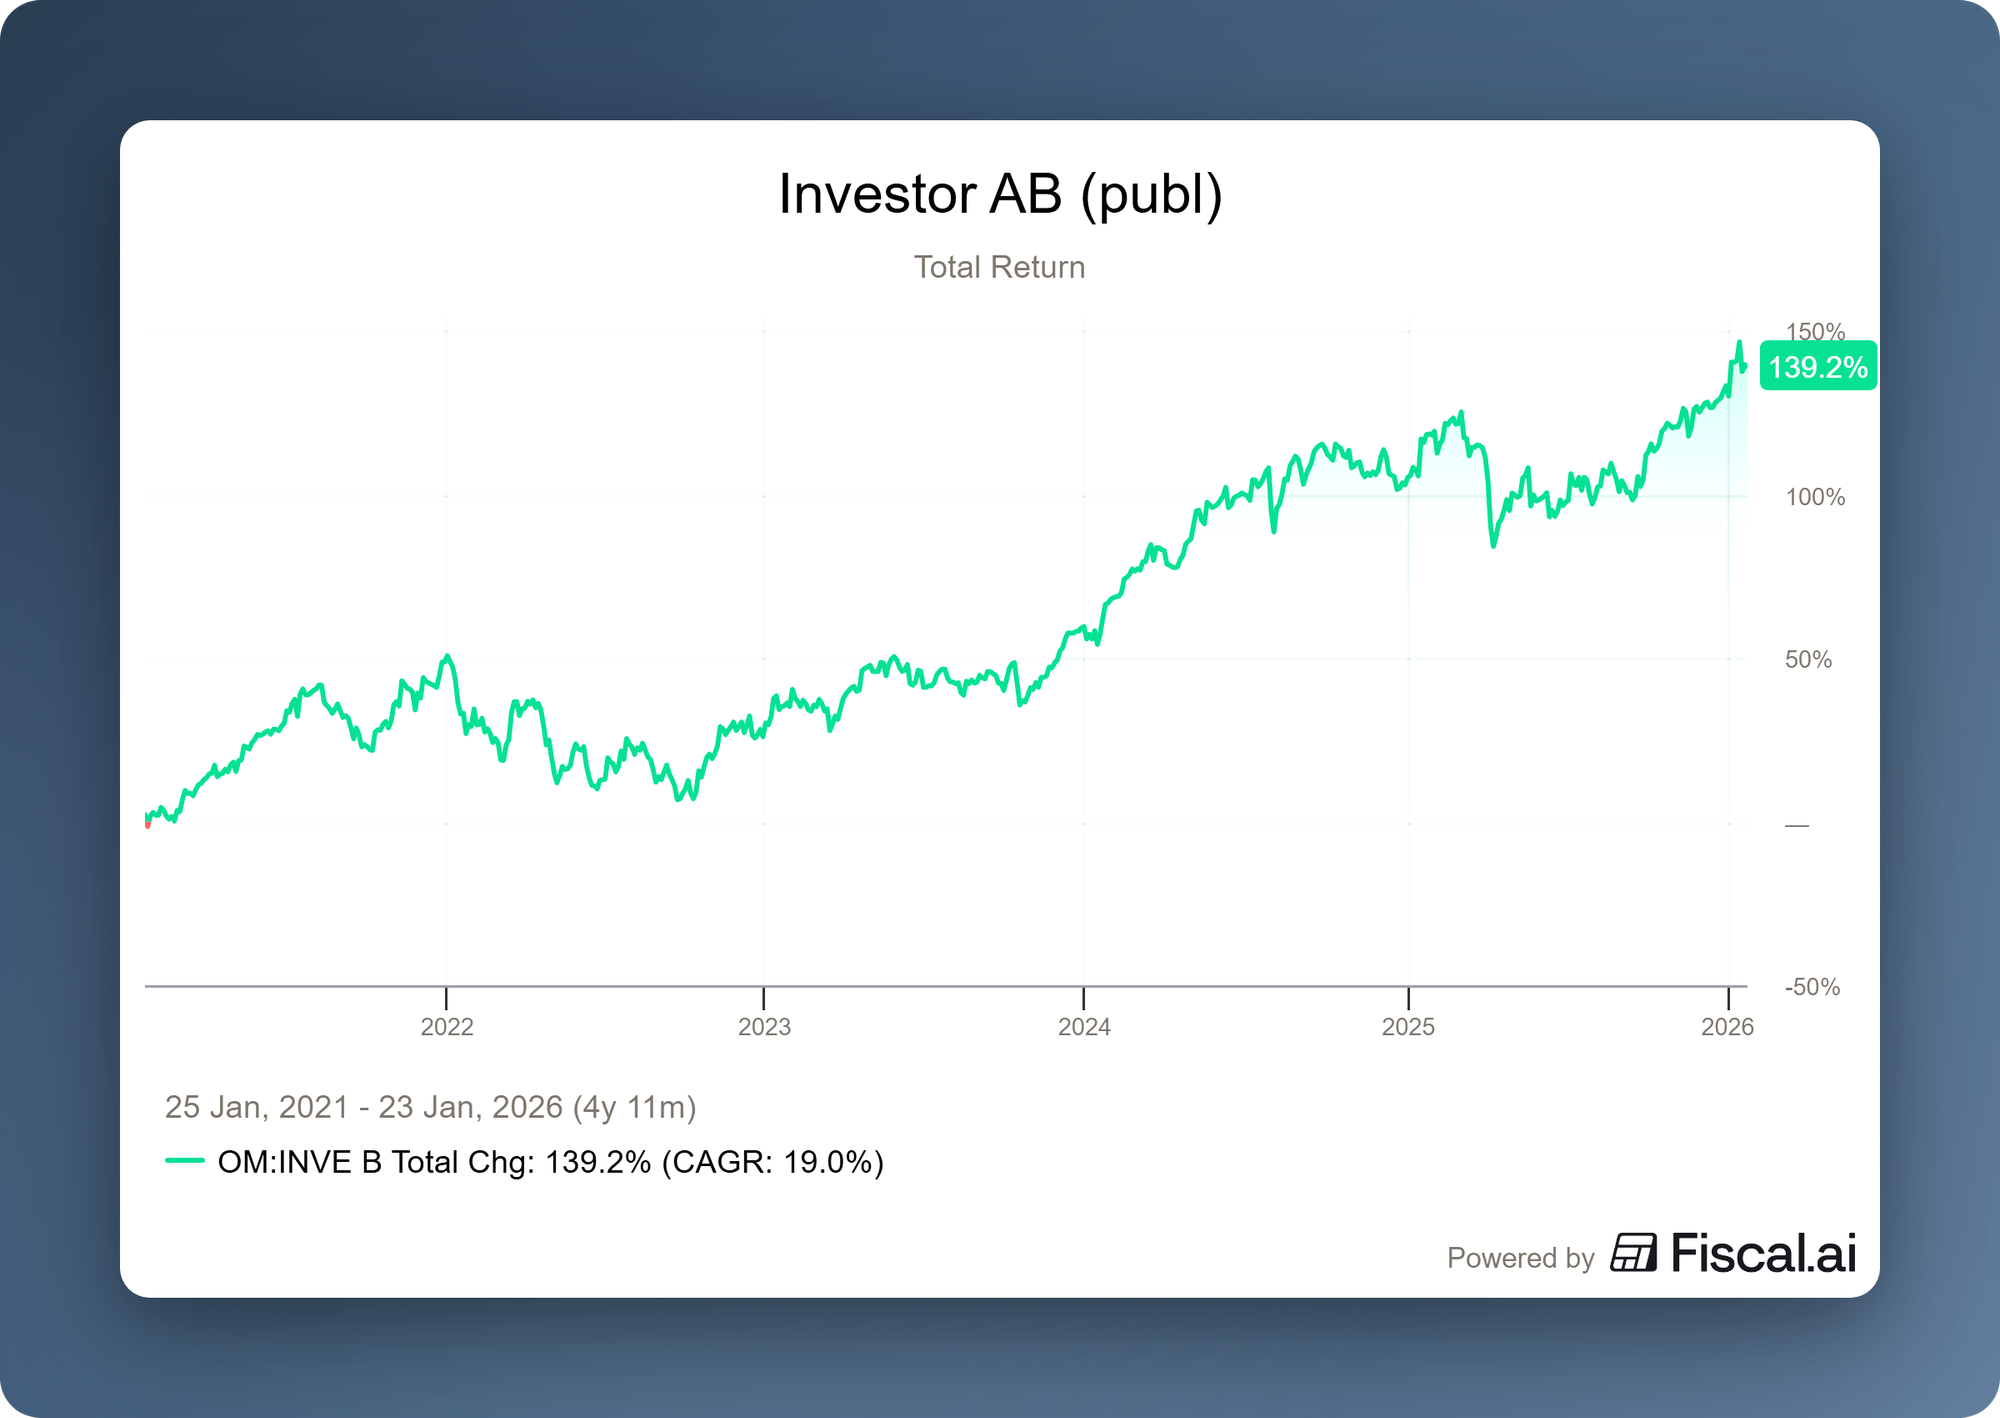
Swedish investment holding company Investor AB (Stockholm: INVE-B) published its Q4 and full-year 2025 results last week. In a year that, according to management, was "anything but straightforward", Investor nonetheless delivered a strong overall performance: NAV rose by 14% and Total Shareholder Return came in at 15%. With this, it once again outperformed the Swedish equity index.
This outperformance fits a pattern we have been tracking for some time. We previously wrote that Investor AB has now outperformed the stock market for fifteen consecutive years, with more than 80% of total returns stemming from actual growth in intrinsic value rather than from financial leverage or multiple expansion. In 2025 too, Investor confirmed this long-term DNA: despite a difficult start to the year, the shortfall was convincingly made up in the fourth quarter. This once again underscores why Investor's model of disciplined ownership, portfolio diversification and a focus on structural value creation has delivered consistent returns for years.
Listed companies
Investor AB's listed portfolio made a solid contribution to intrinsic value growth in the fourth quarter. The figure below shows each company's contribution to NAV development in Q4. Almost all positions contributed positively, with AstraZeneca, Atlas Copco, Sobi, Wärtsilä and SEB the key value drivers. During the conference call, management emphasised that the listed portfolio's total return of 6% for the quarter was largely in line with the Swedish market, but that absolute value creation was driven by a broad base of holdings within the portfolio.
AstraZeneca contributed substantially to NAV development, consistent with the size of the position within the portfolio. After the quarter closed, the company also announced the acquisition of Modella AI, a Boston-based AI specialist in oncology research. With this acquisition, AstraZeneca brings in advanced foundation models and AI capabilities to accelerate, among other things, biomarker discovery and clinical development. The transaction underscores AstraZeneca's strategy of structurally integrating data and AI into its R&D process, with the aim of reducing the complexity and lead time of oncology drug development. AstraZeneca also announced that it will obtain a listing on the US stock exchange after market close on 30 January, which could potentially result in a higher valuation for the shares.
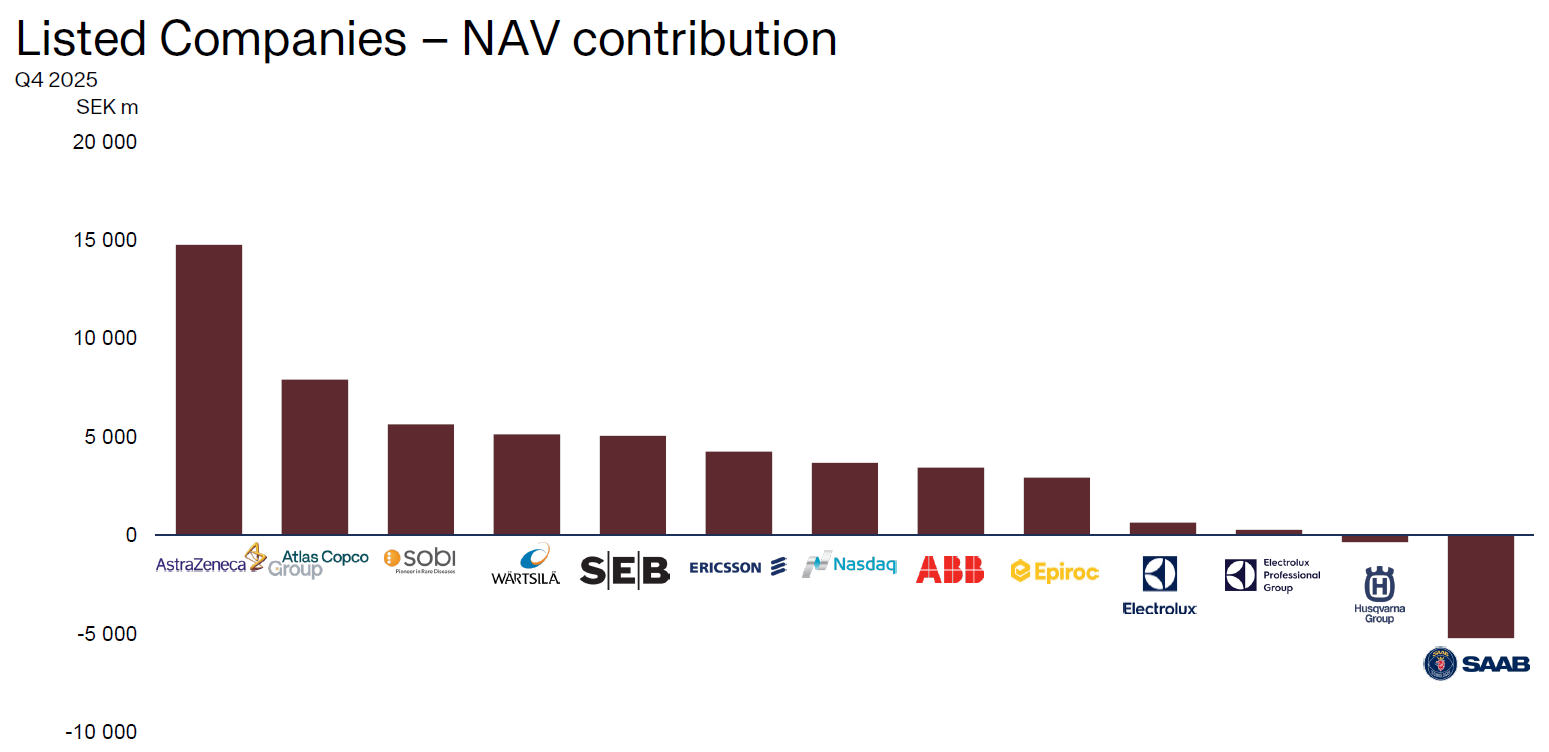
On the negative side of the chart, Saab stands out. Despite a very strong calendar year 2025, in which the share roughly doubled, Saab saw a correction of around 18% in the fourth quarter. This decline coincided with a temporary cooling of sentiment around defence stocks, partly due to speculation about possible peace negotiations between Russia and Ukraine. This proved short-lived. In the first weeks of 2026, the picture has reversed completely, with Saab now trading more than 25% higher again, driven by escalating geopolitical tensions and the continued focus on European defence spending.
Investor continued to act consistently as a long-term owner in the fourth quarter. Its stakes in core positions were further increased, including through additional investments in Atlas Copco and Ericsson. At the same time, a limited number of SEB shares were sold to keep the relative ownership stake stable as SEB continues its share buyback programme. According to management, these transactions do not reflect tactical market timing, but rather the aim of maintaining the desired ownership structure for each company. In SEB's case, avoiding heightened regulatory requirements once the ownership stake exceeds a certain threshold is specifically a factor.
Finally, portfolio company Ericsson released its quarterly results this week. The company has been under pressure for some time due to structurally weak demand for traditional telecom network infrastructure. Although management pointed to potential growth opportunities in AI-related network applications, drones and defence-related solutions, underlying revenue development remained under pressure in the near term. This persistent pressure has forced Ericsson into cost cuts and restructuring for a while now, including a significant reduction in headcount. Nevertheless, Ericsson managed to surprise investors with the announcement of its first-ever share buyback programme, worth €1.4 billion. A move that the market interpreted mainly as a clear signal of strong capital discipline.
Unlisted companies: Patricia Industries
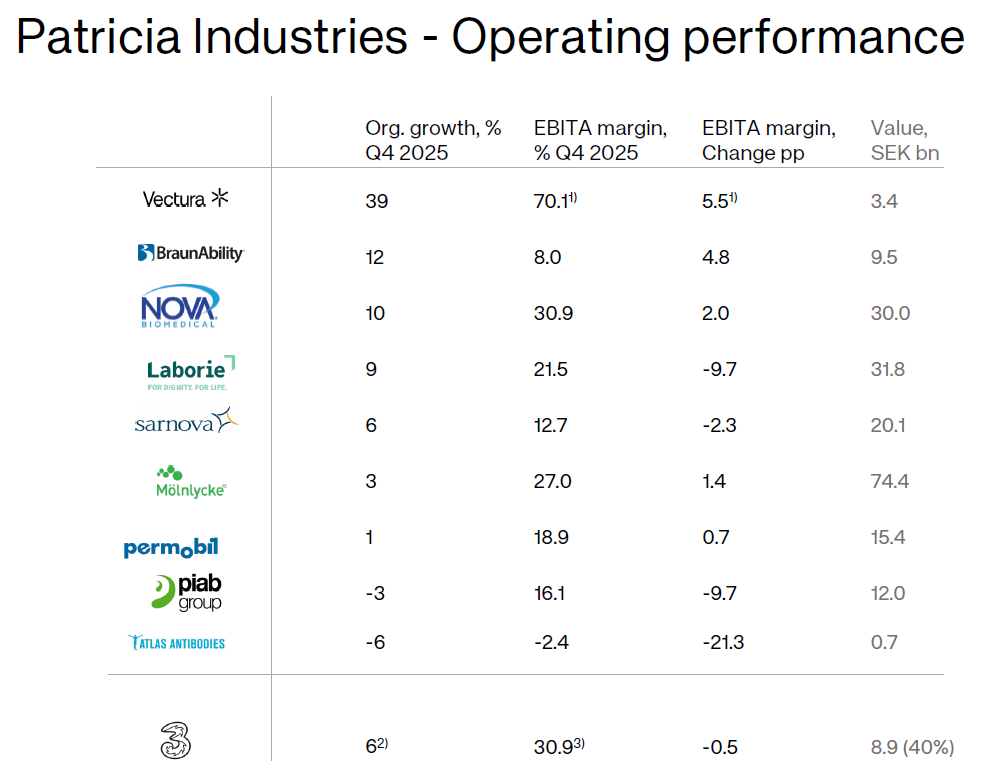
Where the listed portfolio carried the year, Patricia Industries was in fact the headwind in 2025. The private portfolio's total return for 2025 came in at -9%, with management explicitly identifying the weaker US dollar as the main obstacle.
Operationally, the portfolio is more resilient than the -9% annual return suggests, but performance varies widely by company. At the upper end, there are clear growers with high or improving margins (Vectura, BraunAbility, Nova Biomedical), while at the lower end are companies where demand weakness, restructuring and temporary issues are weighing on growth and profitability (Piab, Atlas Antibodies).
What stands out here is that organic growth and margin development do not always move in tandem. For example, Laborie's robust revenue growth was accompanied by a sharp margin decline due to integration and transition costs, while Mölnlycke managed to further improve its margin despite modest revenue growth. This underscores a point management made several times during the call: operational reality varies significantly by end market and by the phase a company is in, while currency effects and restructuring costs added an extra layer of noise in 2025.
Whereas the previous update was still largely dominated by the completion of this company's acquisition, Nova Biomedical's Q4 results show for the first time how the investment case is starting to play out in practice. During the call, management indicated that the integration is proceeding according to plan, with concrete steps such as combining organisations and implementing a single shared ERP system. It had already been noted previously that this could create temporary friction. In that light, it is important that Nova achieved a solid recovery, following the negative organic growth (-4%) immediately after the acquisition, which was attributed to an exceptionally strong comparison base and a cyber incident in Q3. CFO Haquinius emphasised that the recovery in Q4 was partly helped by the normalisation of operations following that incident, but also that underlying demand and profitability remained robust. The EBITDA margin of over 30% underscores that Nova Biomedical is not just a growth story, but also a high-quality profit platform. At the same time, management tempered short-term expectations: further integration steps may still affect revenue and profit, but are seen as necessary to unlock the full scale and synergy potential.
Mölnlycke is by far the largest holding within Patricia Industries and, accordingly, received above-average attention in analysts' questions during the conference call. In Q4, Mölnlycke reported 3% organic growth, driven by the wound care (+5%) and gloves (+3%) divisions, while the EBITDA margin improved further to around 27%, despite persistent negative currency effects and trade tariffs.
At the same time, the call made clear that Mölnlycke is facing structural headwinds in Europe. Both CEO Cederholm and CFO Haquinius explicitly pointed to ongoing pressure on healthcare budgets in Germany and France, which is slowing growth in those regions. Management indicated that this weakness has been visible since the first half of 2025 and that there is little prospect of a swift recovery. On the other hand, the US and China continue to show strong momentum, underscoring the geographically diversified nature of Mölnlycke's operations.
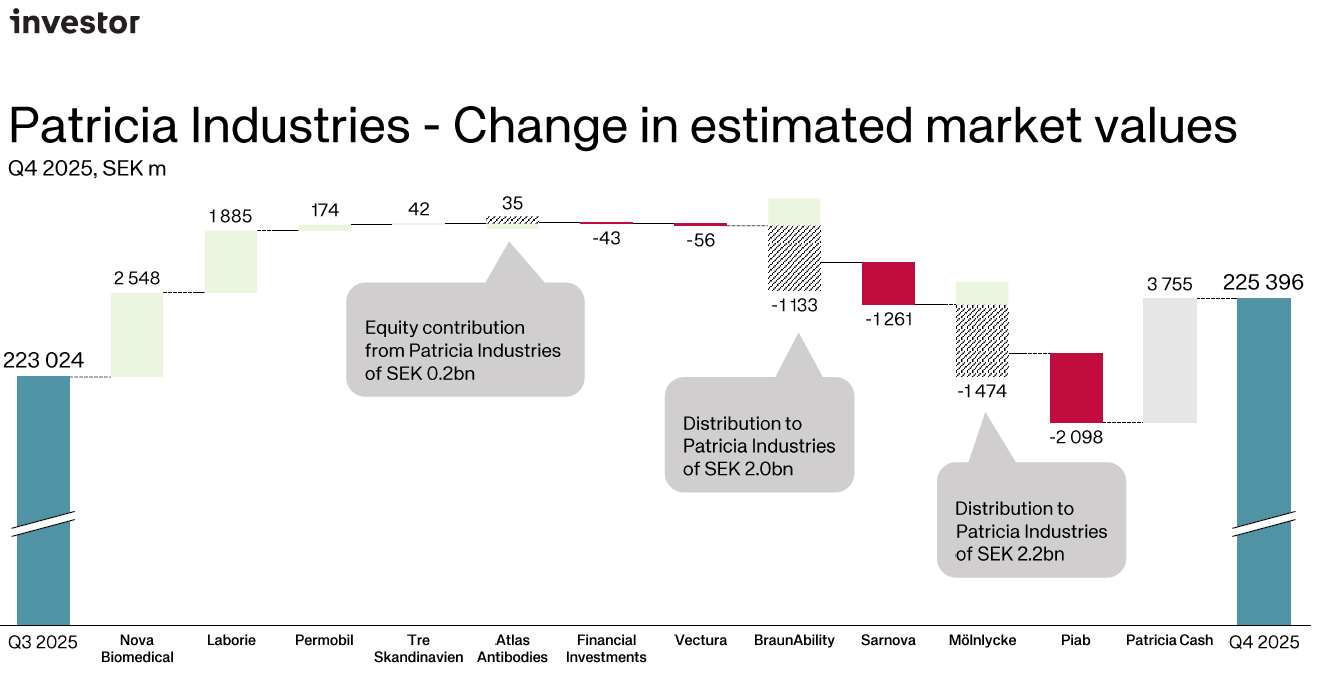
The accompanying value bridge puts these operational results into perspective. Despite the solid underlying development, Mölnlycke made a negative contribution to the estimated market value in Q4, mainly due to currency effects and a dividend distribution of €200 million (around SEK 2 billion) to Patricia Industries. However, this decline is not indicative of the company's fundamental quality. On the contrary: the margin improvement stemmed from active efficiency programmes and a favourable product mix, which according to management offset currency and tariff pressure by several percentage points.
EQT AB and private equity funds
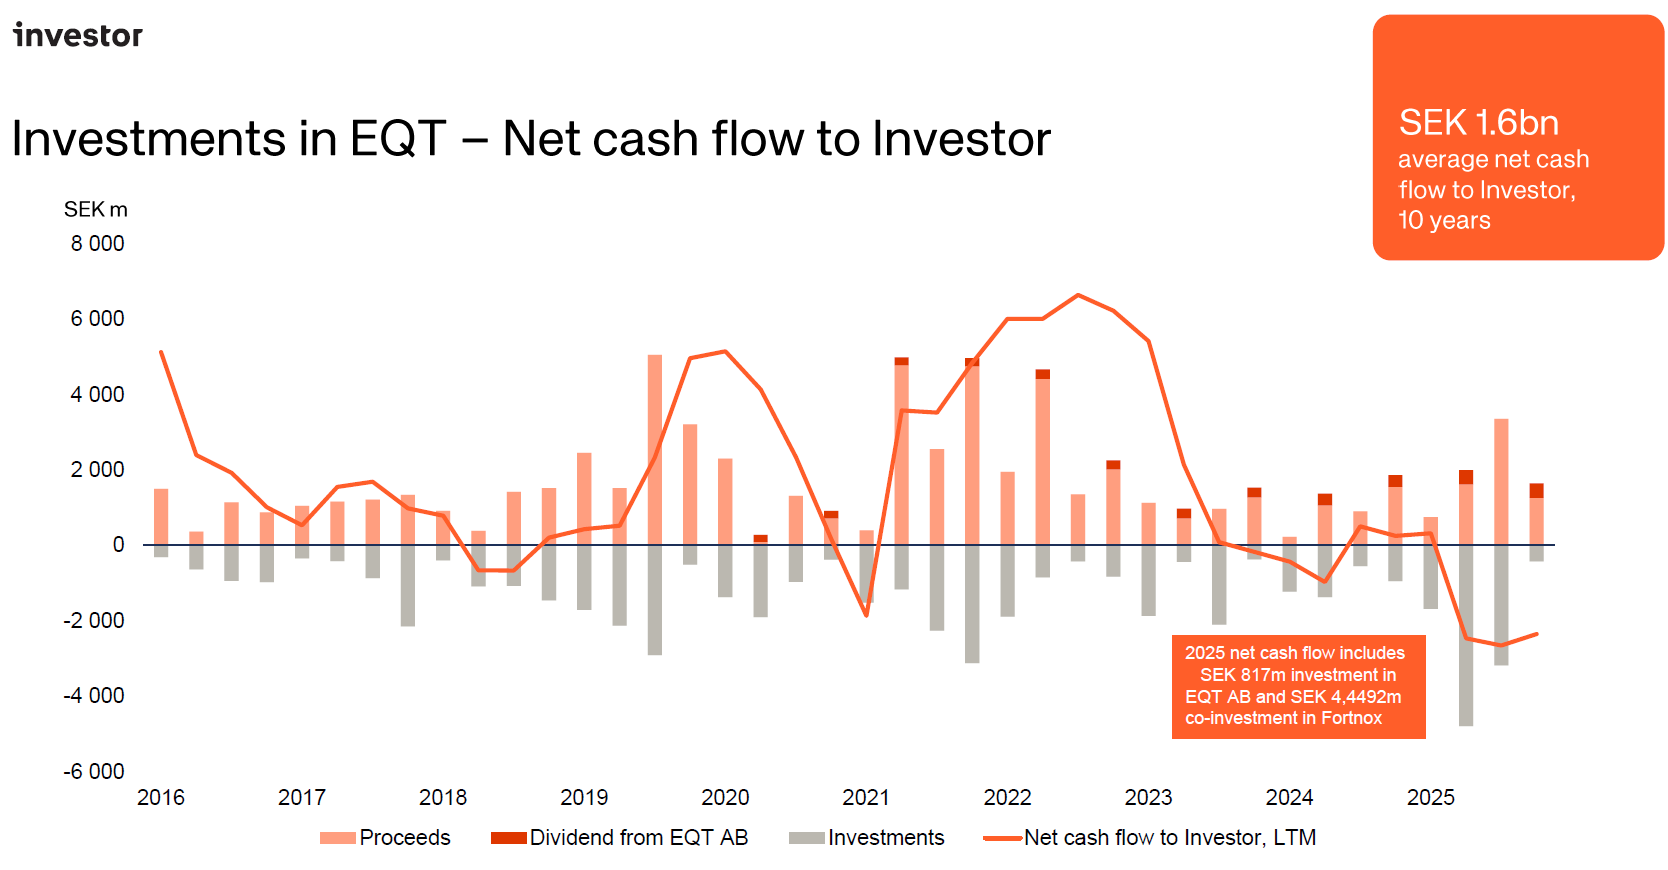
The value of the EQT component grew by 8 percent in the fourth quarter. The share price of EQT AB showed a strong increase of 14%, while the value of the private equity funds remained flat at 0%. As usual, fund results are reported with a one-quarter lag, so this figure relates to performance in the third quarter. Net cash flow from EQT to Investor amounted to SEK 1.2 billion this quarter, of which SEK 0.9 billion came from the funds, driven by healthy exit activity.
This quarter, Investor also completed the final tranche of its investment in software company Fortnox, bringing the total co-investment to SEK 4.5 billion. During the call, CEO Christian Cederholm explained that, alongside the EQT X fund, this transaction is a way to create value in private markets. Zooming out to the long term, the picture remains robust, with an average annual net cash flow of SEK 1.6 billion over the past ten years. Although cash flow over the past twelve months was negative due to the significant investments in EQT shares and Fortnox, it would have been positive without these strategic moves.
Outlook and future-proofing
Looking ahead to 2026, Cederholm expects that challenging market conditions, such as currency headwinds, trade tariffs and geopolitical uncertainty, will persist. However, Investor AB's strategy remains unchanged, focused on future-proofing the portfolio by striking a balance between operational efficiency in the here and now and investing in structural growth trends such as AI and the green transition.
One specific point of focus during the Q&A was the position in China. Management emphasised that a presence in this region is crucial in order to compete with local players that are at the forefront of speed and technology. This dynamic keeps the portfolio companies sharp and is essential for maintaining their global competitive advantage in the long term.
As an engaged owner, Investor anticipates robust cash flows that will be deployed broadly across its three business areas. Priority is given to the further development of existing businesses, but the search for new platform companies continues unabated. With a focus on the strategic pillars of Performance, Portfolio and People, the objective remains clear: growth in net asset value and dividends, thereby laying the foundation for an attractive total return for shareholders.
Investor AB ended the trading week on the Stockholm stock exchange at a price of SEK 338.90 per B share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
VMS and the AI fear: Why mission-critical software remains indispensable
Sentiment around investment holding companies in Vertical Market Software (VMS) such as Chapters Group (Frankfurt: CHG), Constellation Software (Toronto: CSU) and Topicus.com (Toronto: TOI) is currently dominated by fear of disruption. There is concern that AI can build software at virtually no cost, and that no niche is safe anymore. As we emphasised in our recent Deep Dive on Chapters Group, we take a different view here, because development costs were never the moat for this type of software. The moat lies in the fact that it is truly mission critical. A hospital or public transport company will not simply replace a proven system, one that forms the backbone of the organisation, with an AI solution that has no track record. Tresor Capital partner and co-owner Michael Gielkens made the following observation about these barriers on the podcast: "We hear from a great many clients who work in educational institutions or healthcare institutions that it is simply forbidden to work with AI, or with systems developed using AI, because of the data risk."
Code Is Not a Moat
This observation about data risk ties in seamlessly with the reality of this crucial infrastructure. A fundamental nuance in this debate is offered by former Constellation Software employee Paul. He rightly argues that while AI commoditises code, it does not commoditise the 'System of Record'. The moat is not formed by the difficulty of writing code, but by complex data migrations, workflows and integrations. Paul draws a sharp distinction here between 'Systems of Action' and 'Systems of Record'. AI excels at generating content and performing tasks, which indeed poses a threat to generic tools lacking unique data.
The real line of defence for these companies consists of data migration, compliance with complex regulation, and deep integrations with external systems. 'Vibe coding' may make it cheap to build a simple application, but it does not simply move fifteen years' worth of historical business data, nor does it replicate the hundreds of necessary connections with banks and tax authorities.
Call me out in a few years when all my software investments go to zero:
— Paul, not a CFA (@Investmentideen) January 21, 2026
AI (incl. “vibe coding”) commoditizes code, not systems of record. CSU owns mission‑critical systems of record in niche markets. Those moats are data, workflows, integrations & switching costs – not the… https://t.co/pL3AxyUQWa
The companies in our portfolio, however, manage crucial, regulated data. A financial general ledger or medical record cannot simply be 'vibe coded', because these systems require strict data models and audit trails that auditors and regulators understand. Moreover, AI is expected to be margin-enhancing for this type of software vendor. It boosts developer productivity and automates support, while licence and maintenance costs for the customer often amount to only 1 to 2 percent of revenue. The limiting factor for the customer is risk, not price, meaning the willingness to switch to a cheaper AI alternative is minimal.
That self-built software often disappoints in practice was also experienced by X user Hershie Brody. A tool he built quickly turned into a maintenance nightmare when external APIs changed and users kept demanding new features. Entrepreneurs want to be relieved of this burden, not to act as their own software administrator.
 Michael Gielkens
Historical perspective and valuation
The current panic bears parallels with earlier doom scenarios that did not materialise.Adam Khoo draws a comparison with the panic that prevailed around 2015, when investors feared that Amazon's dominance would spell the definitive end for physical stores. The idea was that traditional retail chains would disappear because consumers would only order online. That prediction did not come true: the established order adapted and emerged even stronger from the fight. A similar scenario was seen around 2010 with the rise of 'the cloud'. The market thought that old software giants such as Microsoft and Adobe would collapse because software was no longer installed locally on computers but offered over the internet by new players such as Amazon Web Services (AWS). That fear also proved unfounded: these companies used their enormous scale to embrace the cloud model and strengthen their market position.
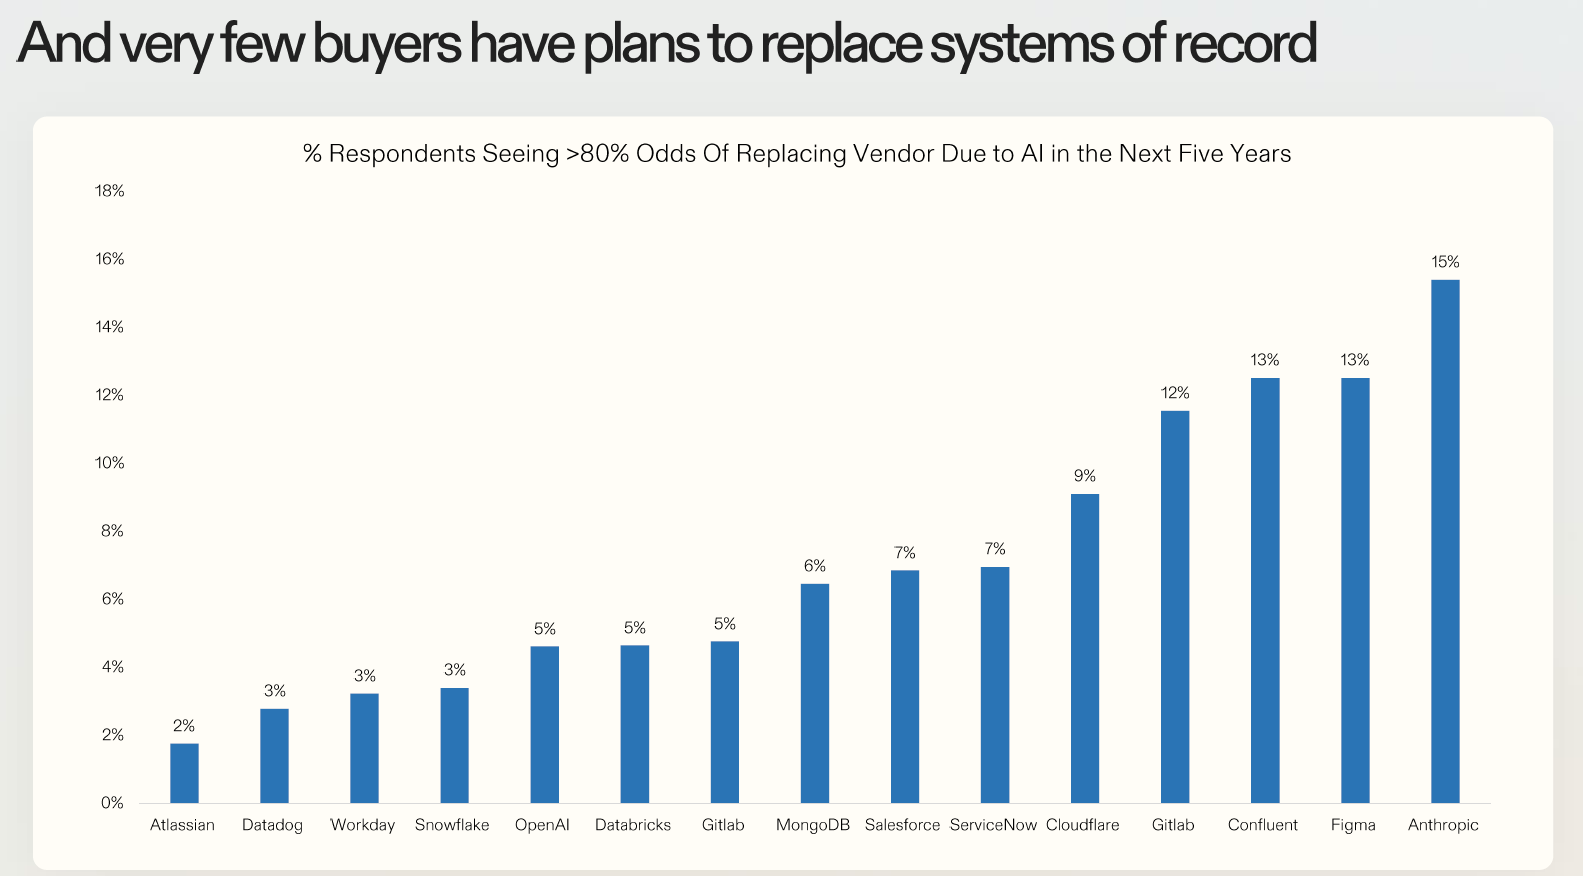
Although a correction in valuations may have been necessary after the earlier peaks, the fundamental position of business-critical software remains intact. Established players such as Constellation and Topicus are not sitting still and have an army of developers testing and sharing lessons across the entire organisation.
The opportunities of a lower valuation
Ironically, the current fear of AI actually creates opportunities for the serial acquirers in which we invest. If the market assigns lower multiples to software companies due to a higher perceived risk, parties such as Topicus and Constellation can put their capital to work at significantly higher expected returns. Michael posed a rhetorical question on this in the podcast: "Do we know any companies that buy software companies, that might actually benefit from lower multiples?" Because of the lower valuations, these investment holding companies can complete more acquisitions at a higher return on invested capital. In addition, AI enables our VMS companies to drastically shorten the development time of new features. As we discussed in the deep dive: "The software is essentially the infrastructure layer. And on top of that software, you can build all kinds of applications using AI." Should disruption nevertheless occur somewhere within the portfolio, the extensive internal diversification and the strength of the ecosystem in sharing these lessons ensure that the other subsidiaries immediately become more resilient.

From theory to practice
Meanwhile, our companies are taking concrete steps to integrate AI. Topicus subsidiary PinkRoccade recently launched the PinkAI programme internally to roll out AI broadly across every department, from sales to customer support and development. CEO David Nyland of Constellation subsidiary Lumine Group emphasised in his New Year letter the focus on responsibly embedding AI to achieve measurable results. This is not about gadgets but about streamlining processes and increasing safety and reliability.
The real value is shifting from simply recording data to understanding the context in which the user works. Because the applications of our portfolio companies know precisely what goal a doctor or civil servant is pursuing at that moment, AI can proactively support rather than merely register. This deep integration into the work process makes the software indispensable, allowing the companies we invest in to maintain their strong competitive position.
Chapters Group, Constellation Software and Topicus.com are currently trading on the Frankfurt and Toronto stock exchanges at prices of EUR 40.50, CAD 2,772.01 and CAD 116.31 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
D’Ieteren's star is repaired and ready for the stock market
Two weeks ago, we shared five slightly playful but substantively serious predictions for 2026. They were explicitly intended as a thought exercise, but remarkably, one of those scenarios now appears to be taking concrete shape barely two weeks later.
 Joep Dikken
Here you can read back the five predictions for 2026
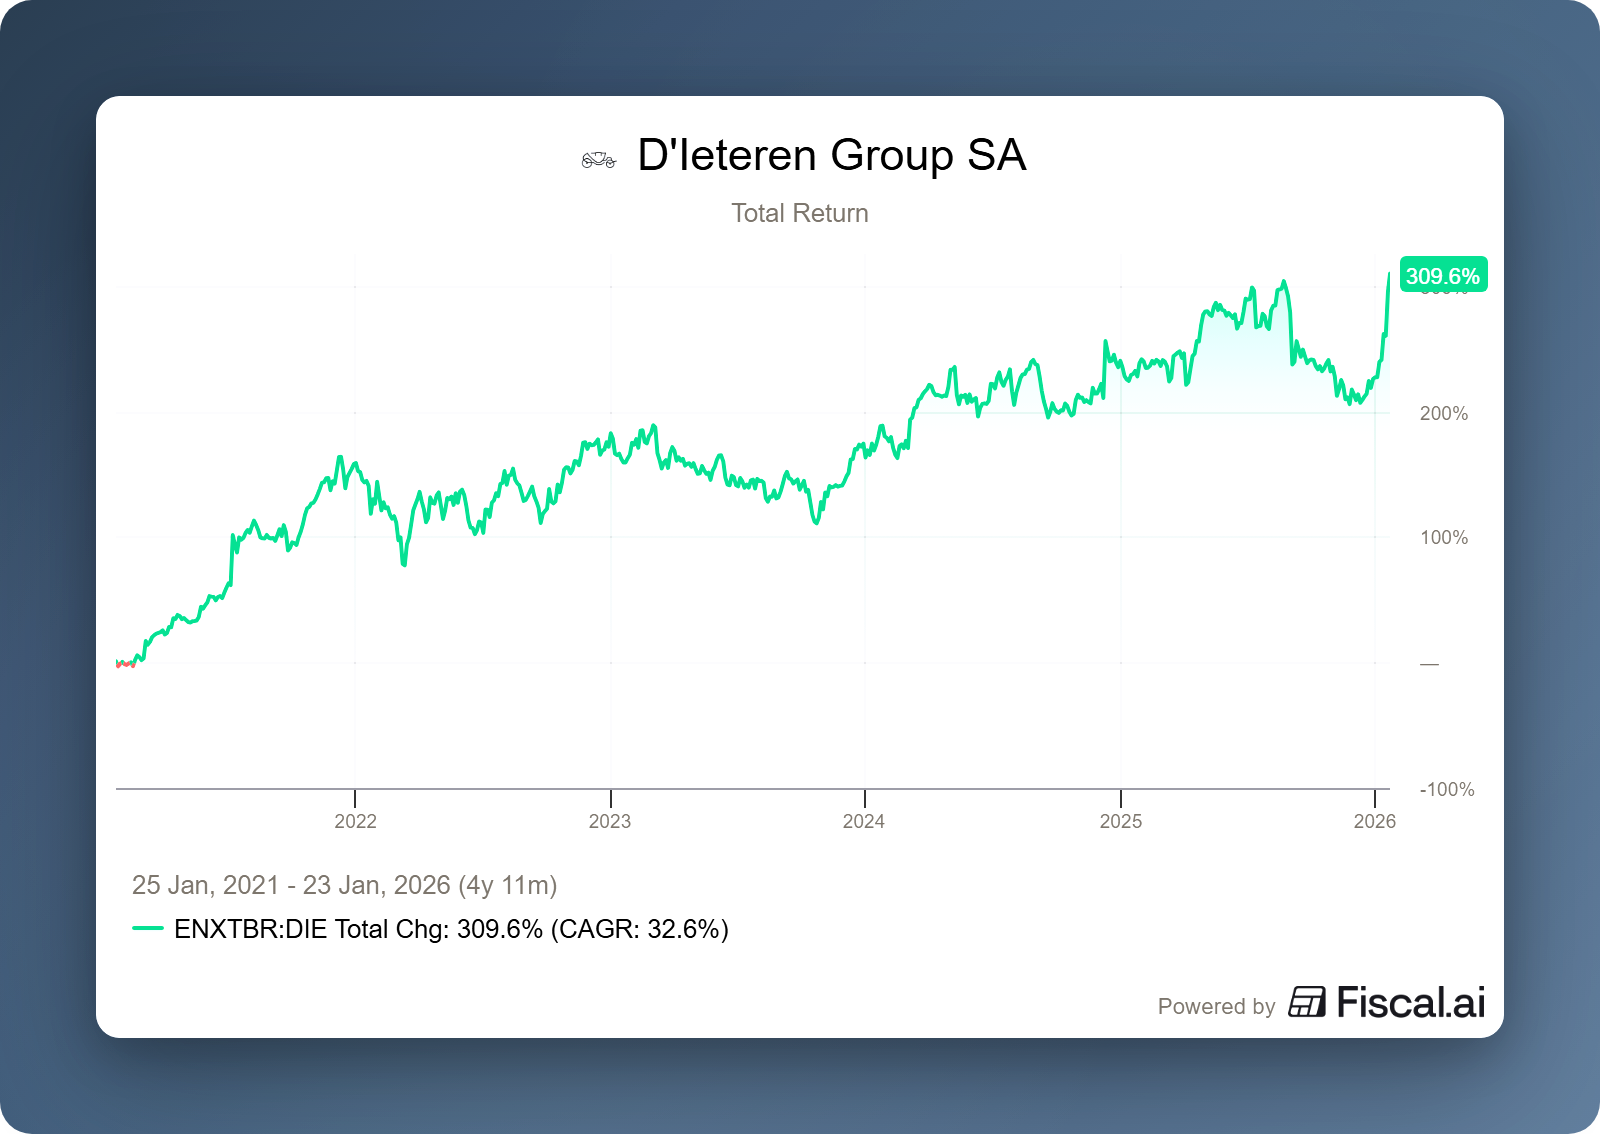
Last week, several banks raised their price target for the Belgian investment holding company D’Ieteren (Brussels: DIE). Shortly afterwards, The Financial Times reported that Belron, the group's crown jewel, is in early-stage talks with banks about a possible stock market listing in the second half of 2026. Analysts estimate that the listing would involve an enterprise value of €32 billion (equity value of €24 billion plus €8 billion in debt) and would take place on the Amsterdam or New York stock exchange.
Belron has for years been the centre of gravity within the D'Ieteren holding company. The company is the global market leader in vehicle glass repair and replacement, with brands including Carglass and Safelite. Since 2023, Belron has been led by Carlos Brito, an executive with an exceptional track record in scaling and optimising global market leaders. Brito built his reputation as the architect behind the transformation of AB InBev into the world's largest brewer, driven by an almost obsessive focus on cost control, cash flow generation and return on invested capital. Ever since his appointment at Belron, it has always been assumed that he was brought in with a future stock market listing in mind. His leadership style is described as sober and strongly operational. Unnecessary complexity is stripped out, capital allocation is central, and every euro must demonstrably contribute to shareholder value creation.
Over the last twelve months, Belron reported revenue of approximately €6.6 billion, with adjusted operating profit of around €1.4 billion, equating to a margin of more than 21%. D'Ieteren owns 50.3% of Belron, but Belron also carries a significant net debt position. Based on the latest reporting, net debt stands at approximately €8.3 billion. This means that the equity value is substantially lower than the enterprise value being discussed in the IPO speculation. After this correction, D'Ieteren's economic interest would roughly amount to €8 to €12 billion.
This calculation does assume that the group's stake remains unchanged. From an economic perspective this makes sense given Belron's quality and cash flow generation. In the event of an IPO, however, a broader free float may be desirable to increase attractiveness to institutional investors, so it cannot be ruled out that D'Ieteren will monetise part of its stake.
D'Ieteren ended the trading week on the Brussels stock exchange at a price of EUR 194.10 per share.
Sofina gives an initial glimpse of its annual figures
Another Belgian investment holding company also made the news this week. Sofina (Brussels: SOF) published a newsletter with an initial update on its results for calendar year 2025. The provisional NAV per share rose slightly from €296 to €299 compared with half a year earlier. That figure, however, requires some context.
In October 2025, Sofina carried out a capital increase, issuing new shares at a discount. That issuance has a dilutive effect on NAV per share. Adjusted for this share issuance, NAV per share would have come out at approximately €305. That implies a decline of around 2% compared with the €312 per share at the end of 2024 (and an increase of around 3% in the second half of the year), a movement that, according to management, can largely be explained by currency effects rather than a deterioration of the underlying portfolio.
According to CEO Harold Boël, 2025 was "the right time to scale". Companies are staying private for longer, capital is increasingly concentrating with the strongest General Partners, and longer exit cycles are creating opportunities precisely for patient long-term investors such as Sofina. The capital increase thus deliberately expands financial firepower, with the aim of putting this extra capital to work selectively.
The top of the portfolio remains largely unchanged, with ByteDance (TikTok) still the largest position. What also stands out is the rise of Vinted. The platform for second-hand clothing moves up from ninth to seventh place within the top ten, without any transactions being involved. This implies that Vinted's valuation has risen faster than that of some other core positions. It is a signal that this holding, despite earlier partial sales, is once again gaining weight within Sofina.
The newsletter also pays attention to artificial intelligence. Sofina explicitly states how many prompts staff have used internally. A striking metric, but on its own this figure says little and offers hardly any basis for drawing meaningful conclusions about the degree of internal AI integration. The message therefore seems to be mainly that Sofina wants to show that active experimentation with AI is taking place internally, without yet attaching any concrete conclusions or measurable improvements to it. At the same time, management remains level-headed in its positioning towards AI investments. Large language models are now regarded as infrastructure, with scale requirements that make direct investments less attractive. Exposure to AI therefore runs mainly through existing holdings such as Mistral AI and through Sofina Private Funds.
Shortly after the newsletter, two concrete investment updates followed. Sofina again took part in a financing round at Oviva, a European platform for digital care for chronic conditions. Sofina already held a stake of 11.4%, and invested further in a €200 million Series D round, in which investment holding company Kinnevik also played a major role. In addition, Sofina announced a new stake in Cerealis, one of the larger industrial and commercial players in the Portuguese agri-food sector. The group specialises in grain processing, is market leader in pasta and industrial flours, and owns eleven commercial brands, together accounting for more than 130 products. No details have been disclosed regarding the size of the investment.
 Sofina
 Sofina
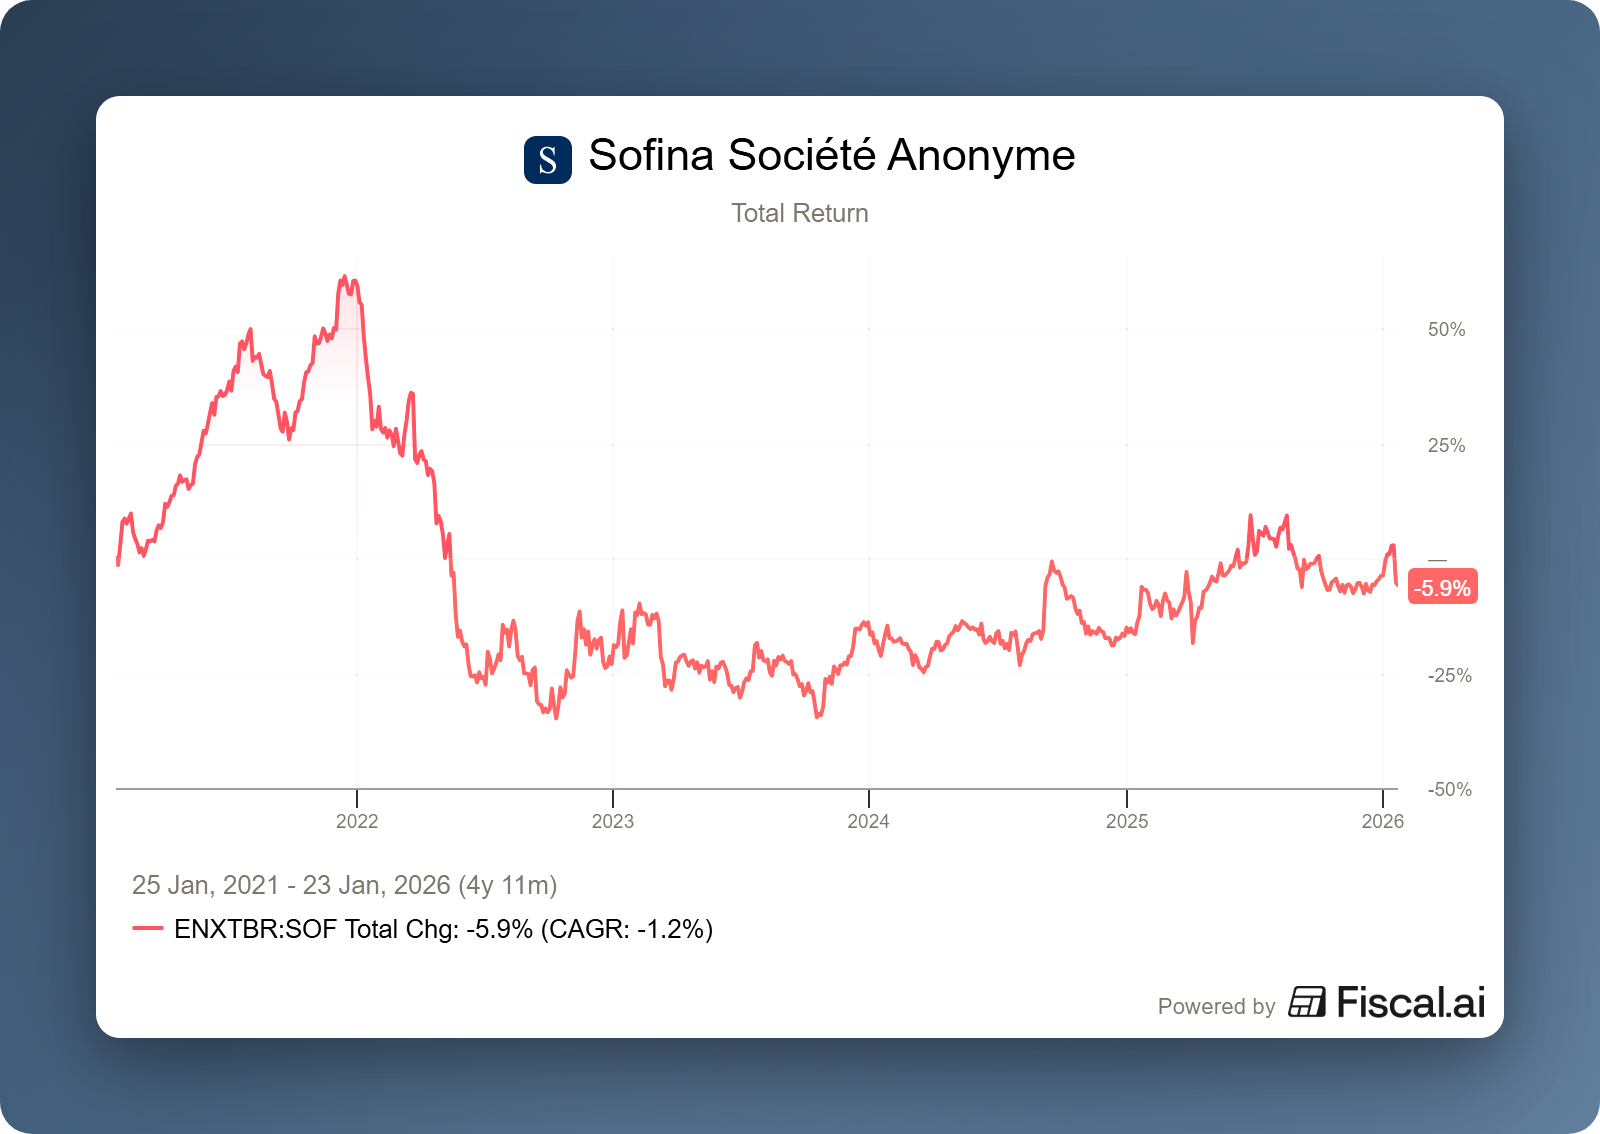
Altogether, according to Harold Boël, the second half of 2025 was in line with the first six months. The core of the portfolio developed stably to positively, despite a challenging macroeconomic climate, geopolitical tensions and a volatile trading environment. With the recent capital increase, Sofina is expanding its room to manoeuvre. The real test still lies ahead, in the question of how this extra capital is effectively put to work and translates into tangible value creation.
Sofina ended the trading week on the Brussels stock exchange at a price of EUR 243.40 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts of it, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to obtain investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you begin investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your invested capital. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts of it, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to take up investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments can fluctuate. Past performance is no guarantee of future results. You may lose (part of) your investment. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



