
Family Holdings #49 - Asseco takes the first steps of the Topicus blueprint



This week's topics:
Asseco presented its results through the third quarter this week, and they show the first, tentative contours of the Topicus/Constellation playbook. Margins took their first step upward, while revenue grew remarkably strongly on an organic basis. In this reporting period, however, Topicus formally still had no role in management; the real integration only begins from October, after approval of the second tranche. This means the bulk of the margin improvement potential still lies ahead of us. The growing backlog and possible future defence contracts could serve as additional catalysts here.
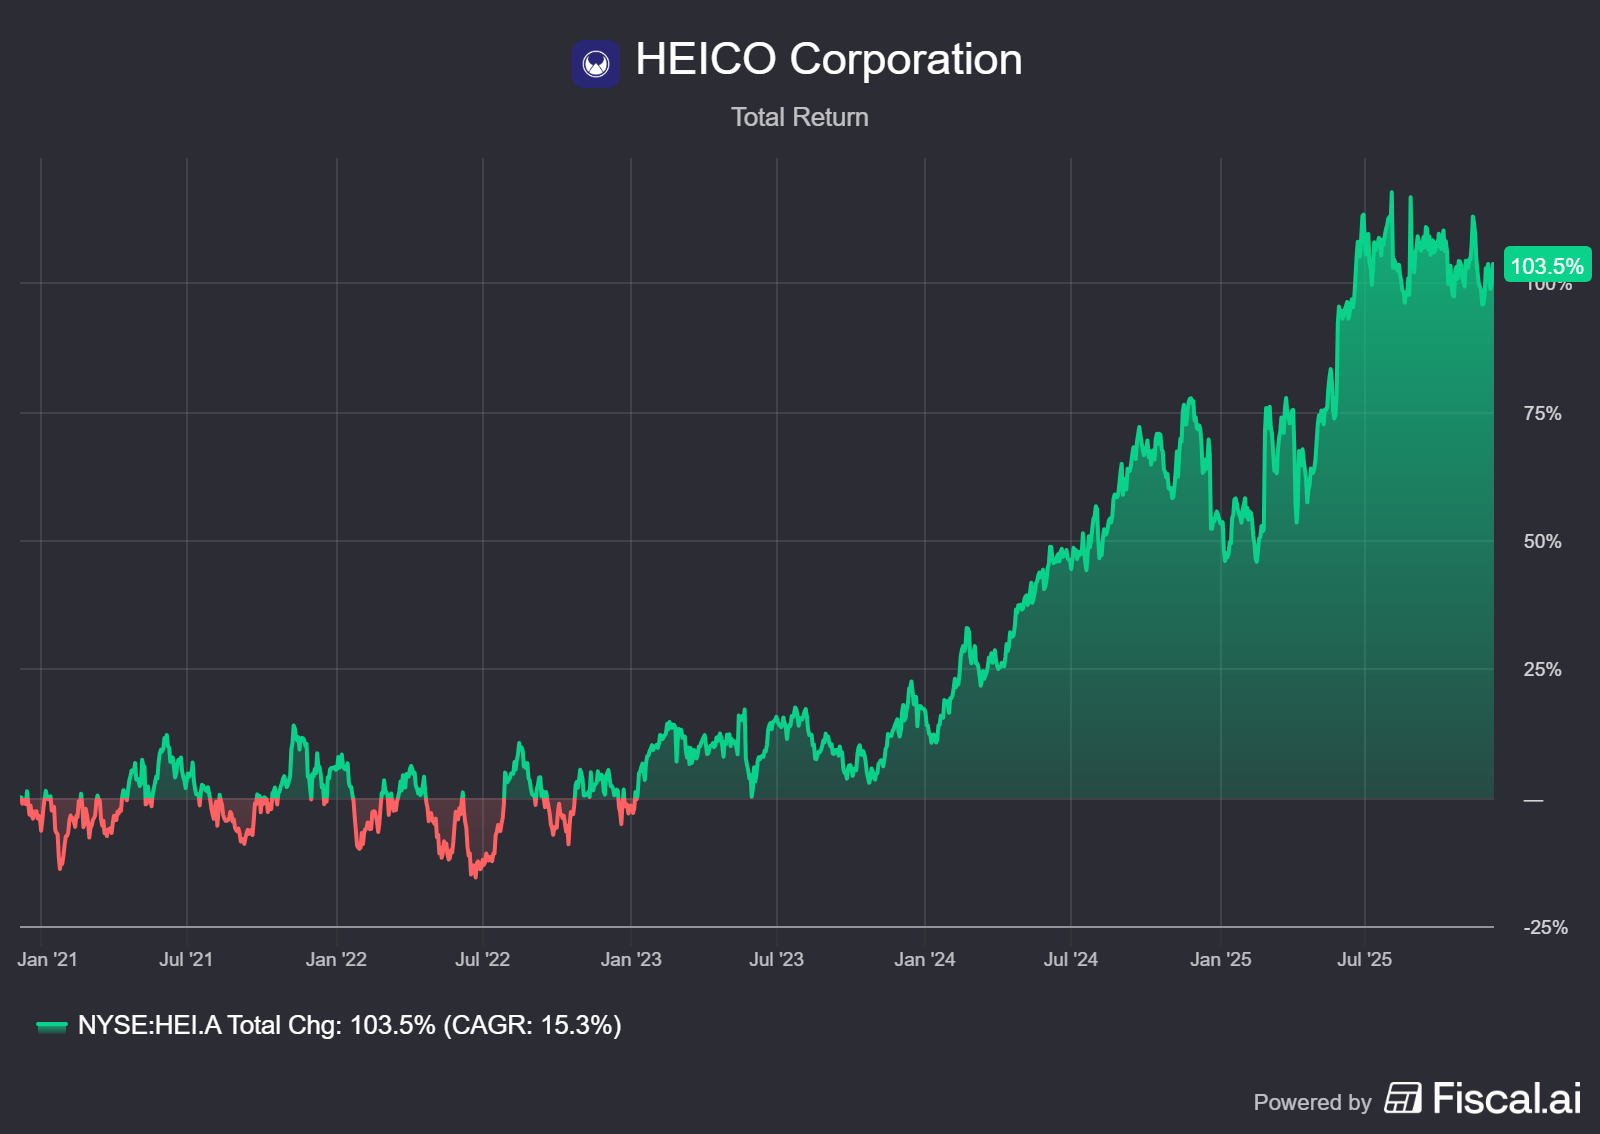
Heico CEO Victor Mendelson once again highlighted, during the recent Gabelli Aerospace & Defense Symposium, why the company performs so exceptionally well: a radical focus on free cash flow, conservative accounting and an acquisition strategy built around entrepreneurship and decentralised responsibility. Heico also continues to build strong positions in specialised segments within aviation, defence and space. Both organic growth and recent acquisitions, such as Wencor, confirm that the proven model remains effective even at larger scale.
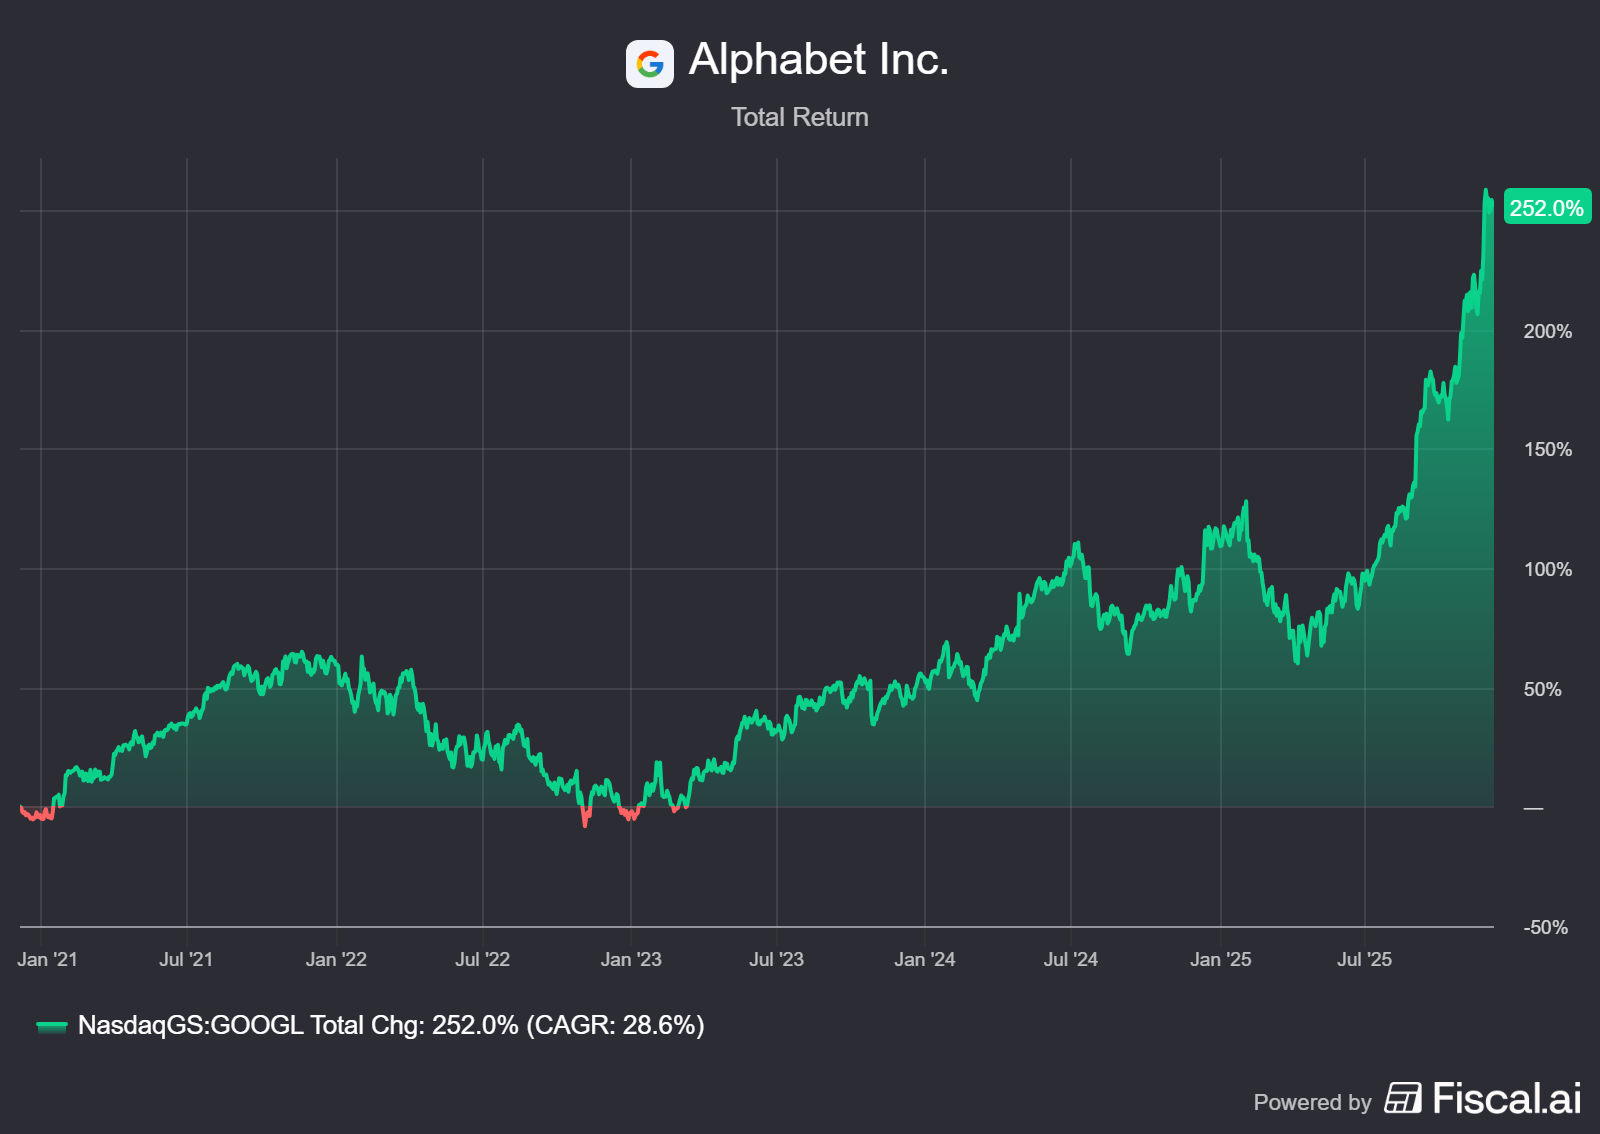
Alphabet CEO Sundar Pichai noted in a recent BBC interview that the current AI investments strongly resemble the internet revolution: plenty of enthusiasm and the risk of overinvestment. Still, just as back then, he sees a lasting technological breakthrough that will significantly change the way we work and live. Alphabet is relatively well positioned here. Thanks to strong cash flows and the fact that new AI infrastructure can be deployed directly within Search, YouTube and Cloud, the investments remain easier for the company to bear than for many of its sector peers.
In Brief:
Constellation Software (Toronto: CSU) was active once again this week through its platform companies. Jonas acquired the UK's Mine Tech Services, a provider of mining consultancy, operational analytics and bespoke software that supports more than 50 mining operations worldwide. In addition, Lumine Group launched an all-cash bid to take Synchronoss Technologies (SNCR) off the Nasdaq at $9 per share, a premium of around 70% to the closing price on 3 December. The transaction values SNCR at $116 million equity value and $258 million enterprise value. Analysts estimate that the acquisition was carried out at an EV/EBITDA multiple of roughly five times expected EBITDA.
Topicus (Toronto: TOI) once again announced expansion in Scandinavia. Subsidiary TSS acquired Scalepoint, a SaaS provider for claims handling within the insurance sector. Scalepoint offers multi-tenant solutions for motor, property and health claims, has 200 employees and has processed more than 15 million claims to date. This is now TSS's fourth acquisition in Denmark. In addition, Topicus's Polish unit Sygnity completed the carve-out of the Healthcare Information Systems business from Comarch HIS for roughly PLN 28 million. The division supplies EHR, monitoring and facility management software to more than 80 hospitals and 200 outpatient clinics, with more than 30,000 daily users.
Prosus (Amsterdam: PRX) announced this week that founder Jitse Groen will step down as CEO of Just Eat Takeaway.com on 1 January 2026. He will be succeeded by Roberto Gandolfo, currently chairman of JET's Supervisory Board and Head of Prosus Europe. Groen's departure marks the end of a quarter century of entrepreneurship in which he built JET from a student room in Enschede into a global player with 60 million consumers, 362,000 partners and €19 billion in GMV. Gandolfo, who at iFood scaled a marketplace business from 1 million to 120 million monthly orders, is now tasked with shaping the next phase of growth under Prosus ownership.
Berkshire Hathaway (New York: BRK.B) has, through its subsidiary BNSF Railway, asked regulator STB to review the nearly thirty-year-old competitive conditions surrounding Union Pacific's acquisition of Southern Pacific. According to BNSF, the promised market access has in many cases been eroded because Union Pacific has in practice allegedly delayed or hindered competing access. By requesting a formal review, BNSF aims to ensure that these rights are actually enforced and possibly tightened. Such an outcome would give BNSF more commercial room on routes where it is currently constrained.
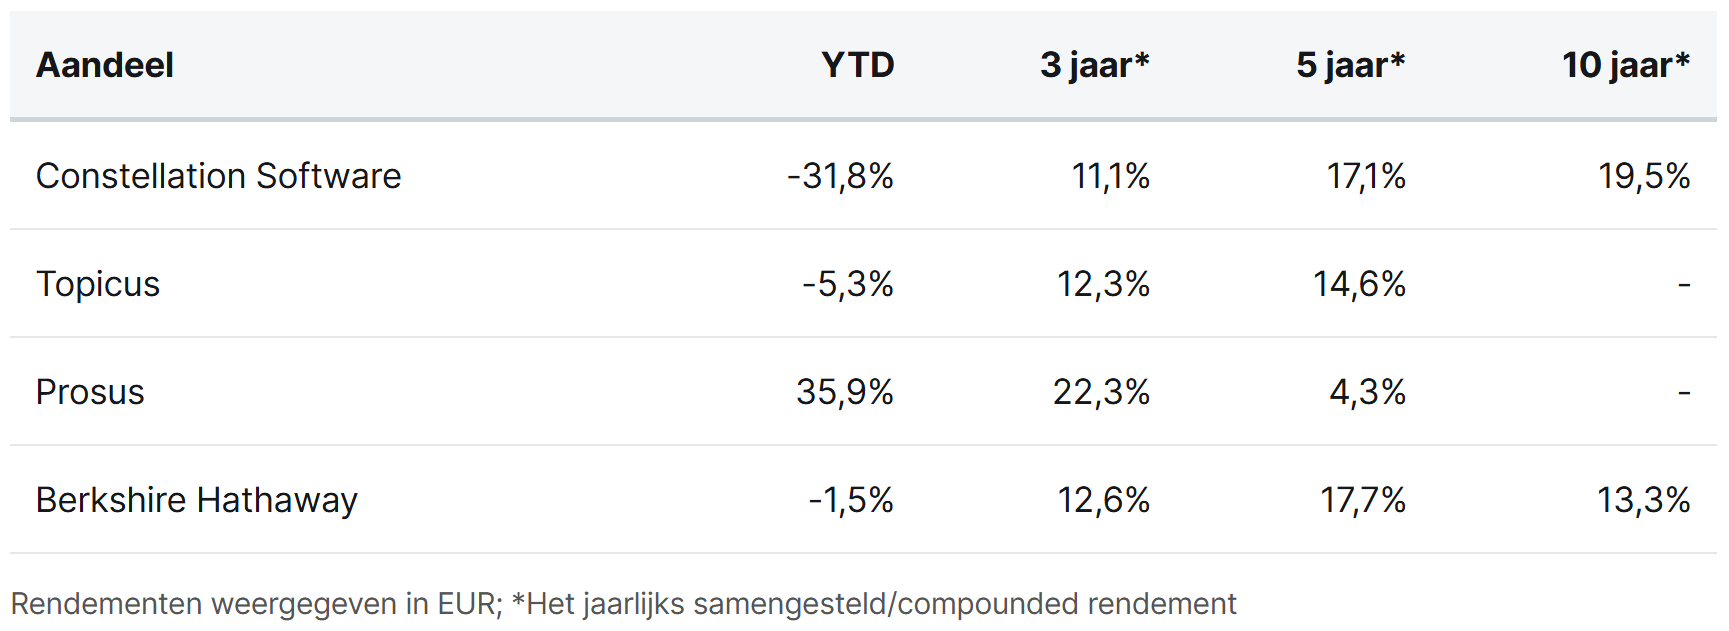
Constellation Software, Topicus, Prosus and Berkshire Hathaway are currently trading on the Toronto, Amsterdam and New York stock exchanges at prices of CAD 3,314.66, CAD 125.01, EUR 52.12 and USD 504.25 (Class B share), respectively.
1, 2, 3i, Action!
Last week, Tresor Capital once again contributed to this year's 10th edition of the "Guide to the Best Investor" published by the Vlaamse Federatie van Beleggers (VFB, the Flemish Federation of Investors). Analyst Joep Dikken wrote an extensive analysis of 3i Group and their goldmine Action. The piece brings together our two recent articles on the company and combines the strategic insights with a straightforward valuation analysis.
 Michael Gielkens
 Joep Dikken
In our piece, we pointed out that 3i keeps Action's valuation remarkably conservative. For years, management has valued the chain at a multiple of 18.5x EBITDA, at the low end of the spectrum when compared to international sector peers, which amounts to €46.9 billion. After all, retailers such as Costco, Dollarama and Ollie's structurally trade at 22x to above 30x EBITDA.
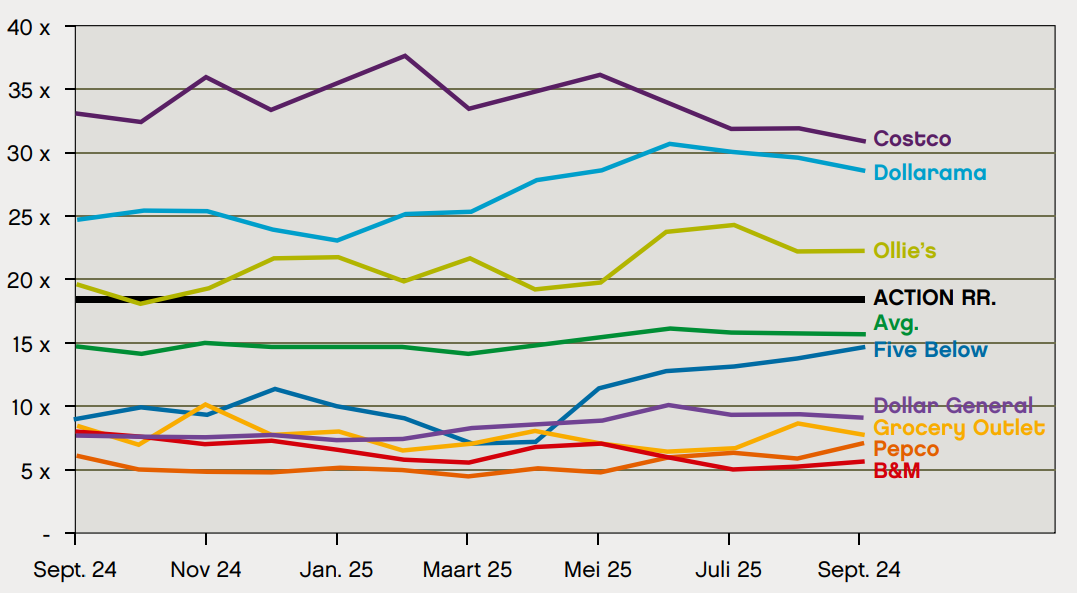
Given Action's exceptional qualities: a payback period of less than one year, a decade of structurally above-average growth, and an expansion model that has exceeded every expectation for ten years running, it is plausible that a stock market listing would lead to a significantly higher valuation than the current internal one. Even a conservative 25x EBITDA, still below Costco's level, already implies a value of roughly €63 billion today.
An at least equally realistic alternative is that Action does not go public in the coming years. In that case, the valuation will likely continue to be kept deliberately conservative by 3i. But even under those cautious assumptions, a similar picture emerges: take the current 18.5x EBITDA multiple, assume moderate annual growth of 14% (10% from store expansion and 4% like-for-like; historically these figures were closer to 14% and 8% respectively), and apply a required return of 10%, and you still arrive at a value of roughly €61 billion.
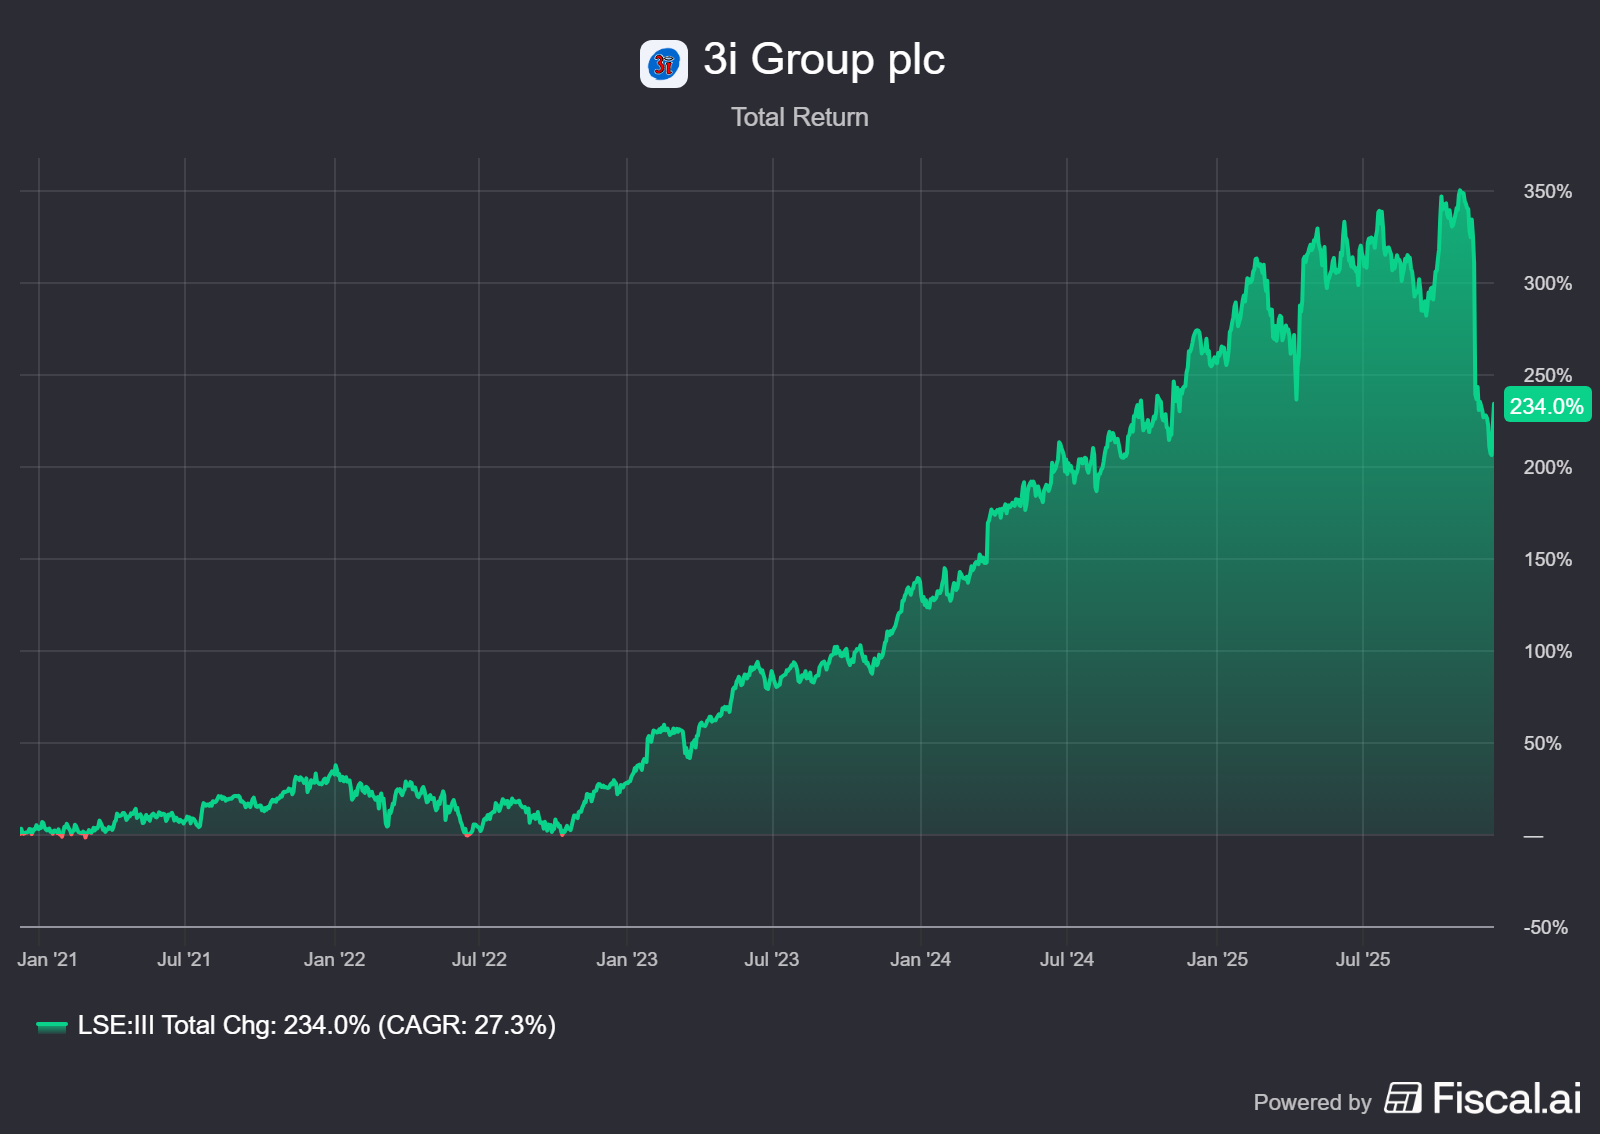
Whichever scenario you choose, the conclusion remains the same: the implied value of 3i's stake in Action covers almost the entire market capitalisation of 3i Group. The rest of the portfolio, which has generated an IRR of at least 20% for years, essentially comes for free.
For those who want to read our full analysis in the magazine:
The VFB regularly publishes extensive guides featuring analyses of a wide range of companies. These editions bring together in-depth contributions from leading Dutch and Belgian analysts, and are definitely worth recommending to any serious investor.
3i Group PLC ended the trading week on the London Stock Exchange at a price of GBP 32.31 per share.
Asseco takes the first steps
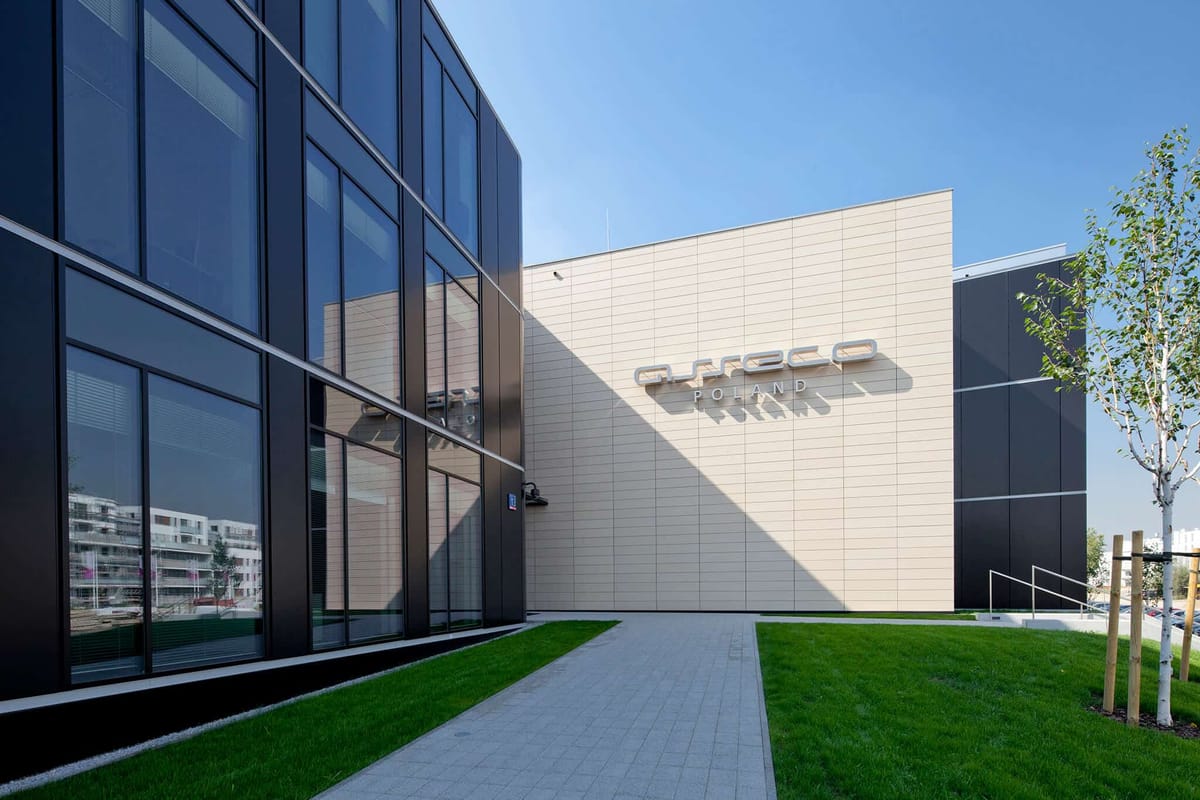
After publication of its figures was postponed last week due to the sale of its stake in Sapiens, Asseco Poland (Warsaw: ACP) finally presented its results through to the third quarter this week. These figures are essentially about the application of the well-known Topicus and Constellation playbook, aimed at structural margin improvement.
Earlier this year, the head of M&A at one of Constellation's platforms summed up the investment case for Asseco in a single sentence during a Speedwell podcast:
"Constellation/Topicus is fairly confident that it can acquire virtually any software company and bring it to around 30% profitability, regardless of that company's shape or size."
Asseco's figures show the first effects of the Canadian blueprint for margin improvement. It is important to stress here that the recent reporting period runs through to the end of September. During this period, Topicus held only a 10% stake and did not yet have an official board role within the company. Although there have been suggestions that Topicus was already exerting influence behind the scenes, the second tranche of 15% was only approved in October. Since then, Topicus's board members have officially taken their seats.
The image below shows that the Asseco Poland and Formula Systems segments in particular are achieving clear margin improvements. For the group as a whole, the operating profit margin rose from 12.2% to 13.5%, pointing to a broad-based, structural efficiency gain.
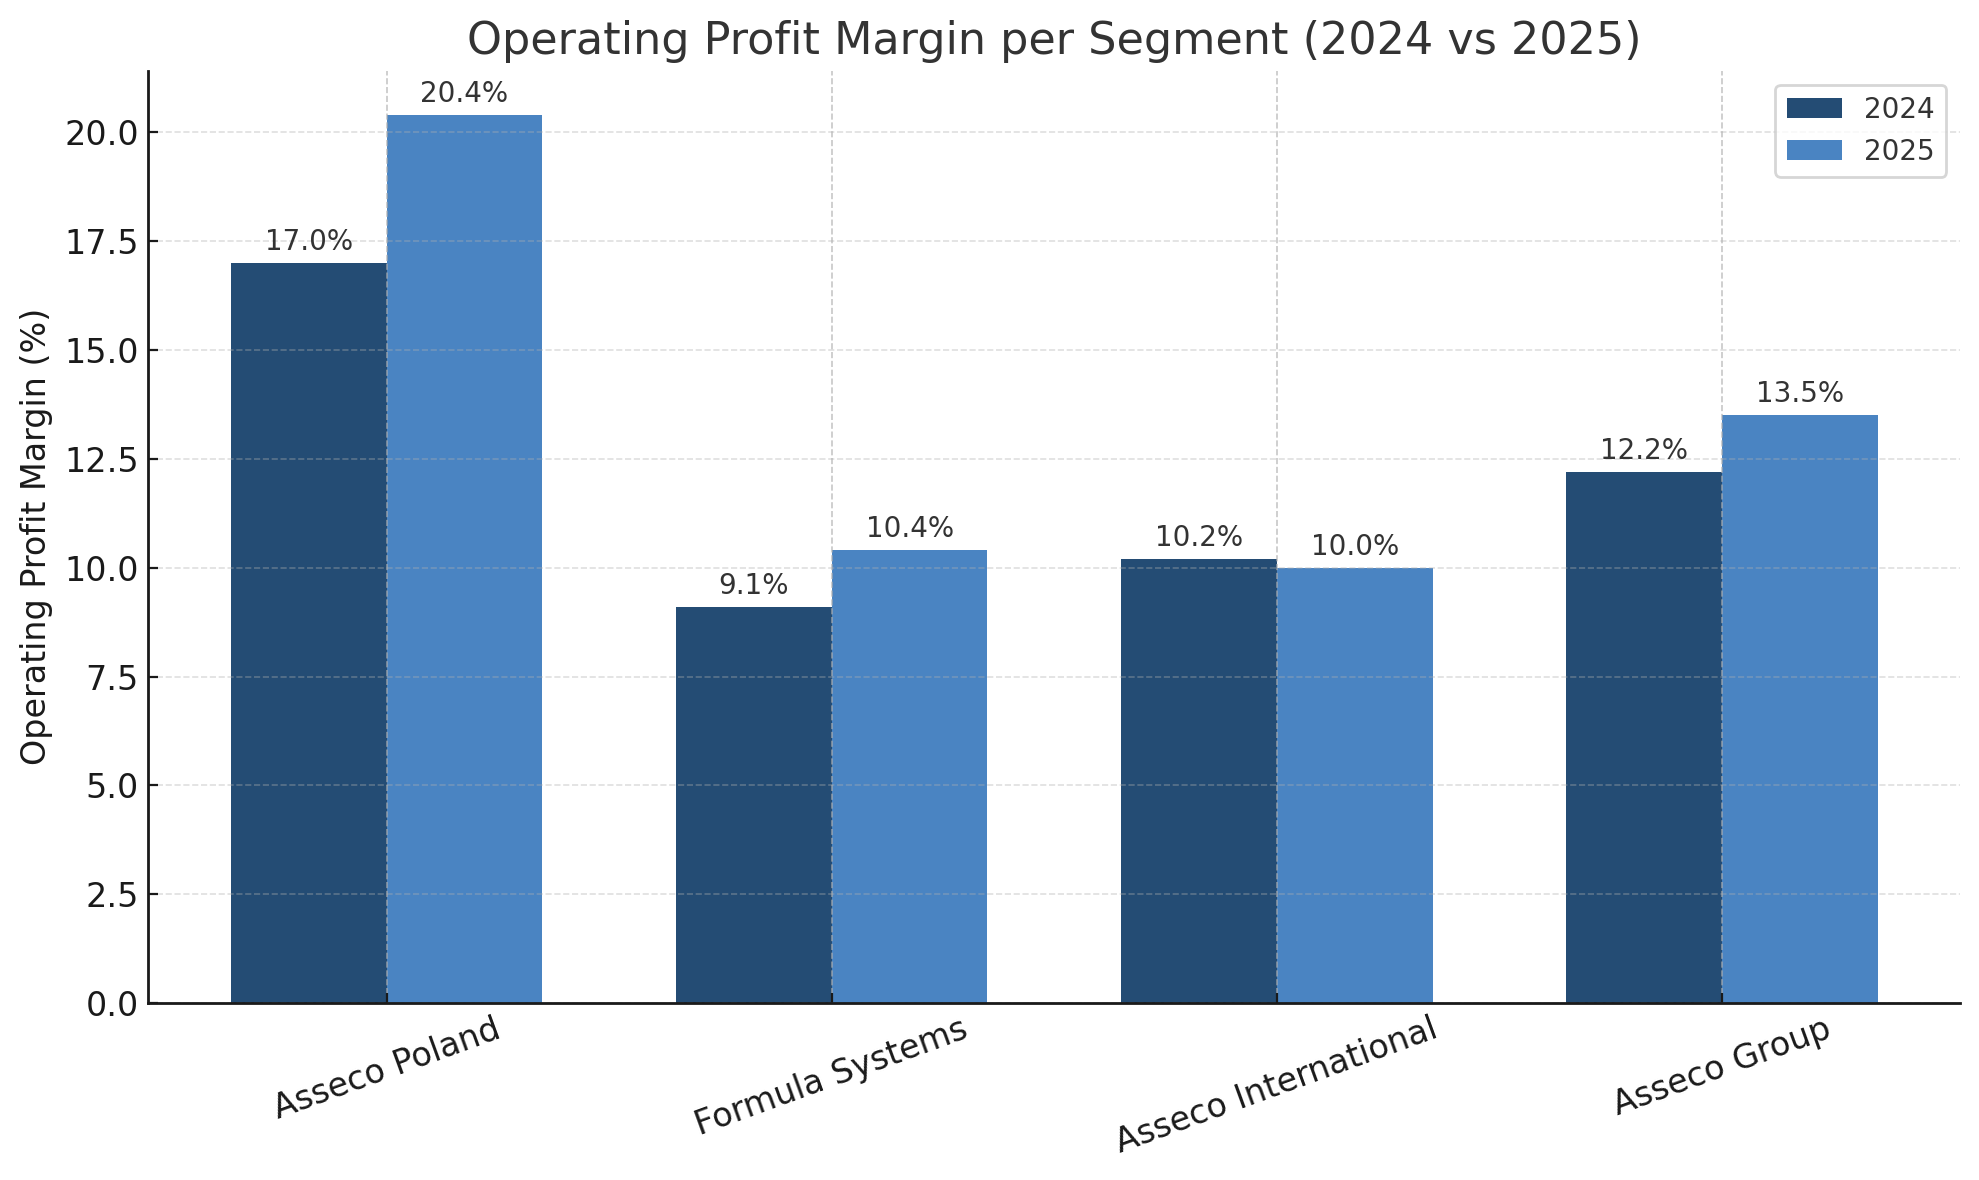
That is encouraging, but it also shows that Asseco still has considerable room for further margin improvement. If we take as a benchmark the 30% profitability that Constellation/Topicus claims to achieve with acquired software companies, a large part of the value case potentially still lies ahead.
Although margin improvement forms the core of the investment case, it is equally important that the company continues to grow strongly in revenue. After adjusting for non-controlling interests, revenue grew by 13.6%. Asseco is a serial acquirer and has already completed nine acquisitions this year, but this growth turns out to be almost entirely organic.
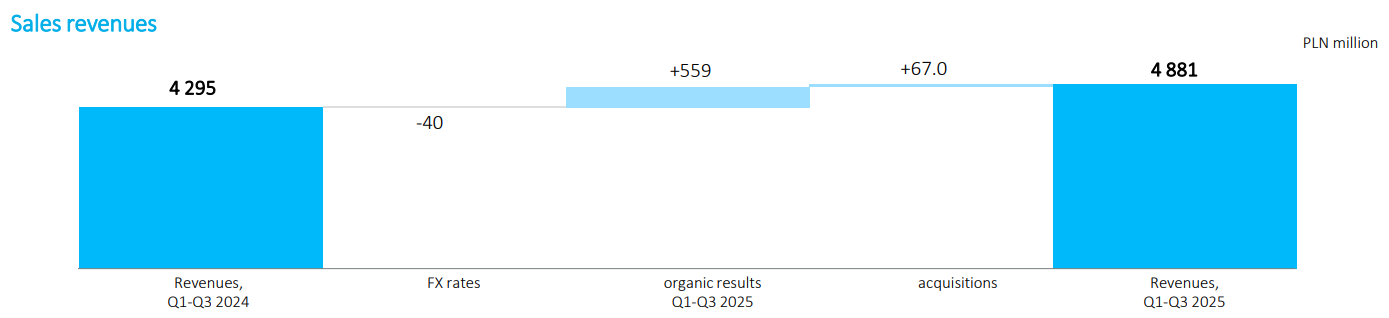
That can mean several things: more orders from new clients, successful upselling of additional services within the existing client base, or price increases. The order backlog, which grew by 12%, supports this picture and suggests that demand for Asseco's products and services will also remain robust going forward.
For those who want to delve further into Asseco, we recommend the recent and thorough analysis by analyst Ole Ensrud on The Outsiders' Corner. In this piece, he breaks down Asseco's structure, historical value creation, geographic footprint and the strategic plans for the partnership with Topicus.
 Ole
We would also like to refer you to our own analysis, in which we specifically examine the broader Polish economic landscape. In it, we show why Asseco, as the country's second-largest cloud infrastructure player with deep roots in crucial sectors, is perfectly positioned to benefit from Poland's strong, structural economic growth.
 Joep Dikken
Conclusion:
The investment case for Asseco has been set in motion cautiously: the first signs of margin improvement are visible, but the real work still has to happen over the coming quarters and years. Now that the second tranche has been approved and the Topicus board members have officially joined, the Constellation playbook can truly be rolled out. If Topicus manages to make the same impact as it did at Sygnity, there is still considerable improvement and value potential on the table.
Management also notes that the company is counting on a revival in the defence segment. Asseco has relevant digital solutions, such as battlefield observation systems, software for uniformed services and satellite applications, which could gain traction once the Polish armed forces launch new IT procurement programmes. Although no major military contracts are currently in sight, this represents a possible additional catalyst for the coming years.
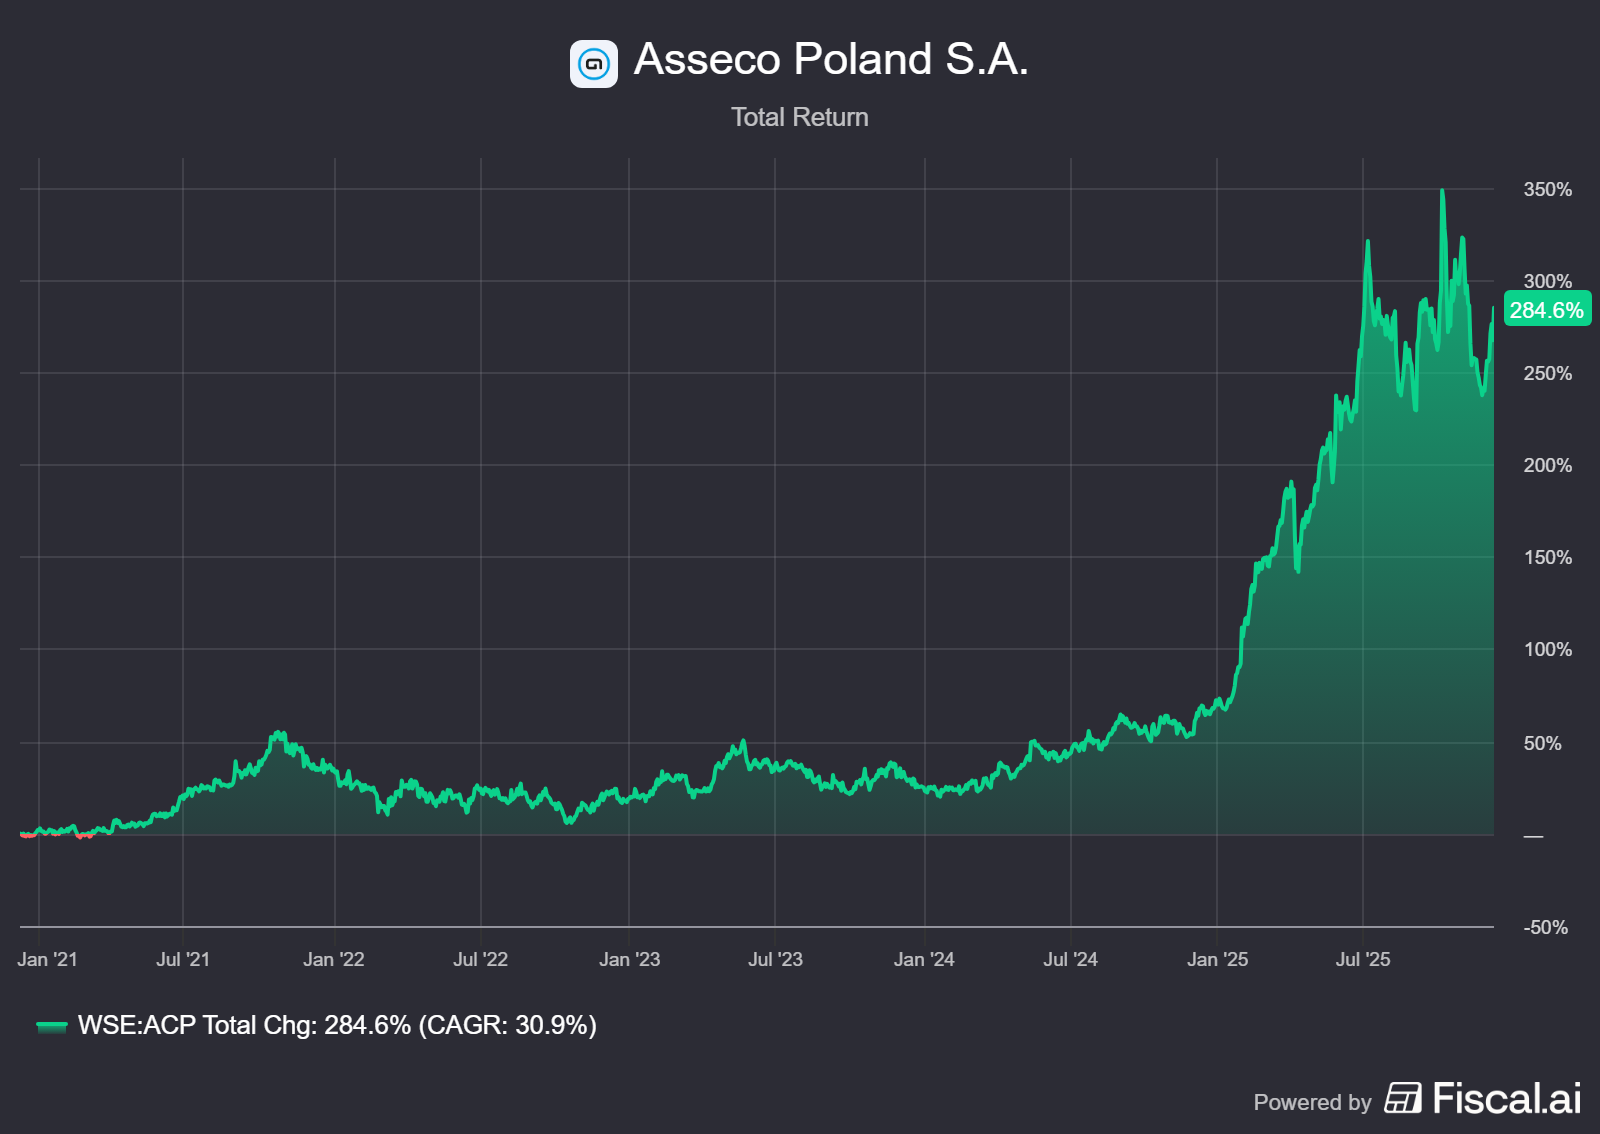
Asseco Poland ended the trading week on the Warsaw stock exchange at a price of PLN 211.60 per share.
Heico: profit is an opinion, cash is a fact
The story of the American serial acquirer Heico (New York: HEI-A) is one of the most impressive compounding cases on the stock market. Since the Mendelson family took charge of the then still small company, with a market value of just USD 25 million, in 1990, Heico has grown into a dominant player with an enterprise value of around USD 40 billion.
We recently wrote an extensive Deep Dive on the strength of Heico. The recent Gabelli Aerospace & Defense Symposium offered an excellent opportunity to look deeper into the mind of management. Victor Mendelson, co-president and CEO of the Electronic Technologies Group, shared insights there that confirm why this company deserves a core position in our portfolio.
 Michael Gielkens
Cash is the only truth
Heico's financial discipline is legendary and has its origins in a simple lesson that Larry Mendelson instilled in his sons Eric and Victor. Doing business comes down to just three things: cash, cash and more cash. Profit on paper is patient, and accounting constructions can obscure reality. Free cash flow, on the other hand, never lies.
This translates into conservative accounting. Heico refuses to go along with the trend of 'adjusted EBITDA', whereby real costs are stripped out to present profitability in a rosier light. Management looks at hard EBITA and regards depreciation as a necessary proxy for maintenance capital expenditure (CapEx). This focus on actual cash flows enables its management to integrate acquisitions quickly and pay down debt aggressively.
Aviation's generic medicine
Although we already discussed the PMA model in our earlier analysis, Mendelson made a striking comparison during the symposium. He describes the Flight Support Group as the manufacturer of generic medicines for aviation. Just as in pharmaceuticals, Heico offers an alternative that is qualitatively identical to, or superior to, the original, but at a fraction of the price. This breaks the OEMs' monopoly position and creates a loyal customer base.
Within the Electronic Technologies Group, which Victor leads directly, the philosophy is subtly different but equally effective. Here, Heico focuses on components that he describes as products you don't fly in, but without which you won't get off the ground. These are defence and aerospace subcomponents that are essential to the functioning of systems costing millions. Because the cost of the Heico part is negligible compared with the total price of, for example, a missile shield, the customer's price sensitivity is minimal. This enables Heico to maintain dominant positions in small niches with correspondingly high margins.
Successful integration of Wencor
As a serial acquirer, the integration of new companies is crucial. Mendelson gave an update on the recent acquisition of Wencor, the largest deal in the company's history. The signals are extremely positive. The cultural fit is proving seamless and performance is exceeding expectations. It confirms that the decentralised model, in which founders stay on board and retain their entrepreneurial spirit, also works at greater scale.
Heico continues to stick to its strategy of buying healthy companies led by their founders. These entrepreneurs often retain a stake of around 20% in their own company, meaning that the subsidiaries also keep skin in the game and their interests remain fully aligned with those of shareholders. With a well-filled M&A pipeline and a proven ability to reinvest capital at high returns, the Mendelson family's compounding machine continues to run at full speed.
Heico is currently trading on the New York stock exchange at a price of USD 243.10 per A share.
Alphabet CEO: "Big Tech will overinvest in AI"
In a recent BBC interview, Sundar Pichai, CEO of Alphabet (New York: GOOGL), draws an interesting parallel between the current AI rally and the internet revolution of the late 1990s. According to Pichai, we find ourselves once again in a period of high market optimism and substantial capital allocation, with a realistic chance that the sector is collectively investing more than is strictly necessary. But, he emphasises, even the dot-com bubble could not stop the structural breakthrough of the internet. The technology changed and improved the way we live and work forever. He now sees the same thing happening with AI.
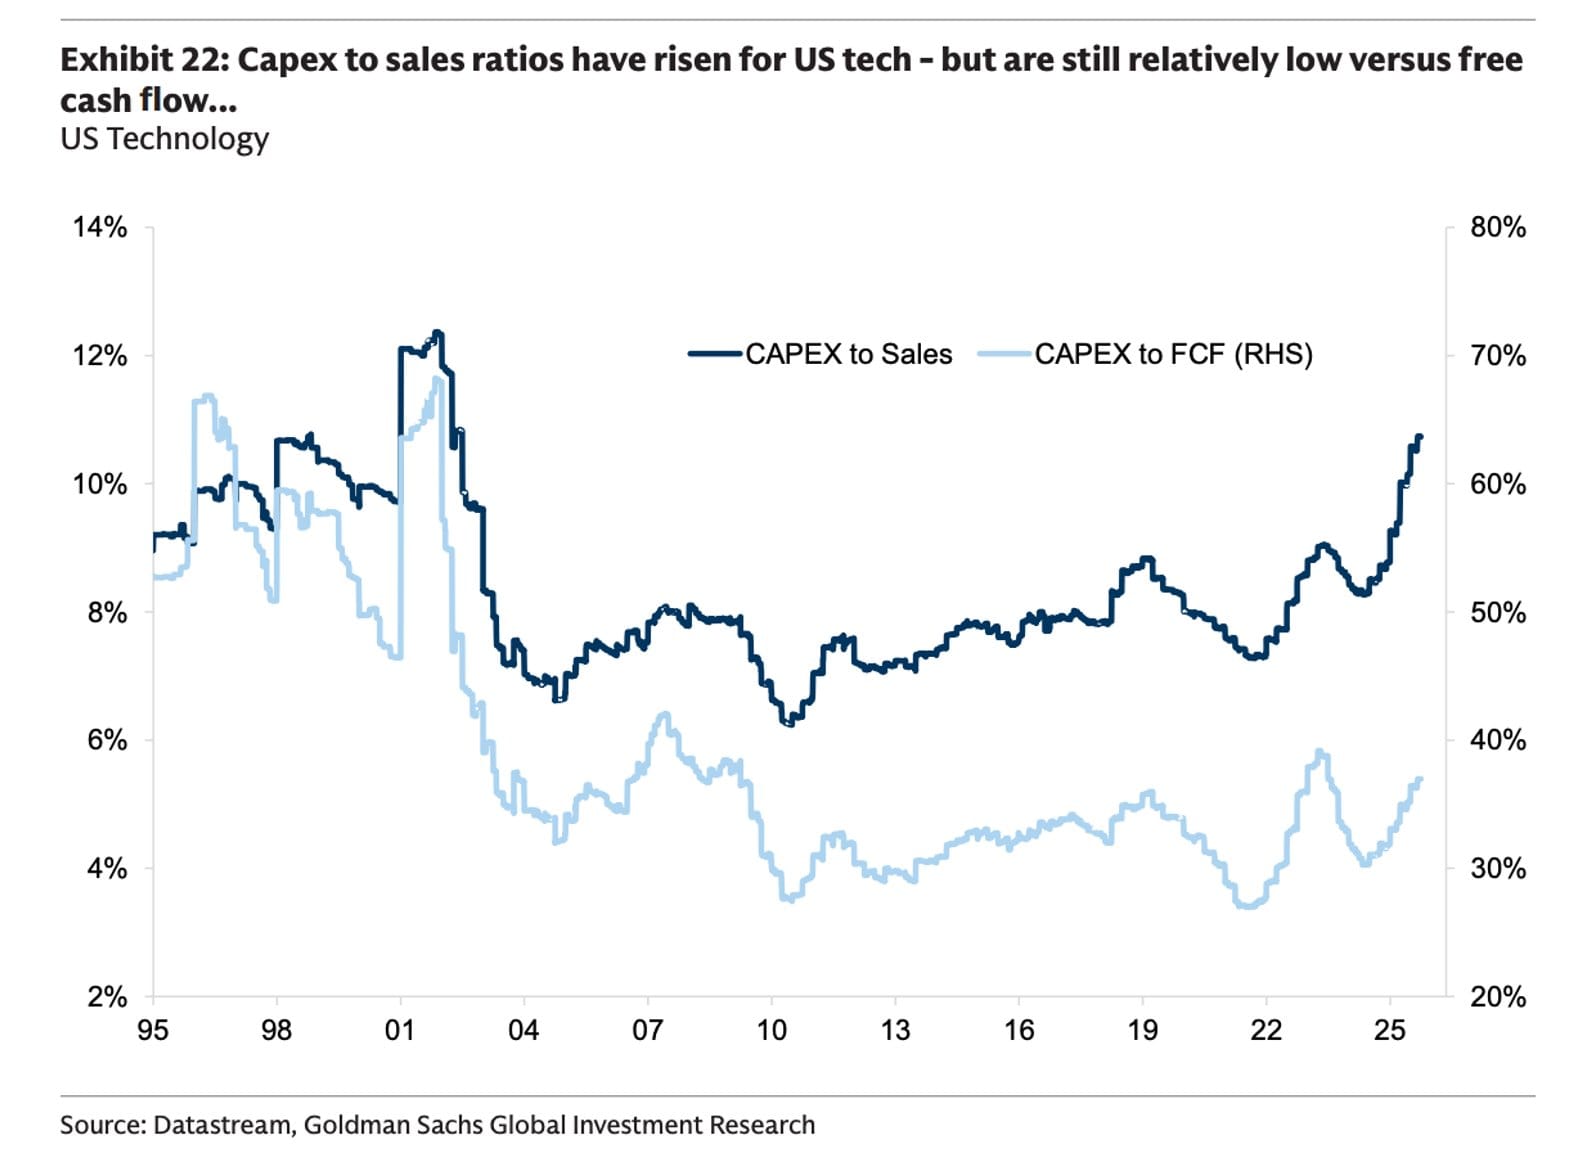
The scale of Alphabet's investment cycle is unprecedented: four years ago, capex (capital expenditure) stood below USD 30 billion; this year, Alphabet will for the first time comfortably exceed USD 90 billion. Together, Big Tech is now investing more than one trillion dollars in AI infrastructure. The chart below shows that these enormous Big Tech investments need to be put into better perspective. Yes, the absolute amounts today are many times higher than during the dot-com bubble. But the underlying profit and cash flow generation of these companies is also far stronger than it was back then.
Whereas tech companies during the dot-com era absorbed a large share of their available cash through investments, that share is now considerably lower. In other words: investment amounts are extremely high, but the companies making them are financially far more robust. As a result, the current AI investment cycle appears much less fragile than the bubble years around 2000. Alphabet is a prime example of this. Despite the enormous scale of its current investments, the company continues to generate more than enough cash flow to cover this spending.
On top of this, many companies will only be able to recoup their AI investments over the longer term. Most businesses are currently building up AI capacity in the hope of monetising it in the future, for example through new products, customers or business models that have yet to emerge. For them, current capex is effectively a prepayment on unknown future demand.
Alphabet finds itself in a completely different position: the company can immediately deploy the same infrastructure within existing, profitable products such as Search, YouTube, Android and Cloud. As a result, the additional capacity starts generating value right away, rather than only years later. Alphabet's broad ecosystem therefore acts as a built-in safety net that supports the current intensity of investment.
At Tresor Capital, we therefore assess the risk of potential overinvestment at Alphabet as well manageable.
Alphabet is currently trading on the New York stock exchange at a price of USD 320.87 per class A share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services? Feel free to get in touch.
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted with written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information must therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to acquire investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments can fluctuate. Past performance offers no guarantee for the future. You may lose (part of) your investment. Tresor Capital rejects any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was originally written in Dutch and automatically translated into English with the help of AI. In case of any difference, the Dutch original prevails.



