
Family Holdings #6 - The diverging capital allocation lessons of Google and Markel


This week's topics:
Addtech reported a third quarter in which revenue growth remained limited, but operational quality came to the fore even more clearly. The EBITA margin rose to 15.6%, driven by exceptionally strong project mixes within Energy and Industrial Solutions. Despite the challenging Swedish macro environment, order intake confirms that underlying demand remains robust. With eight acquisitions this year and the recent acquisition of RAMME Electric Machines, Addtech once again underscores why it ranks among Europe's most high-quality industrial serial acquirers.
Markel Group presented a strong fourth quarter, driven by a clear normalisation in underwriting: the combined ratio fell to 94.6%, with Markel appearing to return to the structurally profitable levels of previous years. CEO Tom Gayner once again emphasised that, despite varying annual results, the equity portfolio continues to generate consistent double-digit returns over longer periods. Looking ahead to 2026, Markel is deliberately choosing quality over growth, with an expected decline in reported premiums due to the exit from reinsurance and the restructuring of the Hagerty model. The target remains a combined ratio in the low 90s, supported by pricing discipline and selectivity.
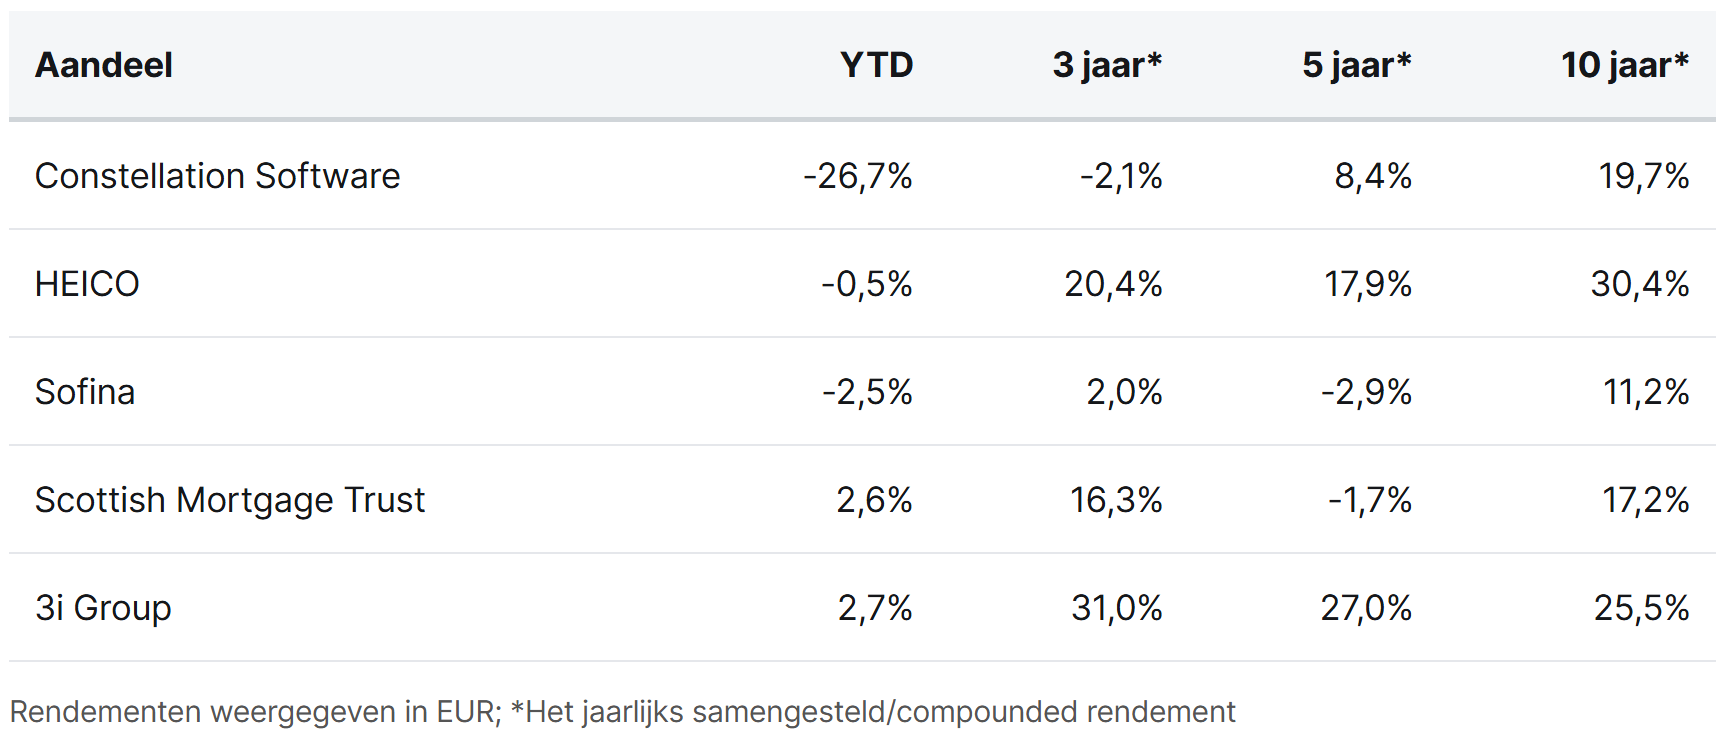
In Brief:
Constellation Software (Toronto: CSU) has started February strongly with five acquisitions. The largest acquisition involves the Scottish company Zonal, which supplies software to the hospitality sector with around 730 employees. The American company Symplicity and the Dutch company WinCar were also added to the portfolio. In addition, software divisions were acquired from RE/MAX, and in Brazil the acquisition of Onegreen followed.
Heico (New York: HEI.A) has acquired EthosEnergy, a leading player in the repair of engine components for the aviation and defence sectors. With 175 employees and locations in the United States and Scotland, this acquisition strengthens Heico's competitive advantage in the industrial gas turbine market.
Sofina (Brussels: SOF) is increasing its stake in The Whole Truth through a new investment of USD 21 million. The holding company is leading this funding round, doubling its ownership in the Indian healthy-food producer to 9.3%. The company, which sells protein bars and muesli among other products, is valued at USD 400 million in this transaction.
SpaceX, the largest position of Scottish Mortgage Trust (London: SMT), is becoming co-owner of a new AI company. Elon Musk is merging SpaceX with xAI into a new group aiming for the largest IPO ever, with a valuation of USD 1,500 billion. The focus is on realising AI data centres in space that run on solar power, thereby bypassing energy constraints on Earth.
Simon Borrows, the CEO of 3i Group (London: III), has further increased his stake in the holding company with a purchase of GBP 1 million. This follows an identical purchase in November last year and underscores both the CEO's confidence in his company and the still attractive valuation at which the holding company trades.
Constellation Software, Heico, Sofina, Scottish Mortgage Trust and 3i Group are currently traded on the exchanges of Toronto, New York, Brussels and London at prices of CAD 2,406.10, USD 251.37 (A-share), EUR 241.00, GBP 12.09 and GBP 33.46 per share, respectively.
Win free access to the Een Hart Voor Beleggen event

During the first edition of the VFB event Een hart voor beleggen in Ghent, Tresor Capital partner Michael Gielkens will speak about the power of holding companies. The day programme, made possible in part by LYNX, offers parallel sessions with experts such as Jan Longeval, Gert De Mesure and Pierre Huylenbroeck.
We are giving away two free tickets among our readers. If interested, please register before Sunday 23:59 using the button below. Please note: each entrant is entitled to only 1 ticket.
📅 Date: Saturday 14 February 2026
🕒 Time: 8:30 a.m. – 4:00 p.m. (including lunch)
📍 Location: Valentin Vaerwyckweg 1, Ghent
Alphabet doubles down on AI investment after strong results
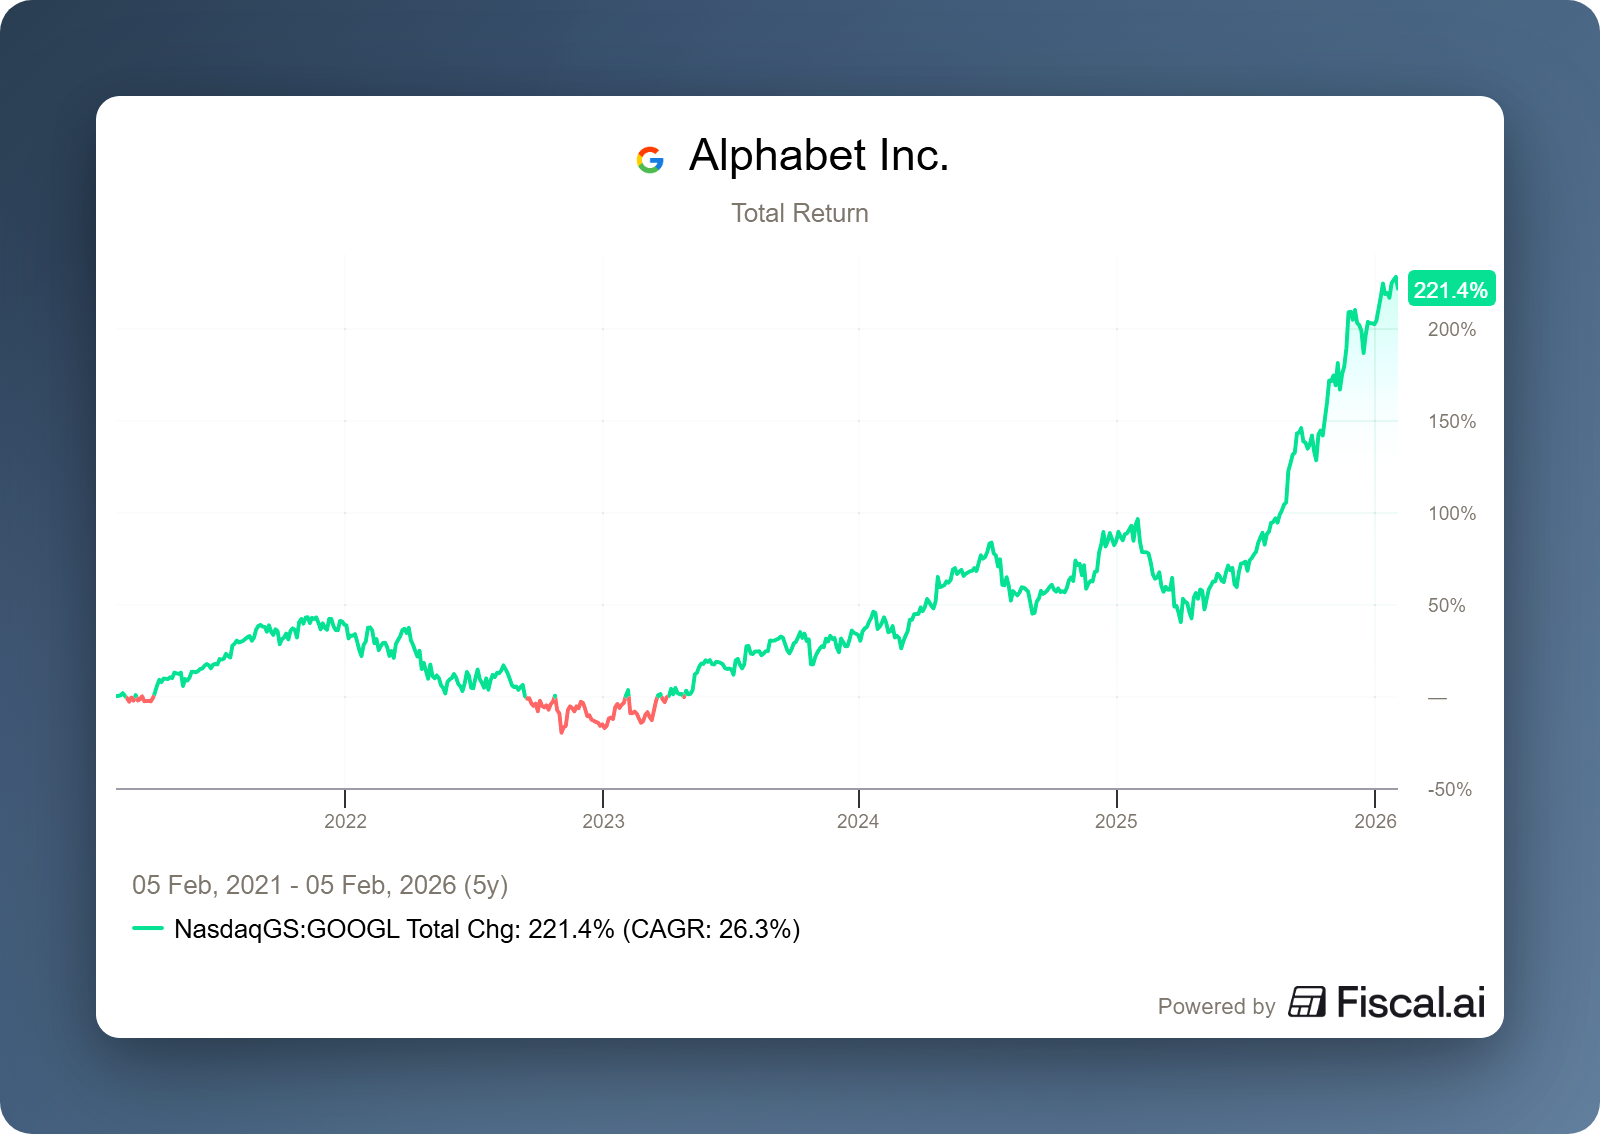
In today's tech market, investors barely look in the rear-view mirror anymore. The results of the past quarter are often already priced in; what really matters is the vision for the future. How does a company position itself in the AI race? How is that technology being commercialised? At the presentation of Alphabet's (New York: GOOGL) annual results, the answer to those questions rang louder than ever.
Just a year ago, Alphabet was still being written off as the biggest loser of the AI revolution. The rise of LLMs such as ChatGPT and Deepseek was supposed to spell the end of the Google search engine. Nothing could have been further from the truth. CEO Sundar Pichai, or 'Sundar Pitch AI' as he might now be called, has shown that Alphabet has not merely embraced AI, but is now dominating it.
The core remains unbeaten
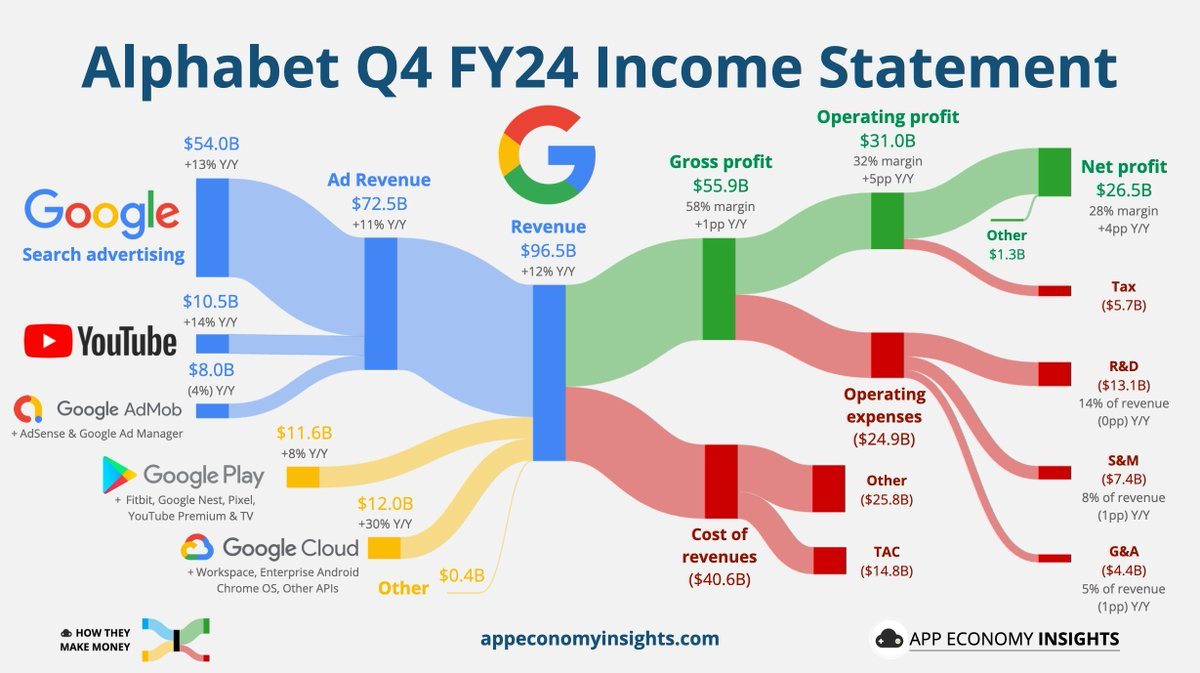
The company's engine, grouped under Google Services (Search, YouTube, AdMob and Google Play), is running at full throttle. In Q4, this division accounted for $95.86 billion in revenue, more than 84% of the total.
- Google Search: Ever since the argument circulated that advertising revenue from the search engine would be disrupted, this segment has in fact only grown harder. Whereas Search's year-on-year (YoY) growth stood at 10% in Q1 2025, it had risen to an impressive 17% by Q4 2025. AI overviews in search results appear to be boosting advertising revenue rather than cannibalising it.
- YouTube: It was acquired back in 2006 for $1.65 billion. YouTube now generates annual revenue of $60 billion (up 9% YoY). YouTube Shorts in particular is a phenomenon: with 200 billion daily views, the average person on the planet now watches around 25 videos a day.
- Subscriptions: The tech giant now counts more than 325 million paid subscriptions, driven by strong adoption of Google One and YouTube Premium. The enterprise AI arm is also growing fast: in just four months, 8 million Gemini Enterprise seats have already been sold. Philipp Schindler, Chief Business Officer, notes that although the shift from a free user to YouTube Premium slightly dampens advertising revenue, the net impact on the business is positive; in other words, Alphabet prefers a stable, predictable cash flow over higher but more volatile advertising revenue.
Google Cloud and AI applications
Last week, Microsoft took a hit after growth of 39% only just managed to beat already lofty expectations. Google Cloud, by contrast, delivered a markedly strong performance and broke records once again.
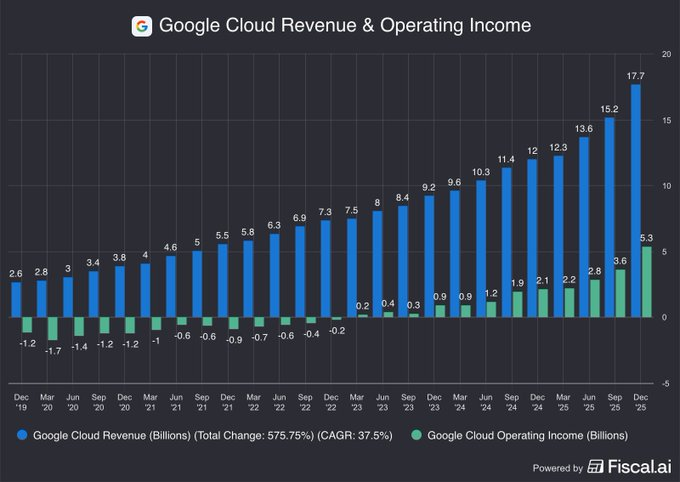
In Q4, the division generated revenue of $17.7 billion, with operating income of $5.3 billion. With these results, the Cloud arm is now on an annual run rate (a forecast of full-year revenue based on results from the most recent period) of $70 billion, up 48% year-on-year.
This acceleration is being driven by increasingly large contracts. CEO Sundar Pichai indicated that the number of deals worth more than $1 billion in 2025 exceeded the total of the three preceding years combined. He also confirmed that Apple has selected Google Cloud as its infrastructure partner for the development of its next-generation AI models.
Looking at margins, the cloud business is not only growing in revenue but is also becoming far more efficient. Whereas the operating margin stood at 17.5% last year, it now stands at 29.9%. According to Sundar Pichai, this margin jump is mainly the result of structural cost improvements in Google Cloud's AI infrastructure. Google currently processes around 10 billion tokens per minute, while the Gemini app has grown to 750 million monthly active users. The cost of running and scaling AI models is falling rapidly as Google optimises its tooling and underlying systems.
"We are getting dramatically more efficient, we were able to lower Gemini serving unit costs by 78% over 2025"
The concern in the numbers: CapEx costs
Despite strong operational results, the share price reacted negatively to the results. The main reason for this is the CapEx guidance for 2026, which Google set at $175–185 billion, significantly higher than analysts' expectations of around $120 billion. Investors remain visibly wary of this kind of extreme investment level among hyperscalers. Google is not alone in this, however. Microsoft, Meta and Amazon have also recently issued CapEx plans that came in above expectations. Together, this group of hyperscalers appears to be heading towards more than $600 billion in CapEx in 2026.
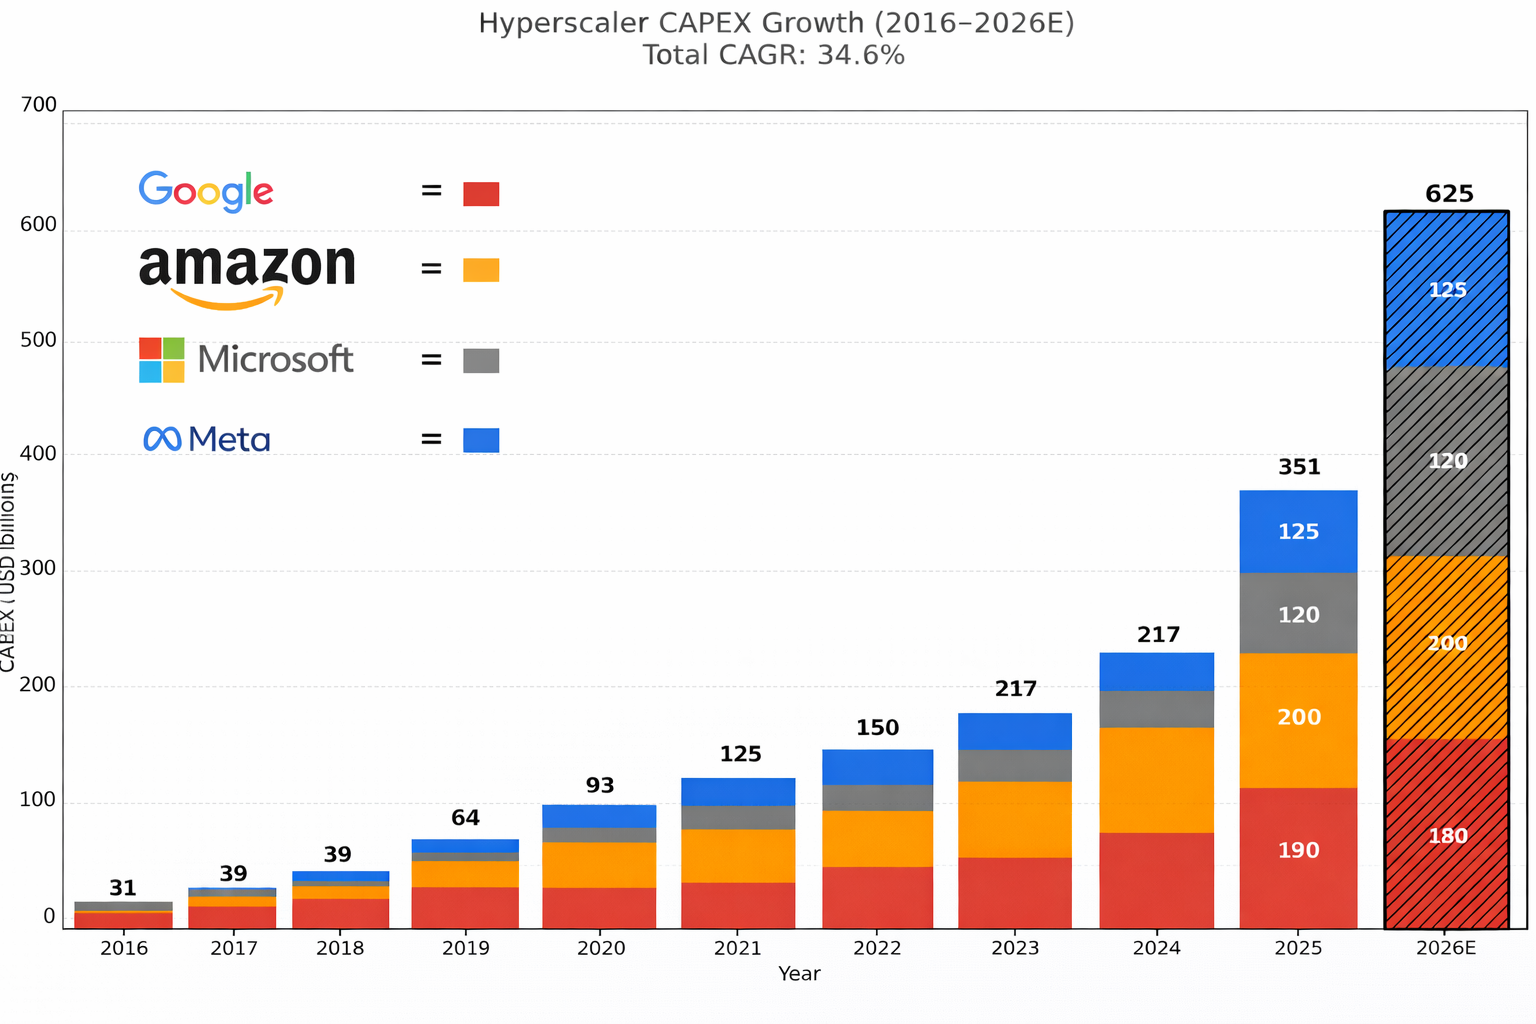
According to management, the high CapEx is not a luxury or a strategic extravagance, but a necessary condition for continuing to meet demand. Sundar Pichai indicated that it is not so much demand growth or productivity gains that concern him, but rather the constraints on the supply side — the factors that determine whether Google can keep delivering sufficient computing power and infrastructure.
Google emphasised that the company was already structurally supply constrained in 2025, despite aggressively scaling up capacity. That persistent tension between supply and demand explains why investment is being accelerated further. Around 60% of CapEx will be spent on machines, including servers and specialised AI hardware, while the remaining 40% will be invested in long-lived infrastructure such as data centres and network facilities. Management does not view this wave of investment as a one-off project, but as a structural part of how the company is run:
"The more capital we can free up within the organization to invest, the better we can turn this flywheel to drive future growth."
This quote sums up precisely what the company's biggest competitive advantage is. Google generates roughly $170 billion in operating cash flow, which is also growing by 10–20% per year. That exceptional financial firepower enables the company to invest to the maximum in compute and infrastructure right now, without being dependent on external financing. For competitors without comparable cash flows, it is becoming increasingly difficult to keep up with this pace of investment structurally. In that light, it makes sense that Google is now deploying its financial strength to build up a substantial lead and further raise the barriers to entry in the market.
Sundar Pichai on SaaS
During the Q&A of the call, a notable question came up about the fear that AI would undermine the seat power and pricing power of large SaaS companies. Sundar Pichai was outspokenly clear in his answer. He said he sees exactly the opposite: Alphabet's strongest SaaS customers, each of them market leaders within their niches, are integrating Gemini deeply into business-critical workflows in order to improve the product experience, accelerate growth and increase operational efficiency. According to Pichai, AI therefore does not function as a substitute that erodes existing software economics, but as an enabling tool that strengthens established business models.
NVIDIA chief executive Jensen Huang also calls the fear that AI would replace the software industry "the most illogical idea in the world". According to him, software products are not an endpoint that will be swept away by AI, but rather the fundamental building blocks on which AI runs and with which it works. A view that fits seamlessly with what we at Tresor Capital have long advocated.
Alphabet is currently trading on the New York Stock Exchange at a price of USD 321.14 per A-share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Margins rise sharply at Addtech despite flat revenue growth
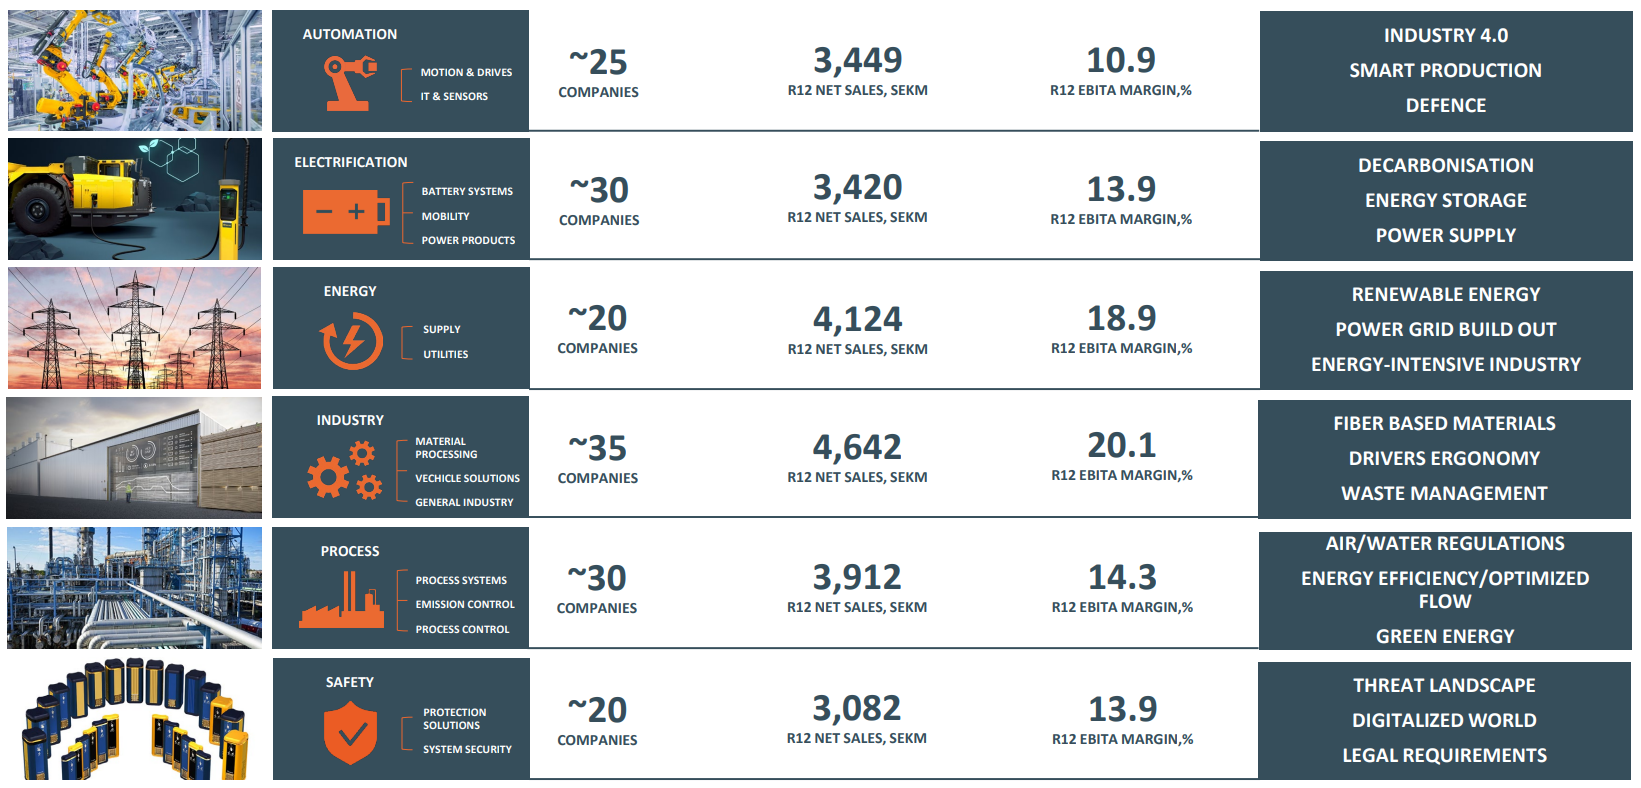
The Swedish serial acquirer Addtech AB (Stockholm: ADDT-B) published its third-quarter results this week. The group operates through roughly 160 highly decentralised niche businesses, spread across six industrial sectors, and has thereby built up a broad and resilient industrial profile. In a macro environment that remains challenging for many Swedish industrial companies, partly due to the persistently strong Swedish krona and reluctance around investment decisions, Addtech managed to further strengthen its operational performance. In doing so, the group once again underlined why it is regarded as one of the qualitatively strongest industrial serial acquirers in Europe.
In the third quarter, revenue rose 1% year-on-year, entirely driven by organic growth, but held back by a negative currency effect of around 3% due to the strong Swedish krona. Management emphasised that this limited top-line growth does not reflect underlying market demand. Order intake remained broadly positive and customer activity high, which, according to CEO Niklas Stenberg, confirms that operational progress is stronger than the reported revenue growth suggests.
The most impressive aspect of this report, however, is operational efficiency. Despite limited revenue growth, Addtech managed to significantly improve its margins. The operating margin climbed to an impressive 15.6%, a significant increase compared with 14.4% in the same quarter last year.
This improvement was driven in particular by two crucial segments:
- Energy: This division delivered the most striking performance. Its margin jumped by no less than 4.9 percentage points, from 15.9% to 20.8%. This underscores Addtech's strong market position within the energy transition.
- Industrial Solutions: As the group's largest revenue driver, this sector once again demonstrated its stability and scale advantage by raising its margin from 19.0% to 20.5%.
According to management, the recent margin improvement is mainly the result of product mix and project timing, and to a much lesser extent of structural price increases. In Energy in particular, it was emphasised that the strong quarterly margin is being driven by a few large, profitable projects with high operating leverage. CEO Niklas Stenberg explicitly warned that this level should not be extrapolated, and that the rolling 12-month margin (18.9%) is a better gauge of future earnings power. Pricing does contribute to margin development, but was described by both the CEO and the CFO as supportive rather than the main explanation. In Industrial Solutions, the margin improvement stems from a combination of scale, favourable mix (including special vehicles and subsea) and contributions from acquisitions, while weaker end markets such as sawmills have been successfully offset.
M&A is and remains the key growth pillar
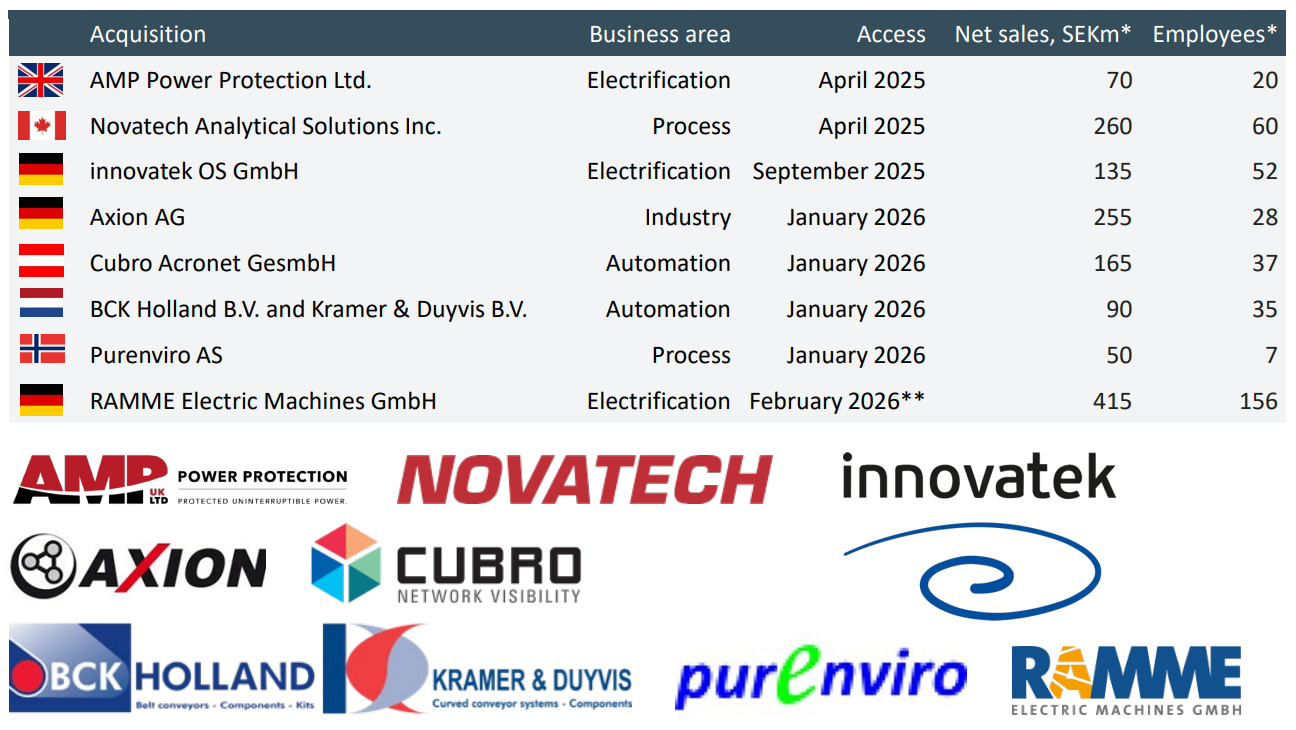
Addtech also kept up a fast pace of acquisitions in the third quarter. In total, eight companies were added this financial year, good for around SEK 1.5 billion in additional revenue. This week also saw the acquisition of Germany's RAMME Electric Machines GmbH, a specialised manufacturer of electric motors for, among other things, maritime applications and industrial electrification.
According to management, RAMME fits seamlessly within Addtech's strategy: a well-positioned niche player with its own products, high added value and attractive margins. During the earnings call, CEO Niklas Stenberg indicated that RAMME's profitability is around 20%, which makes the acquisition immediately earnings-enhancing for the group. Although the transaction is relatively large in Addtech terms, management emphasised that scale in itself is never the starting point; strategic fit, entrepreneurship and culture remain the guiding principles.
Conclusion
Looking ahead, management paints a picture of cautious optimism. Order intake was broadly positive during the quarter, with a book-to-bill ratio above 1 in five of the six business areas. At the same time, Addtech remains alert to continued reluctance around larger investment decisions in parts of the industry, particularly within Automation and Process. Importantly, management is making no attempt to anchor exceptionally strong quarters into fixed expectations. Margins may continue to fluctuate by segment and by quarter, depending on project mix, timing and end markets.
AddTech ended the trading week on the Stockholm stock exchange at a price of SEK 327.00 per share.
Markel Group: 'quality over quantity'
The American insurance holding company Markel Group (New York: MKL) reported strong fourth-quarter results this week. CEO Tom Gayner used the earnings call to candidly admit that the investment portfolio delivered disappointing results in 2025. "In the investing business, at any given moment you always look either smarter or dumber than you actually are. 2025 was a year in which I think we looked dumber than we actually are," said Gayner. However, for those looking beyond one-year results, Markel remains a defensive quality compounder with an extremely strong track record.
Insurance: Combined ratio on track towards the 'low-90s'
Markel's core activity, insurance subsidiary Markel Insurance, showed a clear normalisation of underwriting in 2025. Over the full year, the combined ratio came in at 94.6%, an improvement compared with 95.5% in 2024. This means Markel spends 94.6 cents on claims and operating costs for every dollar of premium income, resulting in an underwriting profit of $456 million over 2025. As the chart shows, Markel is thereby moving back towards the structurally profitable levels of 2021 and 2022.
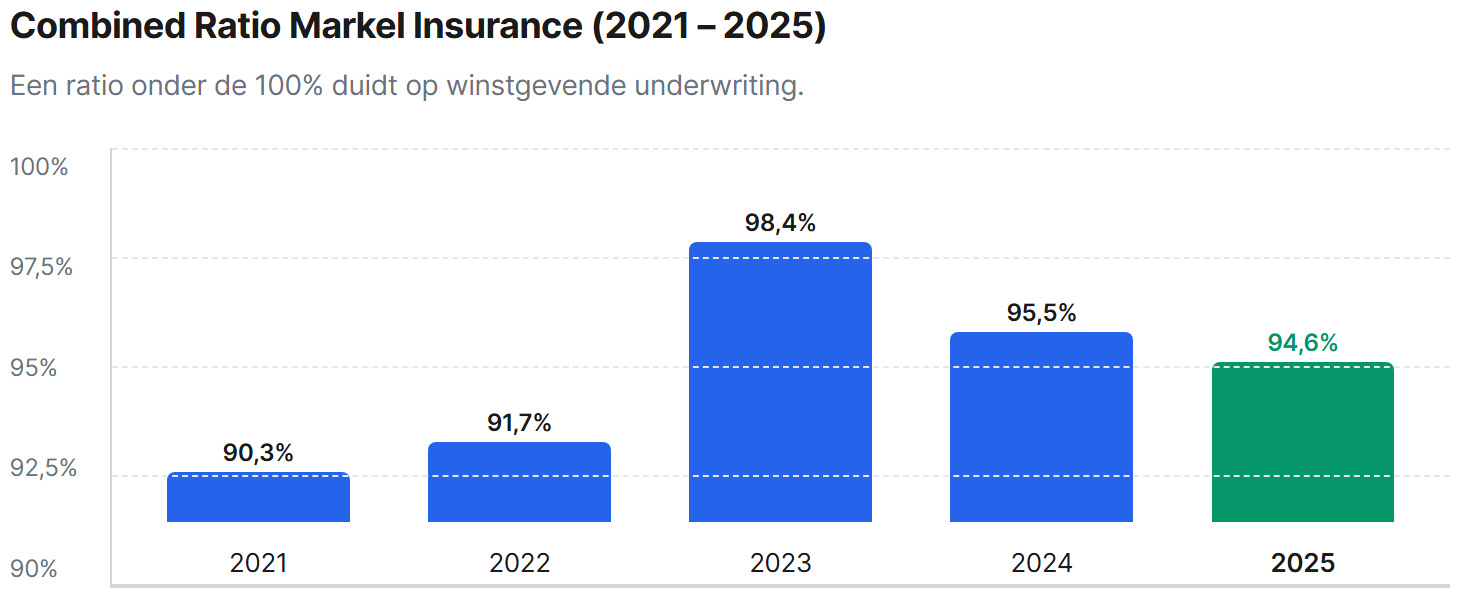
Underlying, the picture nevertheless remains mixed. The International division performed the strongest, with a combined ratio of 83.0%, driven by profitable growth in new markets. Management sees further expansion opportunities here, particularly within professional liability insurance.
By contrast, the Programs & Solutions division came under pressure in Q4, posting a combined ratio of 101.9%, compared with 86.0% a year earlier. The deterioration was primarily the result of substantial losses in the credit and surety line and disappointing results in personal umbrella liability insurance. CEO Simon Wilson indicated that measures have since been taken, including strengthening reserves, tightening pricing and adopting a more selective underwriting policy. According to management, this is sufficient to bring the division back to its targeted profitability in the coming years.
For 2026, the focus is explicitly on sustaining a "low-90s" combined ratio, with management specifically citing a level around 93% as its internal ambition. According to Wilson, this is achievable through further portfolio shifts towards activities where Markel demonstrably has a "right to win", combined with stricter selection in more capital-intensive or volatile lines. Markel does not expect structural margin expansion, but emphasises that pricing discipline and selectivity are more important than volume growth.
Investment portfolio: focus on the long term and capital allocation
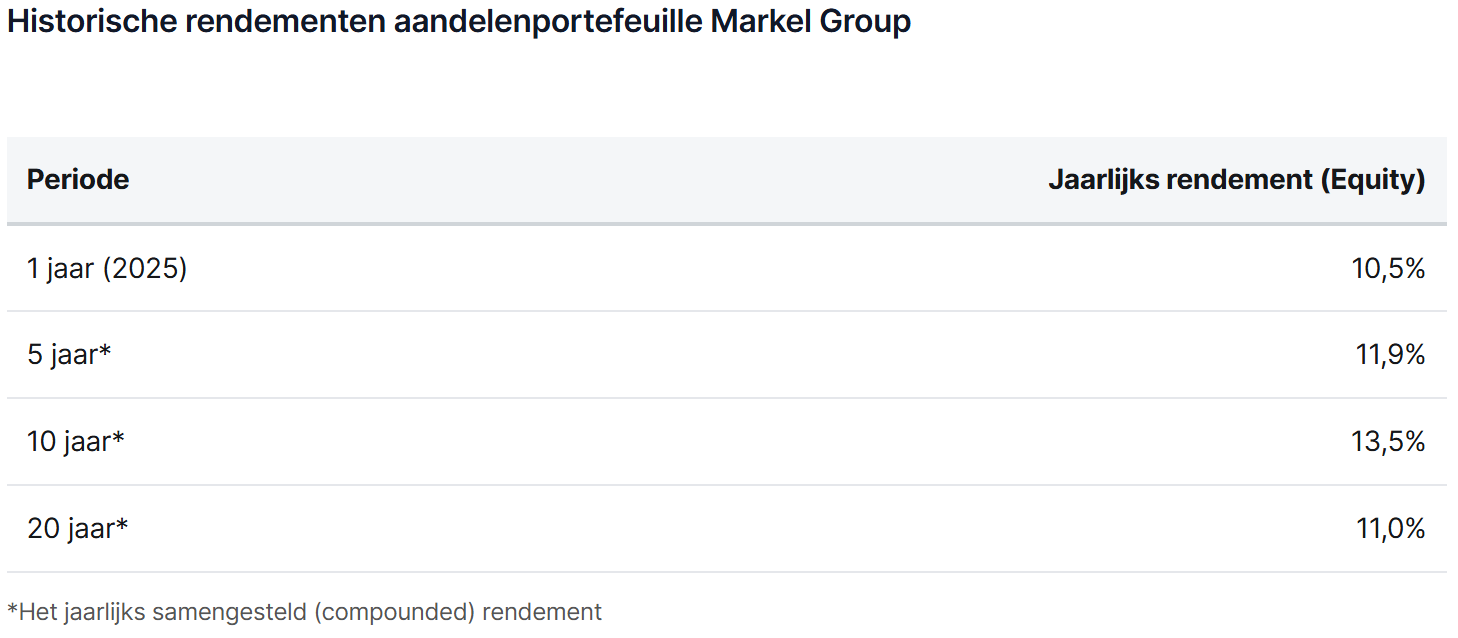
During the 2025 earnings call, CEO Tom Gayner emphasised that Markel Group's investment strategy remains unchanged in its focus on achieving attractive returns over decades. The equity portfolio delivered a return of 10.5% in 2025, resulting in $156 million in dividend income and a total market value of $13 billion at year-end, of which $8.9 billion represented unrealised gains. In 2025, a further net investment of $143 million was made into the equity portfolio.
Although this return was lower than the 20.1% achieved in 2024, Gayner does not see this as a disappointment, but rather as part of the market's natural volatility. He put the annual results into perspective by pointing to the importance of a long-term view: "In any given year, results can and will be volatile, but over periods of five years and longer, the trend has always been upward. That's the power of long-term compounding." The historical figures confirm this consistency.
Outlook 2026: Quality over growth at Markel Group
In 2026, Markel Group's reported revenue is expected to show a decline of approximately $2 billion in gross written premiums. This is not a sign of contraction, however, but the result of deliberate strategic choices aimed at improving the quality of the portfolio.
- Exit Global Reinsurance: The sale of the renewal rights of the reinsurance division accounts for a reduction of approximately $1 billion.
- Hagerty fronting model: The shift in the partnership with Hagerty to a fronting model (whereby Markel receives a fee instead of retaining the full risk and premium on its balance sheet) explains the remaining $1 billion decrease in gross premiums.
Simon Wilson emphasised that Markel would rather give up market share than compromise on underwriting discipline. Although pricing in certain US property lines is under pressure, the target remains a combined ratio in the low-90s range. Management sees the current market as an opportunity to operate more selectively, doing more of what works and less of what doesn't. Tom Gayner closed the call with the following words:
"By staying true to our values and providing a home for exceptional businesses and leaders, we remain positioned to build shareholder value across generations."
Markel Group is currently trading on the New York Stock Exchange at a price of USD 2,126.35 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted after written permission and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments can fluctuate. Past performance is no guarantee of future results. You may lose (part of) your invested capital. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



