
Family Holdings #8 - The purchases and sales of the holding companies



This week's topics:
After a year in which Scottish Mortgage beat the world index, everything points to a successful 2026. The driving force is its strong position in private markets, with SpaceX as the standout performer. Thanks to strategic revaluations and stakes in private giants such as ByteDance and Stripe, the trust holds substantial latent value. Although the market is speculating on IPOs, the trust is taking a patient approach; the current liquidity in the secondary market allows it to stick to its long-term vision.
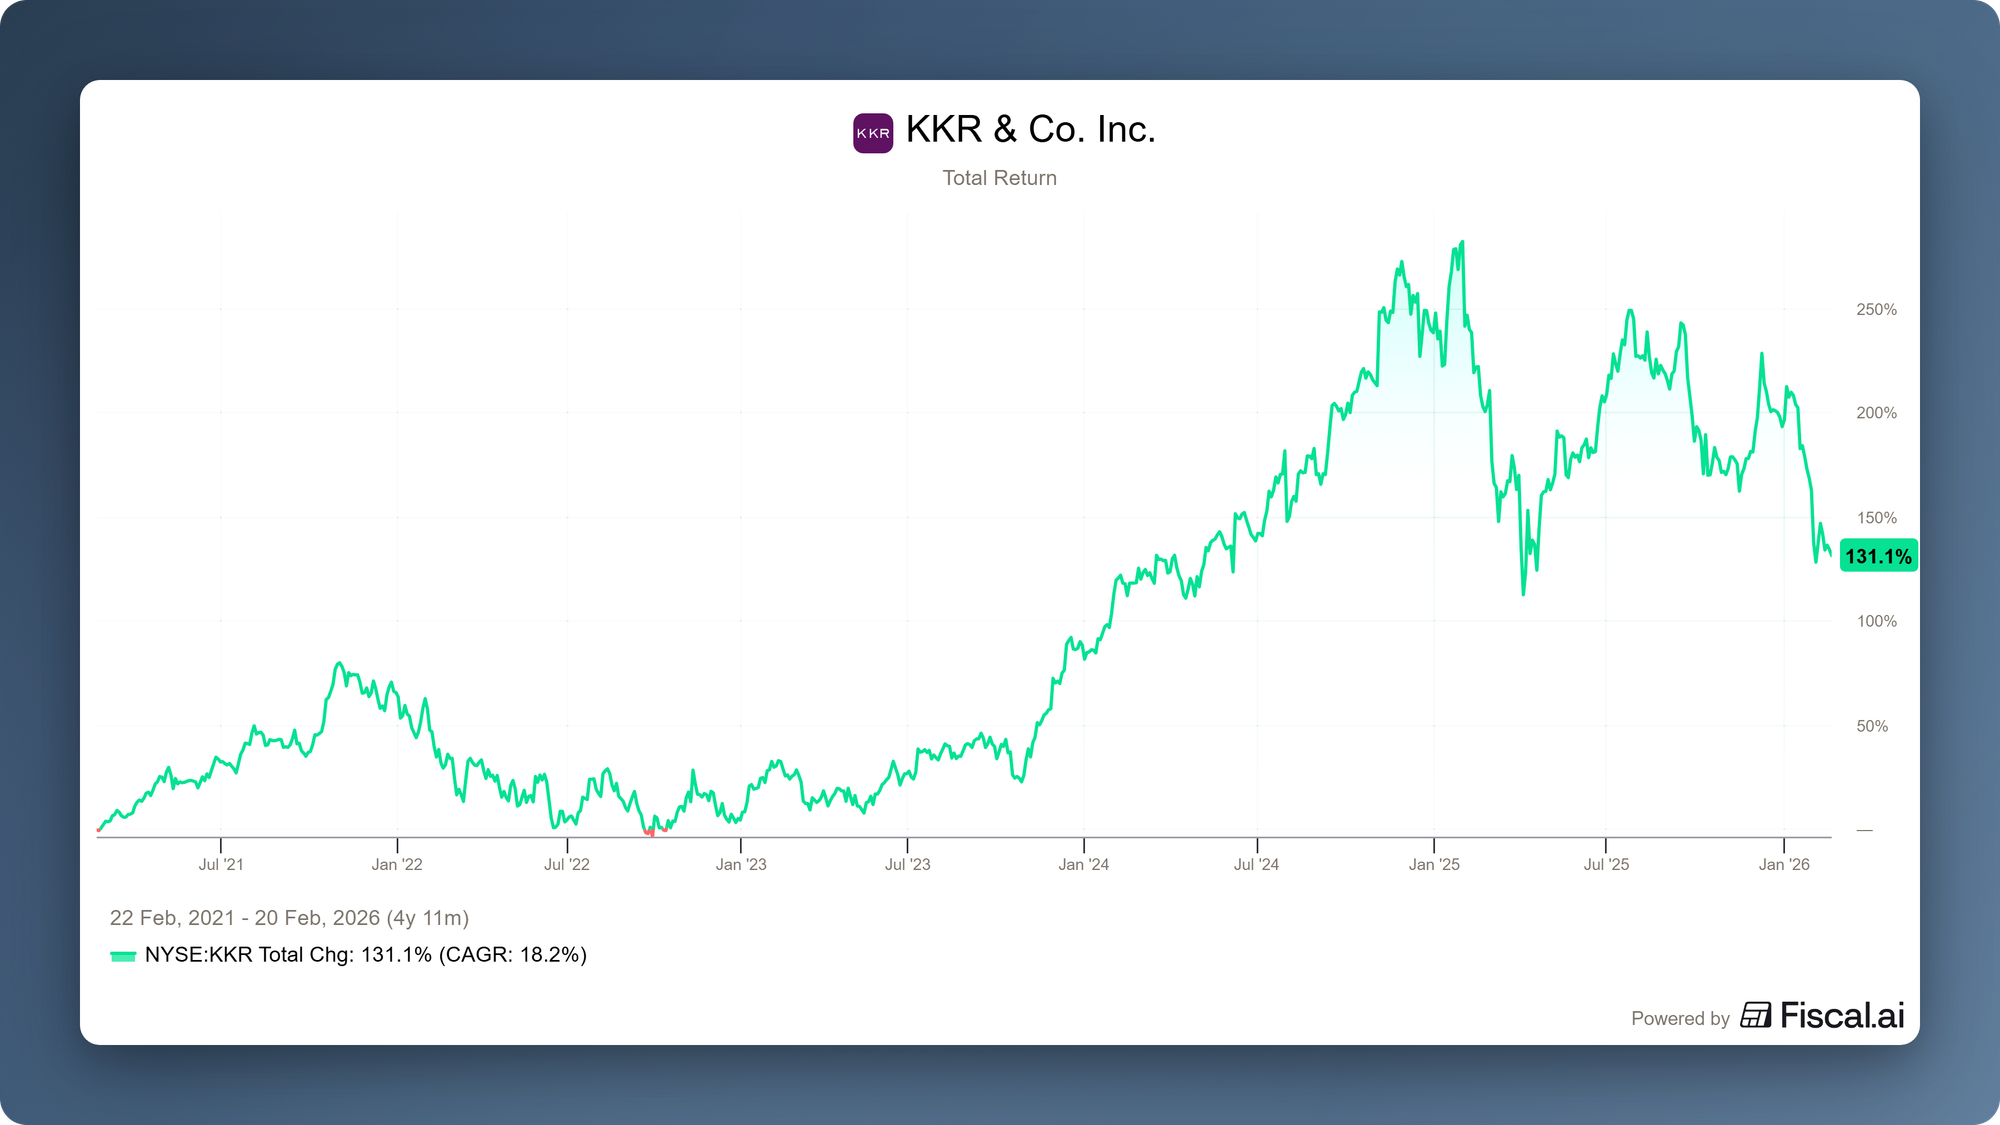
Despite negative sentiment surrounding the sector, insiders at KKR are showing rock-solid confidence. With combined purchases of more than $35 million of their own shares, the Co-CEOs and supervisory directors are sending a clear signal: the market is too pessimistic and the shares have been punished too harshly. For Tresor Capital, this skin in the game is a crucial confirmation that the interests of management and shareholders are aligned.
The Swedish holding company Investor AB continues to impress, as the underlying operating profit (EBITA) of its portfolio companies has risen by no less than 113% over the past five years. While the market worries about the impact of AI on financial valuations, Investor sees the share price declines at holdings such as Nasdaq Inc. and EQT as a buying opportunity and is aggressively expanding its stakes. This active capital allocation, combined with strategic private expansions such as in the medical sector (Vectura), underscores why the traditional undervaluation of the holding company is steadily diminishing.
Berkshire Hathaway’s recent 13F filing shows that the portfolio is gradually shifting. The stake in Apple was further reduced and Amazon was cut significantly, while a modest position in The New York Times was built up. At the same time, energy subsidiary PacifiCorp is selling assets to limit financial risks, pointing to an initial cleanup of the portfolio and a rapidly growing cash position.
In Brief:
Constellation Software's (Toronto: CSU) Lumine expanded its telecom software portfolio with the acquisition of Synchronoss for $9 per share, valuing the enterprise at approximately $258 million, equivalent to roughly 5× expected 2025 EBITDA. Synchronoss provides cloud and messaging services to global Tier-1 operators such as Verizon, AT&T and SoftBank and employs around 750 people.
Danaher (New York: DHR) announced its largest acquisition in more than five years with the takeover of Masimo for $180 per share, totalling approximately $9.9 billion in cash, a 38% premium over the last closing price. Masimo is a leading manufacturer of pulse oximeters and is involved in an ongoing patent dispute with Apple over the Apple Watch. The transaction is expected to close in the second half of 2026, subject to customary approvals.
Brown & Brown (New York: BRO) has acquired the assets of American Adventure Insurance, a niche insurer offering dealer-based insurance solutions for, among others, campers, boats, motorcycles and recreational vehicles.
Prosus Ventures (Amsterdam: PRX) expanded its AI portfolio with two new deals. It invested $5 million in Qureos, a platform that automates the entire recruitment process, from sourcing to interviews, and is now used by more than 1,000 organisations. In addition, Prosus led the $15.8 million Series A round of BeConfident, Latin America's largest AI learning platform with 3 million users, which offers 24/7 conversation-based learning via WhatsApp and its own app.
Constellation Software, Danaher, Brown & Brown and Prosus are currently trading on the Toronto, New York and Amsterdam exchanges at prices of CAD 2,535.40, USD 211.26, USD 69.56 and EUR 44.12 per share, respectively.
| Share | YTD | 3 years* | 5 years* | 10 years* |
|---|---|---|---|---|
| Constellation Software | -25.7% | -2.4% | 6.9% | 18.2% |
| Danaher | -8.4% | -5.2% | 1.5% | 13.6% |
| Brown & Brown | -12.9% | 3.6% | 10.2% | 26.3% |
| Prosus | -17.1% | 9.6% | -2.2% |
Returns shown in EUR; *The annual compounded return
Asseco Poland focuses on defence and cybersecurity
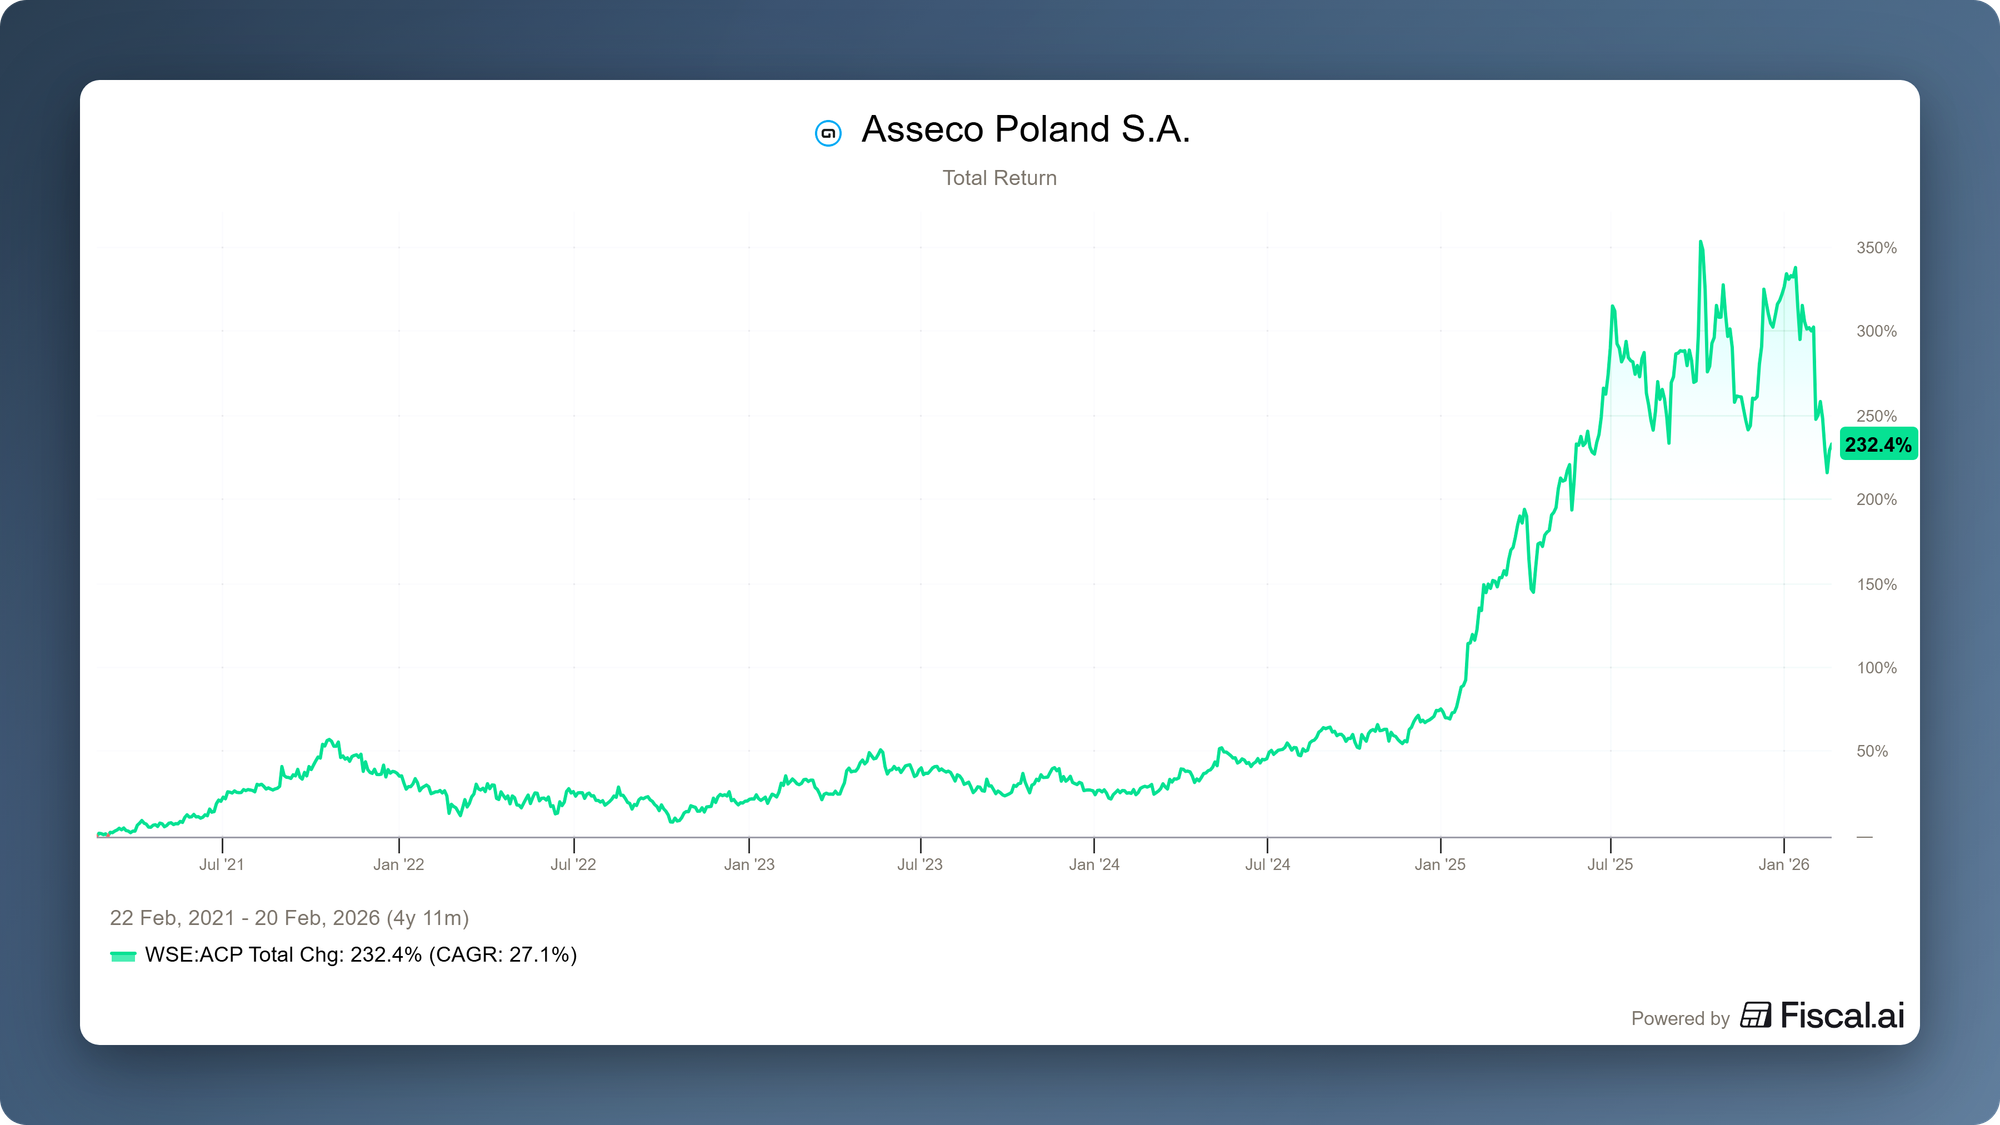
Global geopolitical tensions are rising, and governments are substantially increasing their defence budgets. Against this backdrop, the Polish investment holding company Asseco Poland (Warsaw: ACP) is positioning itself firmly as a crucial player in cybersecurity and national security. The serial acquirer is making strategic use of the deep expertise it has built up in Israel and through contracts with organisations such as NATO and Frontex. For those interested in the full context, this article about Asseco Poland is recommended reading.
 Anna Bełcik - autor artykułu - profil
Vice-president Rafał Kozłowski indicates that the defence sector is highly interesting for the company. Asseco aims to transfer the knowledge gained in the Israeli cybersecurity market to its home market. In Israel, the company provides support for the operation of the Iron Dome defence system through acquired local companies. In Poland, Asseco is currently executing its first defence contracts on a modest scale. The company is considering both organic growth and acquisitions in this sector, specifically looking at the purchase of companies that could enable broader market consolidation in Poland in the future.
The defence market has specific rules for public procurement. In the public sector, the awarding of contracts is determined not only by price and experience, but above all by the degree of trust, organisational maturity and the ability to operate in a highly regulated security environment. Formal and operational factors are crucial, such as handling sensitive information, securing the supply chain, managing access controls and maintaining the readiness to deliver continuous services. This requires a level of operational readiness that smaller players often cannot provide. Large IT players such as Asseco therefore have a significant advantage.

Valuation and long-term outlook
Analyst Adrian Kowollik of East Value Research states that Asseco is one of the strongest companies on the Warsaw stock exchange. He points to the company's strong fundamentals and emphasises that the solutions Asseco provides are business-critical for sectors such as government and healthcare. This creates a high degree of customer loyalty, which also acts as a strong buffer against technological disruption from artificial intelligence.
Kowollik emphasises that Asseco remains attractively valued, despite the sharp share price jump following the announcement of a partnership with Topicus, its largest shareholder. This partnership also provides a catalyst for further improvement in profitability and return on invested capital in the coming years, citing similar examples such as TruBridge and Sygnity. Paweł Łągwa of CMT Advisory notes that 2026 and 2027 are set to be particularly rich in M&A activity in the technology sector.
Asseco Poland is currently trading on the Warsaw stock exchange at PLN 182.80 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
A rock-solid 2025 appears to be the prelude to a successful 2026 for Scottish Mortgage Investment Trust
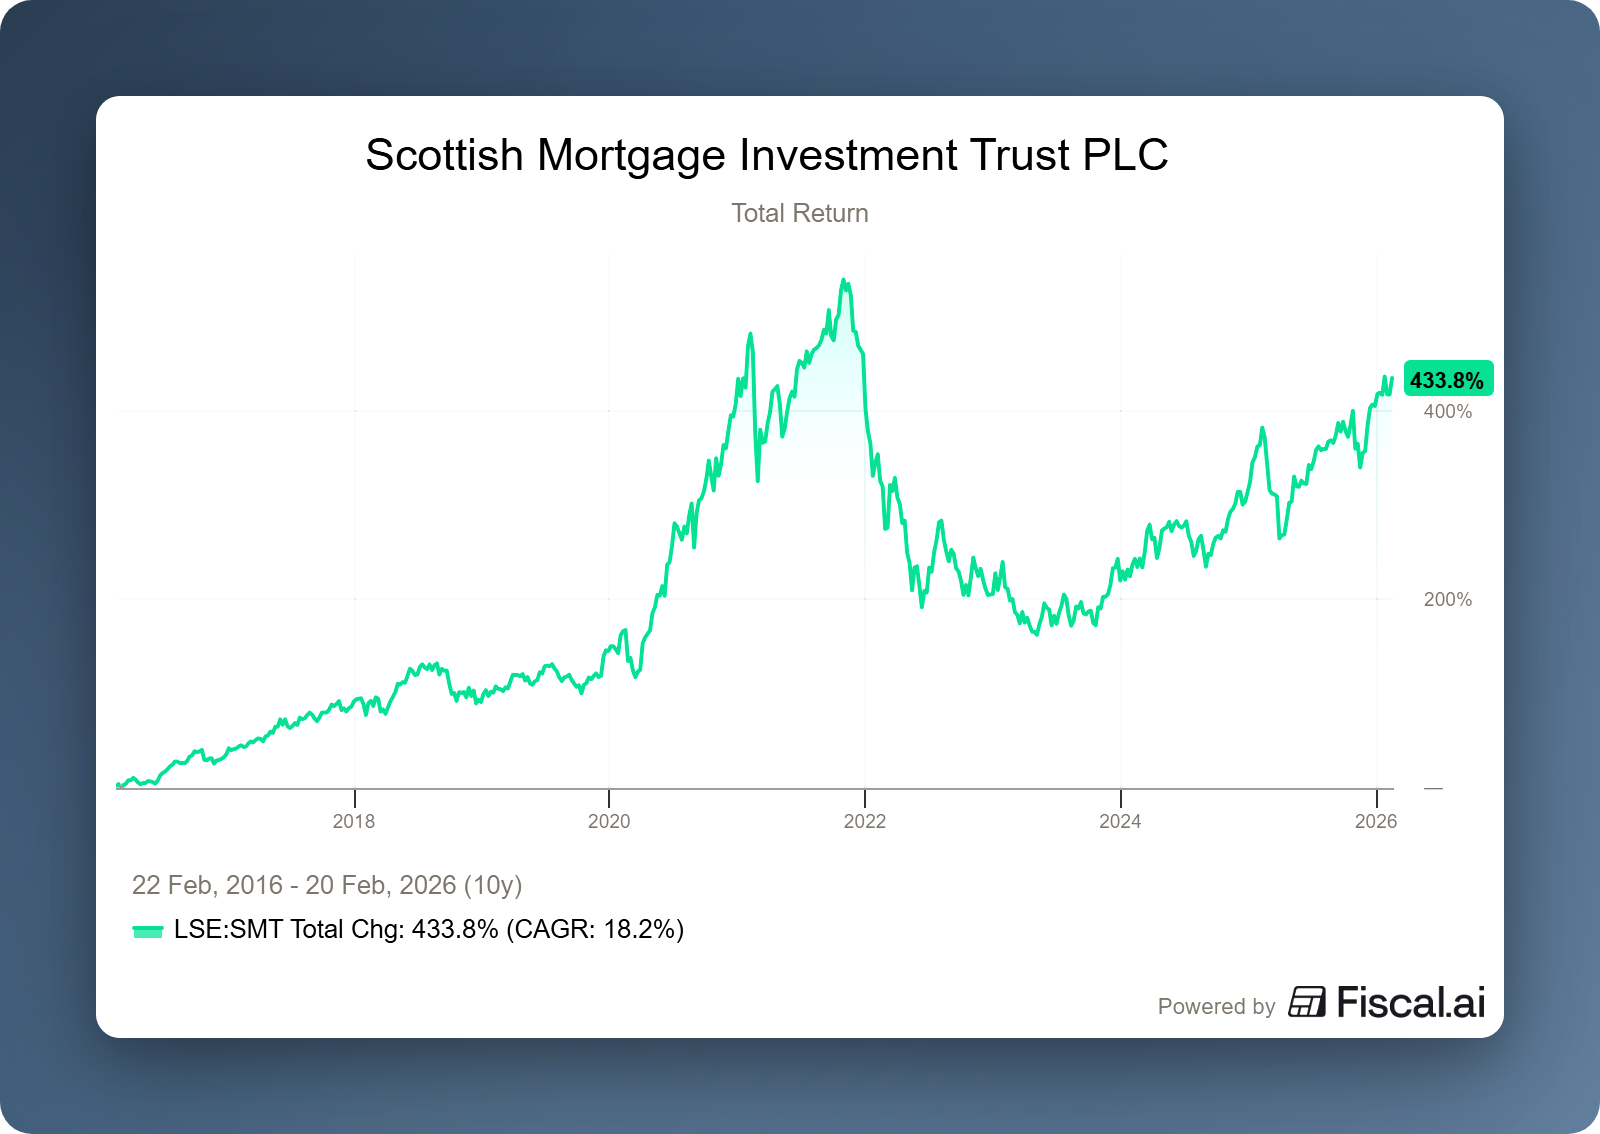
The British investment trust Scottish Mortgage Investment Trust (London: SMT) recently published its results for the fourth quarter of 2025. Over the full year 2025, the trust's net asset value (NAV) rose by 22.3%, while the share price showed an even stronger increase of 24.7%. This means SMT significantly outperformed the broader market; the FTSE All-World Index managed a return of only 14.6% over the same period.

The absolute spearhead of the portfolio is currently SpaceX. Whereas the valuation was still more conservative in the third quarter, the company was revalued in Q4 to an impressive $800 billion. This upward revaluation was the largest single driver of returns in the past quarter, contributing as much as 9.1% in absolute terms to the trust's net asset value (NAV).
It is interesting to note that the recent merger with xAI is already pushing the informal valuation in the secondary market well above $1 trillion. However, this additional 'markup' has not yet been incorporated into the current Q4 figures, pointing to a significant latent reserve for upcoming quarterly updates in the run-up to a potential IPO.
Manager Tom Slater emphasised SMT's unique position in a recent interview. The trust holds stakes in six of the ten largest private companies in the world, including heavyweights such as ByteDance, Anthropic, Databricks, Stripe and Revolut.
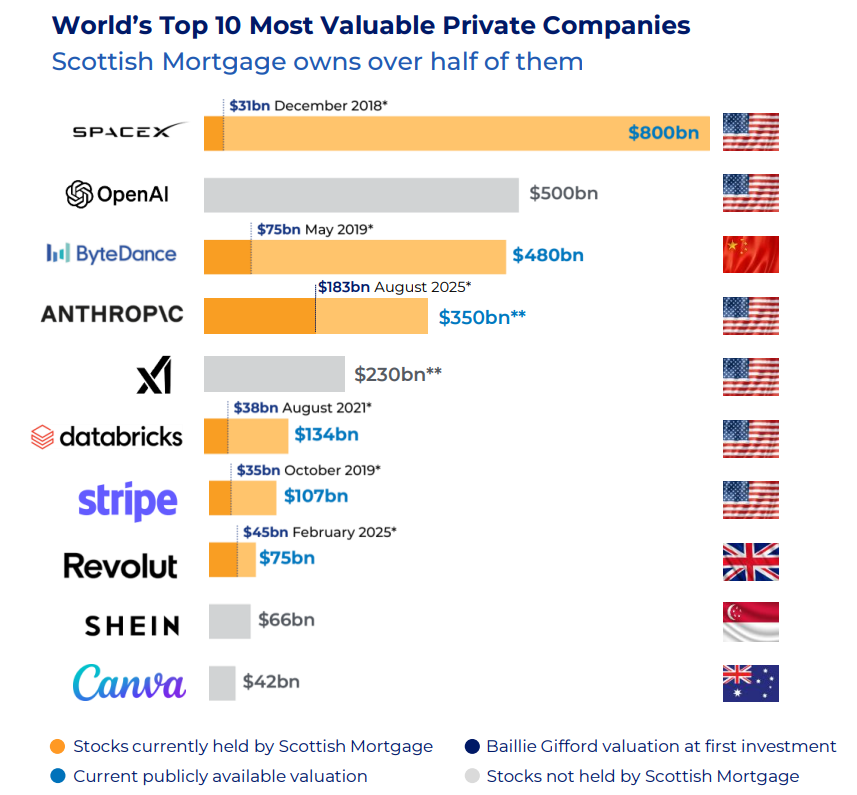
With a private allocation approaching the regulatory limit of 30%, the question arises: should the trust be selling? Slater is clear on this point:
"We are not obliged to sell. We want to maintain the mix of listed and unlisted companies for the sake of tradability, but our philosophy is to hold on to winners for a long time. SpaceX is now a cash-generating company that is highly sought after."
A possible IPO in the region of $1.5 trillion would of course be a great moment to cash in profits, but the secondary market has by now become so liquid that Scottish Mortgage does not need to wait for an official listing to adjust its allocation.
Besides SpaceX, the other five largest private holdings saw their combined valuation rise by a further $400 billion in Q4, resulting in a contribution of roughly 0.8% to NAV in the quarter. Meanwhile, speculation about possible IPOs in 2026 or 2027 for several of these private heavyweights is increasing, although current access to liquid secondary markets also means they can increasingly afford to wait patiently for an official IPO date.
Meet Scottish Mortgage at the VFB Happening
Would you like to discuss Scottish Mortgage's strategy and the dynamic between private and public markets in person? Then put 28 March in your diary. At the VFB Happening, Tresor's Michael Gielkens will take to the stage together with Investment Specialist Hamish Maxwell to share their view on the current market. This is a unique opportunity to gain direct insight into one of the world's most talked-about investment strategies.
Scottish Mortgage Investment Trust is currently trading on the London Stock Exchange at a price of GBP 12.62 per share.
KKR insider transactions point to confidence among senior management
At Tresor Capital, we always talk about skin in the game. We consider it important that our interests and those of our clients as external shareholders are aligned with those of insiders such as executives and supervisory directors. After all, we do not sit at the table in the boardroom, but when key players within an organisation currently have a substantial part of their wealth exposed to the share price performance of the company in question through their ownership of shares, we feel reassured that interests are aligned.
 Michael Gielkens
We have previously written about the pressure on the software and private equity sectors. The American investment holding company KKR has recently come under considerable pressure. Fears around private credit and the underlying software exposure in private portfolios are causing investors to vote with their feet and dump the shares.
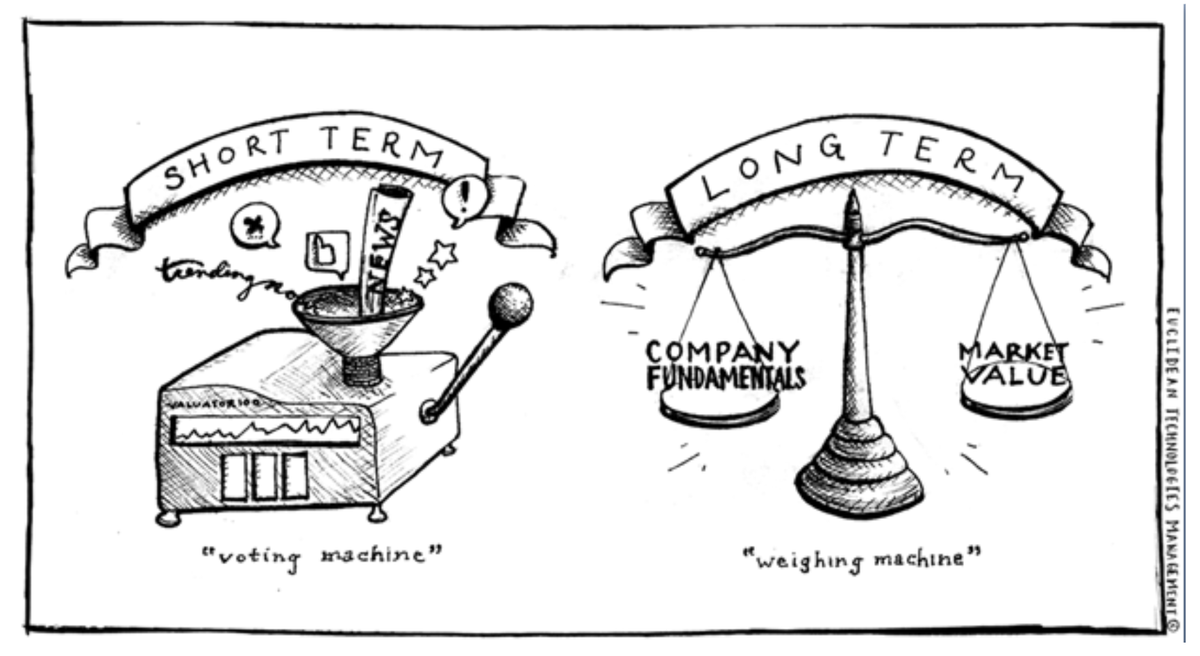
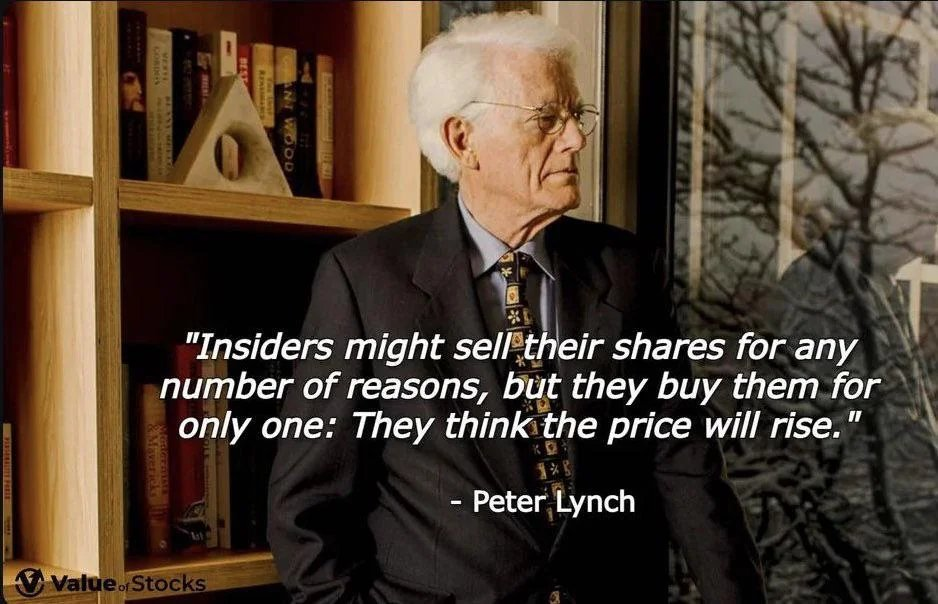
We believe the baby is being thrown out with the bathwater and that investors are overreacting considerably in their sentiment. The fact that insiders share this view was underscored by insider purchases that are rare in their scale. KKR Co-CEOs Joseph Bae and Scott Nuttall each bought shares on the market worth as much as USD 12.8 million with their own money. Supervisory director Matt Cohler also bought shares worth USD 4.5 million. Earlier this month, supervisory director Timothy Barakett also chipped in with a purchase of USD 5.2 million. When insiders buy back over USD 35 million worth of their own shares, this can be seen as a clear signal that the shares have been punished far too harshly. A well-known quote from the legendary investor Peter Lynch goes:
However, not everything in the private equity holding company's portfolio is plain sailing. Sometimes investments fail due to circumstances. For instance, the investment in Accell turned into a flop for KKR. During the pandemic, demand for bicycles surged, prompting manufacturers to respond with enormous orders. However, when supply chains recovered and the bicycles were finally delivered, demand collapsed completely, leaving Accell stuck with large and unsellable inventories. This persistent market malaise, combined with the towering debt load from the initial takeover and the additional costs of a major recall at subsidiary Babboe, ultimately made the financial position untenable.
As a result of the necessary second debt restructuring within a short period, KKR loses control of the company to its creditors, who convert their loans into shares. Although KKR, together with Teslin, still provides a final capital injection of several tens of millions to avert bankruptcy, no ownership remains for the private equity firm in the troubled bicycle giant, which produces bicycles under brands such as Batavus, Sparta and Koga.
KKR is currently trading on the New York Stock Exchange at a price of USD 101.62 per share.
Broad underlying profitability shows the quality of Investor AB
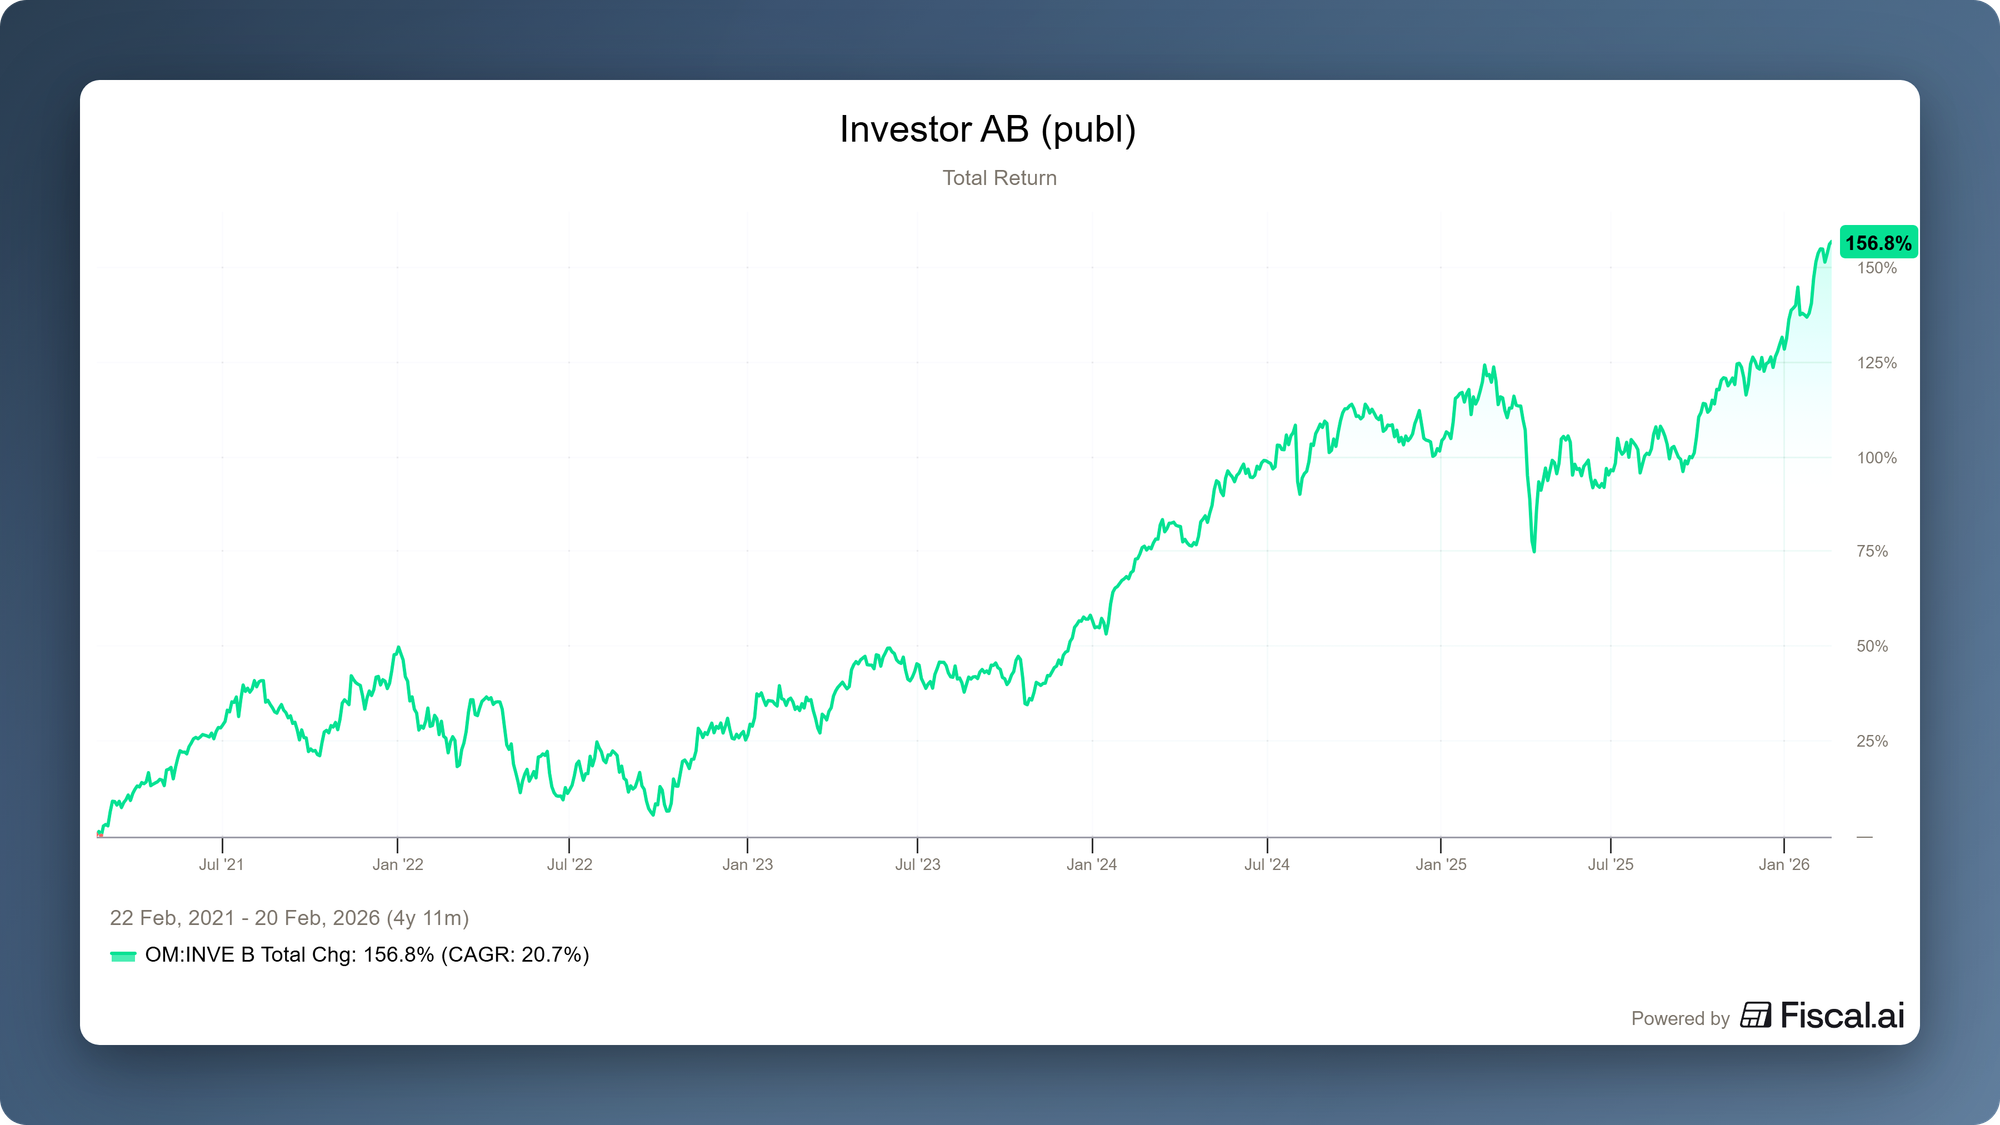
We previously wrote about the excellent annual results of the Swedish investment holding company Investor AB (Stockholm: INVE-B). For the fifteenth year in a row, the Wallenberg family's holding company managed to beat the market. We would like to refer you to the article below for the full report.
 Michael Gielkens
We always read the pieces by Ole Ensrud on his blog Outsiders Corner with interest. This is also true of his most recent analysis of Investor AB's annual results. Ole delves deeper under the bonnet of the companies in the portfolio to calculate what Warren Buffett once called "look-through earnings". This is the profit earned by Investor AB's subsidiaries, multiplied by Investor AB's ownership stake.
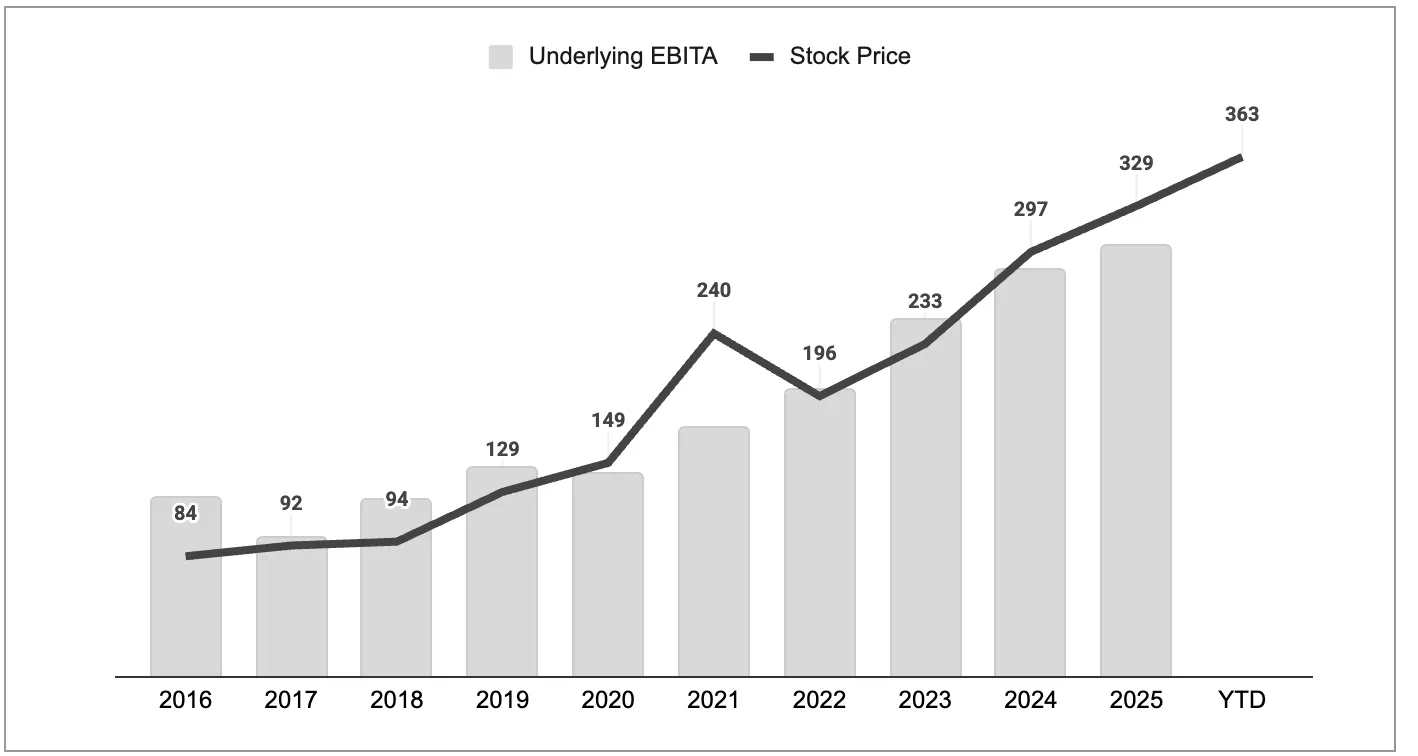
The figure above shows underlying operating profit (bars) plotted against the share price. This shows that fundamental developments are the main driver of share price performance, followed by a modest reduction in the undervaluation relative to intrinsic value. In 2026 too, the undervaluation has been further reduced.
The figure below shows the absolute growth in operating profit over a period of 1, 3 and 5 years. Over a 5-year period, EBITA (gross profit adjusted for amortisation of intangible assets) rose by as much as 113%. The largest contribution to this profit growth came from automation and electrification company ABB, followed by the unlisted portfolio Patricia Industries and bank SEB.
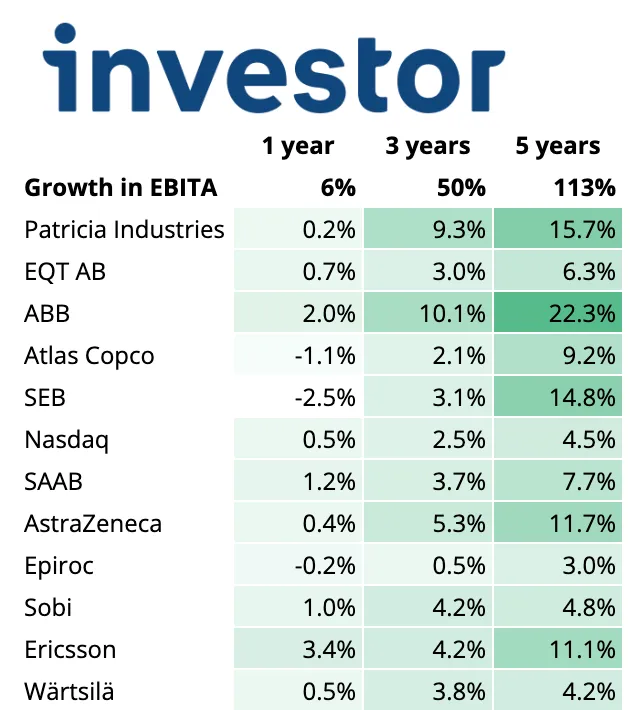
However, Ensrud reveals an even more relevant fact: over both the 3- and 5-year periods, all companies contributed to the growth in operating profit of the family holding company. This supports his view that Investor AB should not trade at a high discount at all, a view we fully endorse.
Capital allocation continues unabated
Investor AB continues to invest without let-up, in both the listed portfolio and the private companies within Patricia Industries. Despite better-than-expected reported figures, the share price of Nasdaq Inc. has already fallen by more than 16% in 2026. Investors are increasingly concerned about the impact of artificial intelligence on traditional financial services providers. The fear is that AI applications will undermine existing business models and put pressure on margins. Investor AB, one of the most forward-thinking holding companies in our investment universe when it comes to future-proofing (read: implementing digitalisation and AI at) its subsidiaries, views this as a buying opportunity rather than a reason for disruption fears. Investor therefore bought additional shares worth USD 15.8 million.
This sentiment did not only affect Nasdaq Inc., but also led to share price losses at other financial institutions. This year, private equity subsidiary EQT AB is also underwater, as investors fear that EQT's software positions will come under pressure from AI. Here too, Investor AB responded in similar fashion: last week the family holding company bought SEK 657 million worth of EQT shares. For an in-depth look at the AI fears gripping the software and private equity sector, we refer you to last week's Deep Dive below.
 Michael Gielkens
In addition, the private portfolio was further reinforced. Vectura, a subsidiary of Patricia Industries, is strengthening its market-leading position by acquiring the remaining ownership interests in GoCo Health Innovation City from Next Step Group. This strategic acquisition of the knowledge-intensive Life Science cluster in Mölndal represents a total property value of up to SEK 2.9 billion and fits seamlessly with parent company Investor AB's capital allocation strategy of supplementing organic growth with high-quality acquisitions. Patricia Industries is supporting this transaction with a targeted capital injection of SEK 0.5 billion. The transaction comprises four buildings with more than 52,000 square metres of floor space and is expected to be completed in the second quarter of 2026.
Investor AB is currently trading on the Stockholm stock exchange at a price of SEK 367.90 per B share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Buffett's last dance
Once every quarter, large institutional investors are required to lay their cards on the table by means of the 13F filing. This document offers a glimpse into the portfolios of some of the world's most respected asset managers. For investors, the update from Berkshire Hathaway (New York: BRK-B) is always something of a holy grail.
Although Warren Buffett has indicated on several occasions that he has for some time now been less active operationally, this gives us one final chance to feature his name in a title once more.
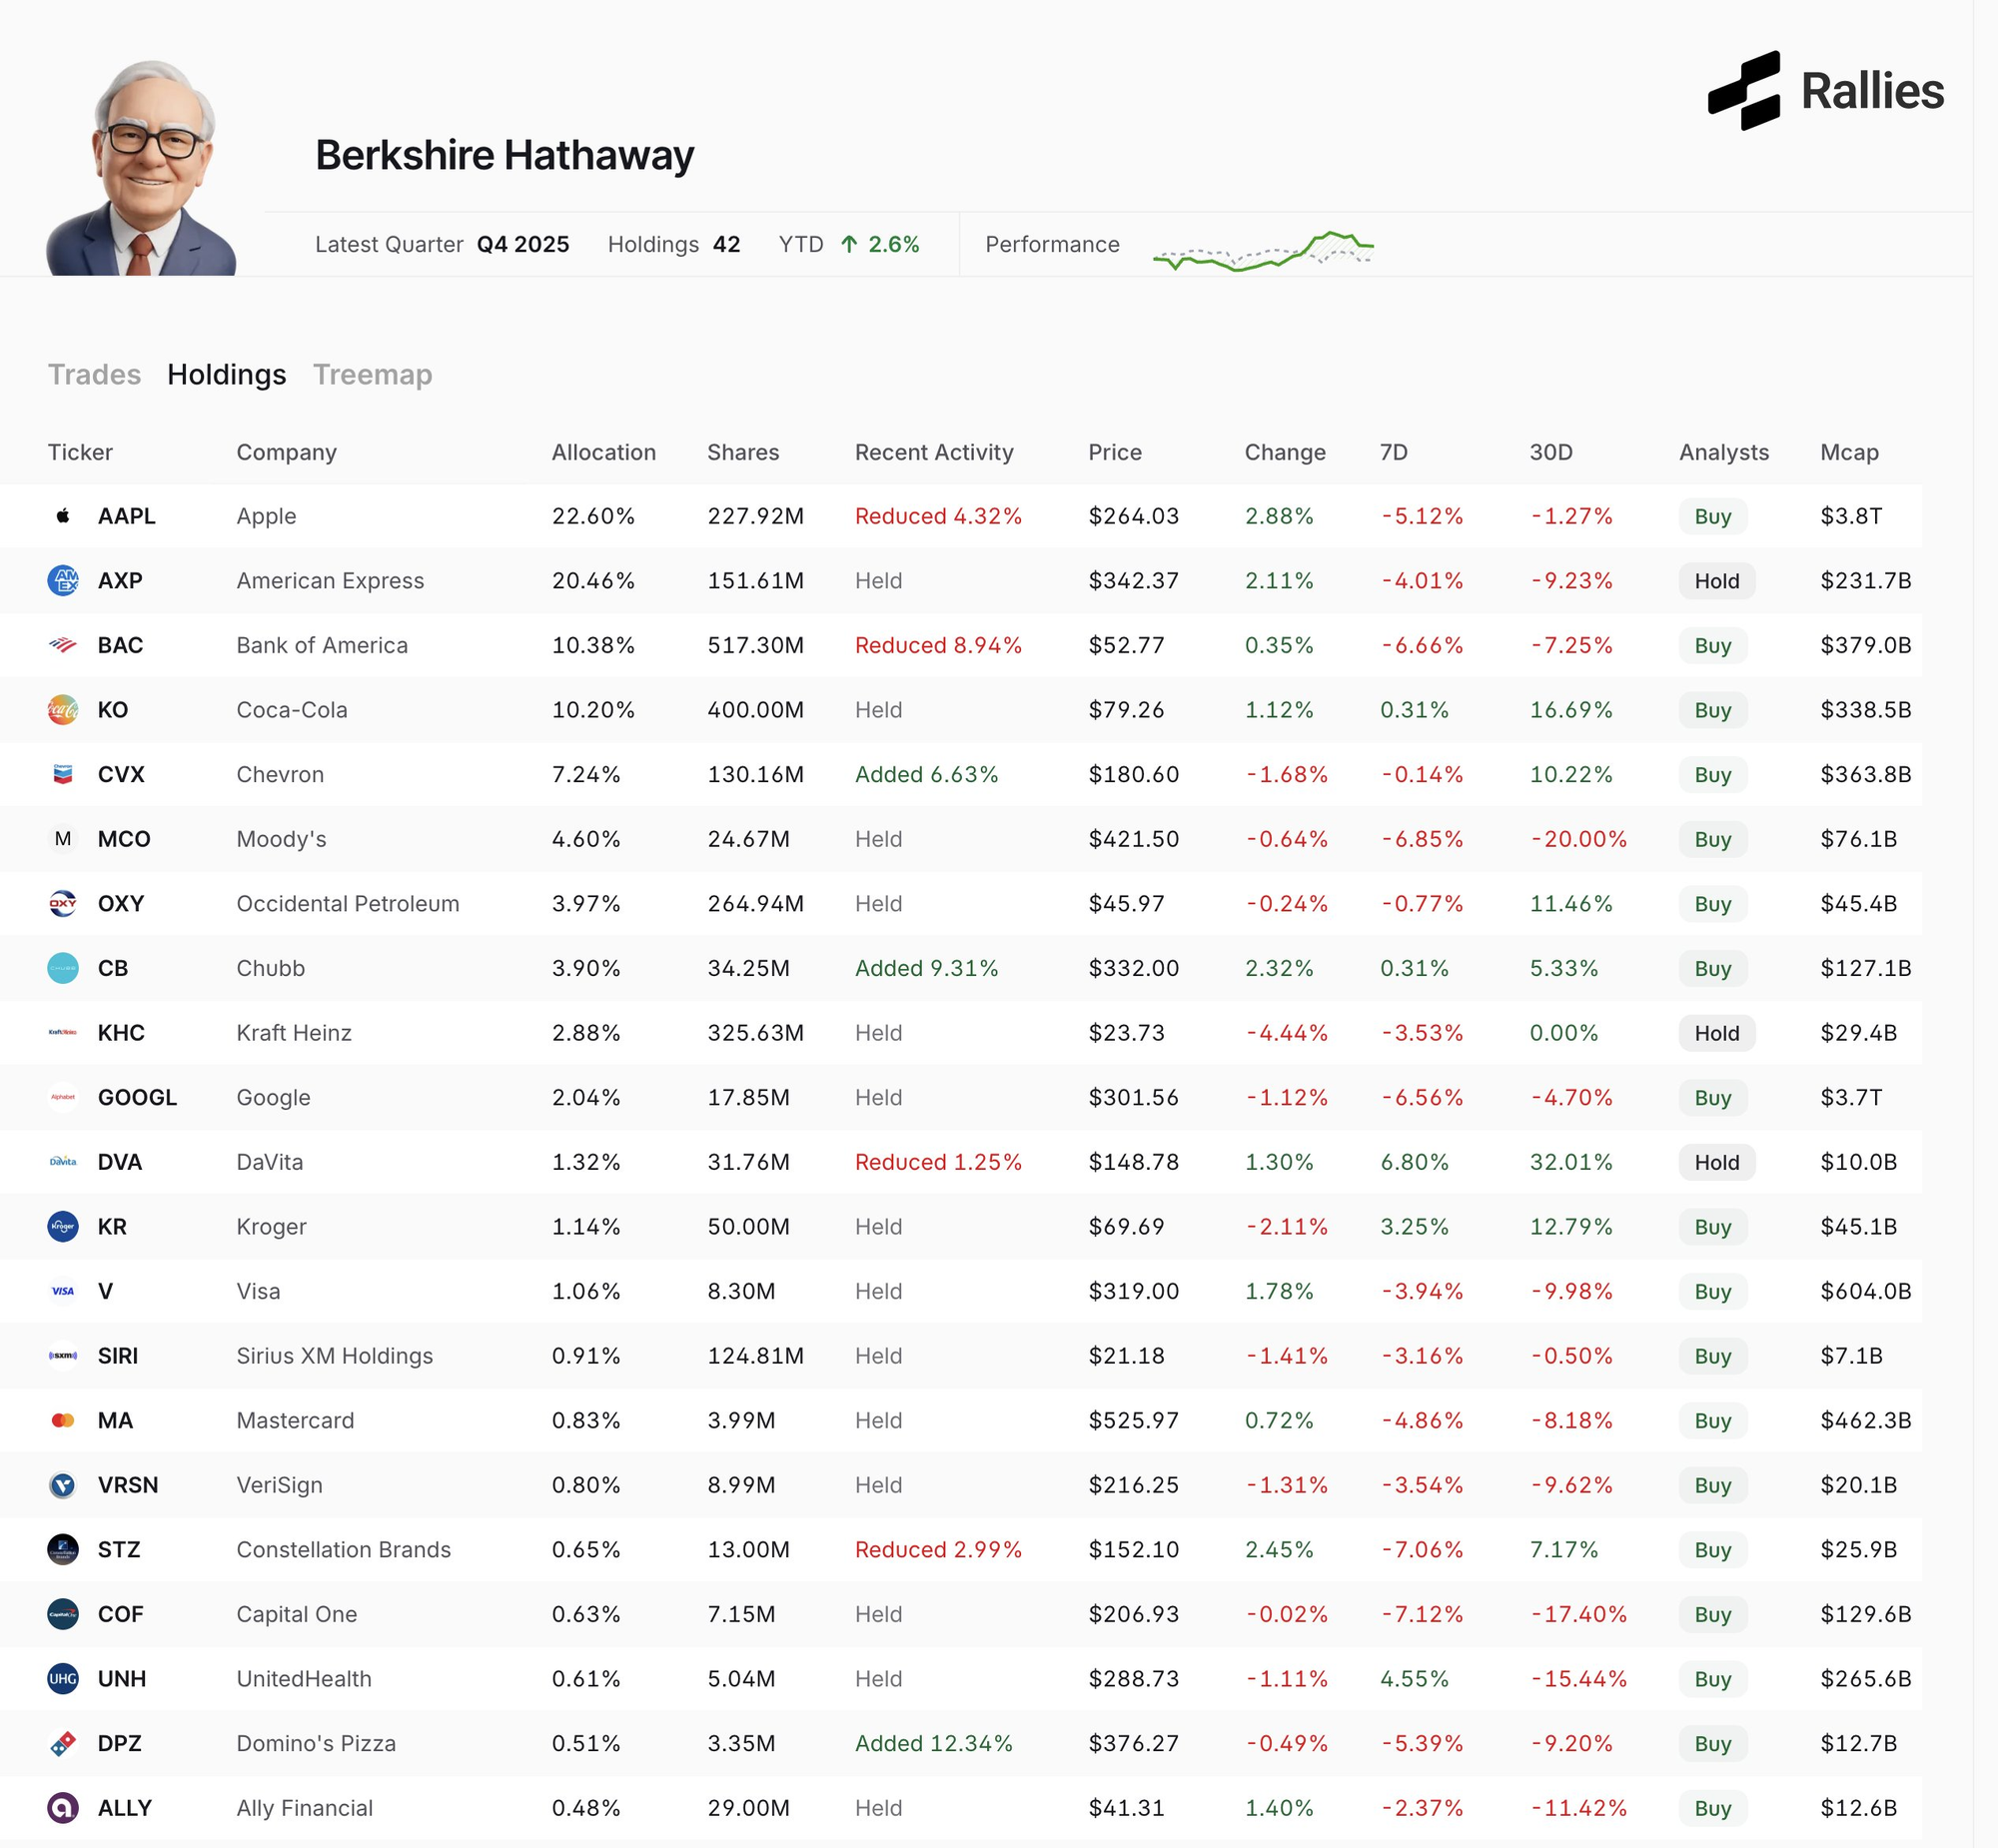
The most notable changes in the portfolio at a glance:
- Berkshire has further trimmed its stake in the iPhone maker by 4.3%, bringing the position to a value of $61.96 billion. Although Apple remains by far the largest holding at roughly 22%, the trend is downward. Following the heavy waves of selling in 2024 and the first half of 2025, Berkshire continues to steadily take profits.
- More striking is the move on Amazon. Berkshire slashed its position in the e-commerce and cloud giant by more than 75%. Buffett first bought the stock in 2019 and readily admitted at the time that he had been an "idiot" for not getting in sooner. The current sale, which leaves just 2.3 million shares remaining, appears to be part of a broader move away from the volatile technology sector. It is possible, however, that this was originally a purchase by portfolio manager Todd Combs. Since Combs has since left Berkshire, it would make sense for some of his positions to be unwound as well.
- Perhaps the most interesting move is the investment of more than $350 million in The New York Times. Although at 0.12% of the portfolio it is a relatively modest position, it marks the first time in years that Berkshire Hathaway has directed fresh capital towards journalism. Buffett has always preached that in the digital age only three newspapers in the US would remain viable: The Washington Post, The New York Times and The Wall Street Journal. Now that the 'Post' has been in the hands of Jeff Bezos for quite some time, Berkshire is choosing, with this position, to take a stake in one of the other remaining strong brands.
A sale within Berkshire's energy division
In addition to the shifts in its equity portfolio, Berkshire Hathaway is also taking an unusual step within its energy division. Subsidiary PacifiCorp has agreed to sell a significant portion of its assets in the state of Washington to Portland General Electric for approximately $1.9 billion. The package includes wind farms, transmission lines and a natural gas plant.
The fact that Berkshire is divesting assets is remarkable. For decades under Warren Buffett, the philosophy was to hold businesses and infrastructure “forever,” even when returns were temporarily under pressure. The sale should therefore be seen in the light of the billions in claims facing PacifiCorp following devastating wildfires in Oregon and California, which are undermining the division's financial stability.
Buffett warned two years ago that he would “not knowingly throw good money after bad.” Greg Abel, who earned his stripes within Berkshire's energy division, now appears to be turning those words into policy. His start as CEO is thus marked by a first, visible cleanup of the portfolio.
At the same time, this raises questions about where the resulting cash will be directed. The winding down of the Apple stake and now this energy sale are further swelling the cash position. The new stake in The New York Times is strategically interesting, but remains marginal relative to the size of Berkshire's balance sheet. It therefore seems not unlikely that Greg Abel will look for a large private acquisition in 2026 or, should attractive opportunities fail to materialise, fall back on substantial share buybacks.
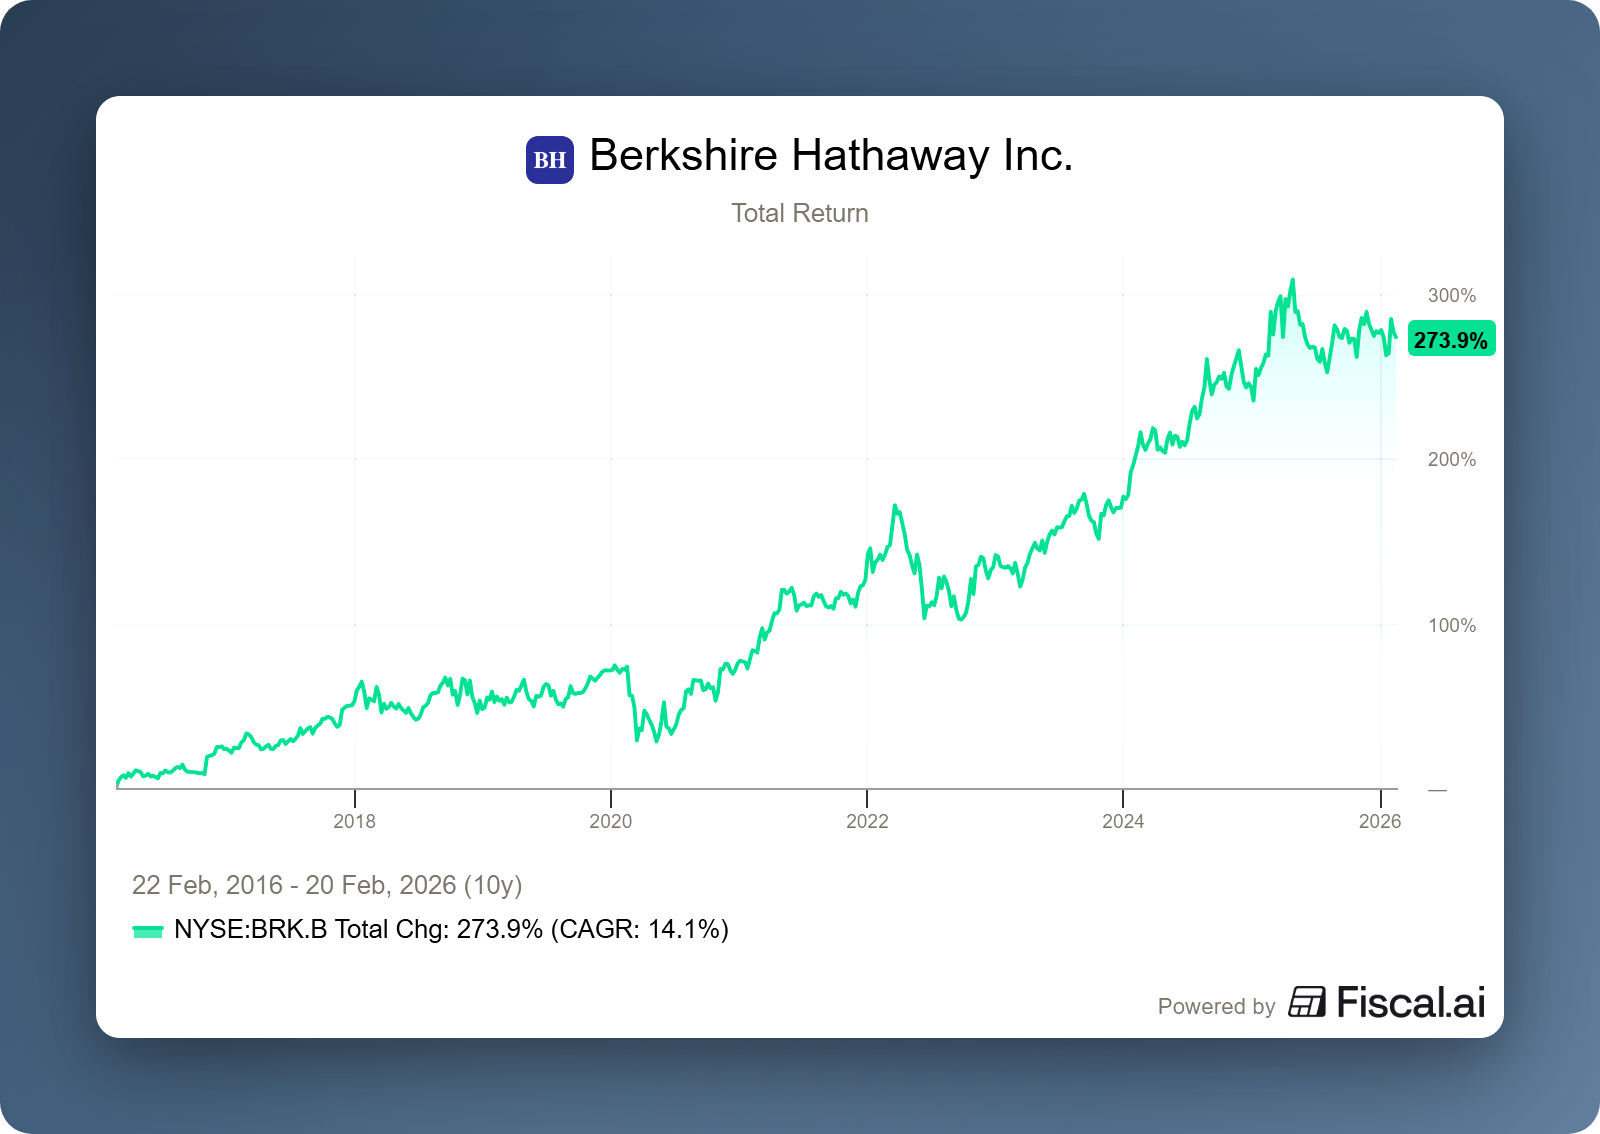
Berkshire Hathaway is currently trading on the New York Stock Exchange at a price of USD 493.68 per B-share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or on behalf of their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your initial investment. Tresor Capital disclaims any liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



