
Family Holdings #9 - Navigating a Nervous Market with a Long-Term Focus



This week's topics:
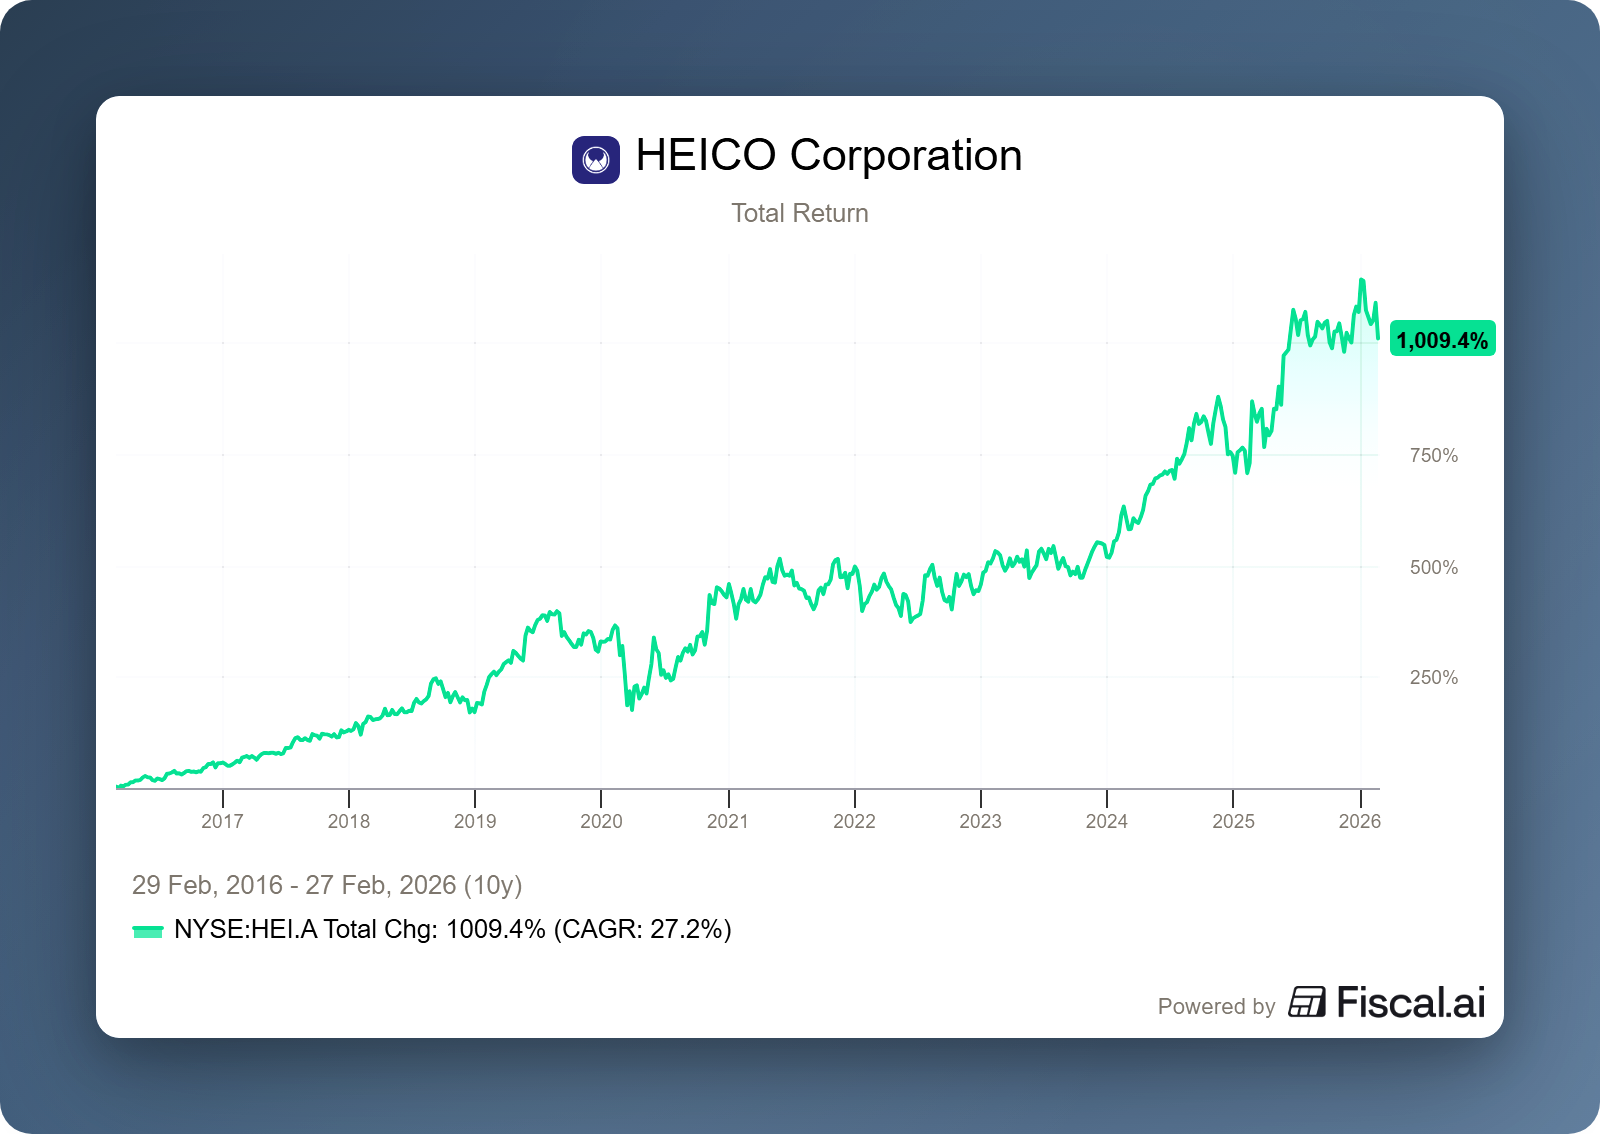
Heico saw revenue rise 14% to USD 1.18 billion in the first quarter of FY2026, with earnings per share of USD 1.35 comfortably beating market expectations. The intraday share price drop of more than 10% was caused by lower operating cash flow due to pension payouts and margin pressure at the ETG division, factors that management describes as one-off and cash-neutral in nature. With a record order book, a healthy balance sheet and a debt ratio of 1.79x operating profit, the company remains focused on organic growth and disciplined acquisitions within the aviation and defence sector.
Brookfield CEO Bruce Flatt is playing down fears of contagion from the private credit market, pointing to the limited size of problem sectors and the fragmented nature of this niche. Brookfield is investing heavily in AI infrastructure as the new backbone of the economy and estimates the global capital requirement for this at USD 7 trillion. To manage the risk of overcapacity, the holding company uses a model in which construction projects and the leasing of AI computing capacity are agreed in advance through long-term contracts with creditworthy counterparties.
Markel Group CEO Tom Gayner recently gave a rare in-depth interview to In Practise on capital allocation, the company's internal workings and his vision for the future. Gayner describes Markel as a company deliberately built to create ever more allocation freedom over time, with Berkshire Hathaway as an explicit roadmap, only earlier in the curve. He speaks candidly about the concentration in his equity portfolio, the wind-down of the loss-making reinsurance operations, and the recent organisational changes as early signs of a simplified and more sharply focused Markel. You can read the full interview at the bottom of this newsletter.
In Brief:
Asseco Poland (Warsaw: ACP) founder and chairman Adam Góral has used the recent share price decline to increase his stake. Through his family fund, a total of 82,500 shares were bought on 20 and 23 February for approximately PLN 15 million (around €3.55 million). The purchase underscores the founder's confidence in the company's long-term prospects.
Both Sofina (Brussels: SOF) and Scottish Mortgage Investment Trust (London: SMT) are benefiting from a substantial revaluation of ByteDance, the parent company of TikTok. A planned secondary sale by General Atlantic implies a valuation of $550 billion, well above previous transactions ($480 billion in November and $330 billion at last year's buyback). The rising private market valuation supports the intrinsic value of both investment holding companies.
Sofina also remains active within the ecosystem. Brussels-based Syndicate One closed a second fund of €22 million, with Sofina as a returning anchor investor. The fund supports early-stage Belgian tech startups and continues to build a compounding network of entrepreneurs and investors, further deepening Sofina's exposure to growth companies in Europe.
Alphabet (New York: GOOGL) is taking further steps in the commercialisation of its AI infrastructure. According to Reuters, Meta Platforms signed a multi-year, multi-billion-dollar agreement to lease Google's Tensor Processing Units (TPUs) for the development of new AI models. This positions Google's own chips firmly as an alternative to Nvidia, and TPU leasing is growing into an important driver within Google Cloud. In addition, robotics software company Intrinsic, which originated from Alphabet's Other Bets X division, is being fully integrated into Google. The Flowstate platform, which makes industrial robots easier to programme, will work more closely with Gemini and Google DeepMind.
Asseco Poland, Sofina, Scottish Mortgage Trust and Alphabet are currently trading on the Toronto, New York and Amsterdam exchanges at prices of PLN 179.50, EUR 252.60, GBP 12.40 and USD 308.12 per Class A share, respectively.
| Share | YTD | 3 years* | 5 years* | 10 years* |
|---|---|---|---|---|
| Asseco Poland | -21.5% | 41.5% | 28.6% | 17.9% |
| Sofina | 1.6% | 4.5% | -0.7% | 11.6% |
| Scottish Mortgage Trust | 3.8% | 21.3% | 2.0% | 16.8% |
| Alphabet | -2.1% | 45.8% | 25.8% | 23.0 |
Returns shown in EUR; *The annual compounded return
Strong Q4 for Topicus, AI heavyweights provide support for software
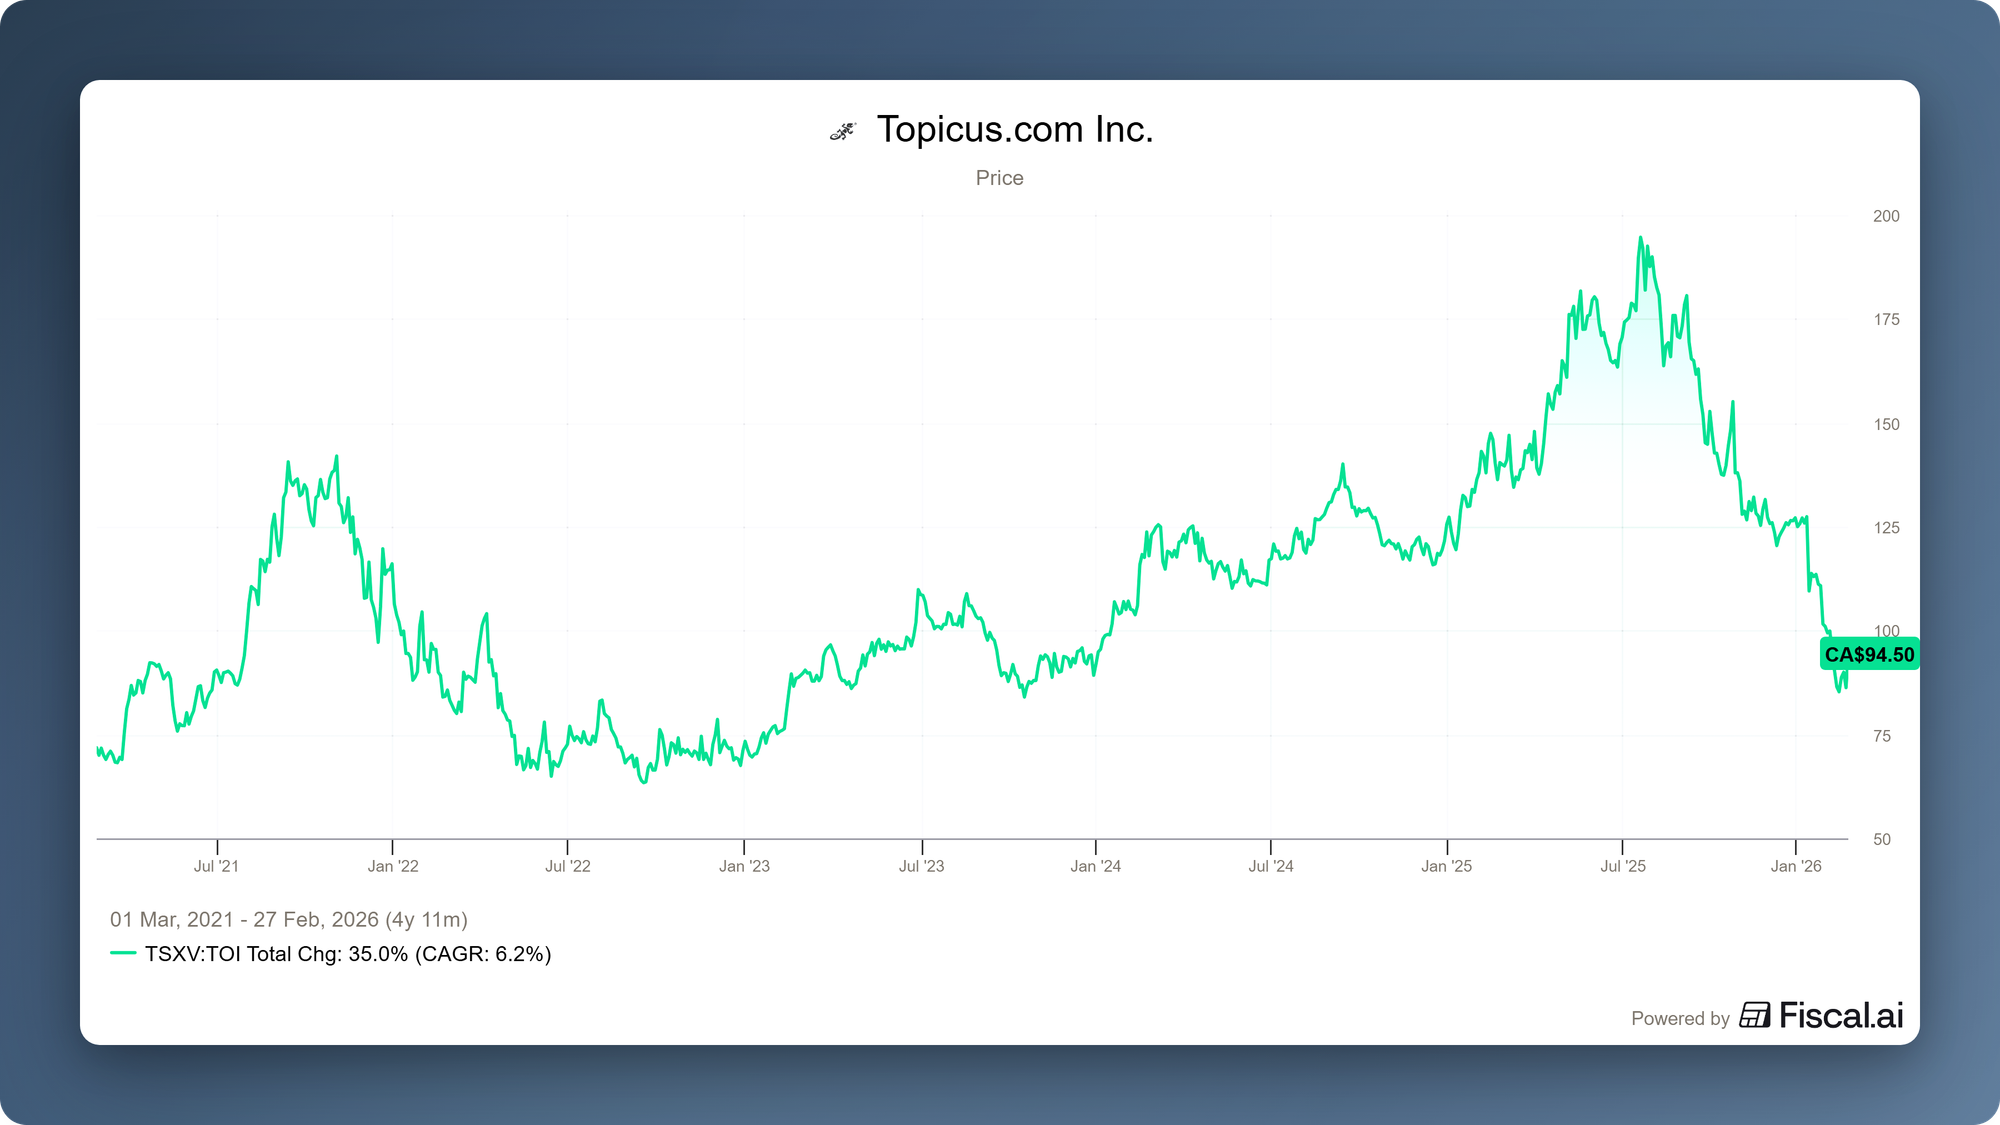
This week, the Dutch investment holding company Topicus.com (Toronto: TOI) published its results for the fourth quarter of 2025. While the share price is under pressure due to investors' AI-related fears, the company continues to perform at a high level operationally.
In the fourth quarter, Topicus's revenue grew by 20% to EUR 436.8 million, of which 4 percentage points was organic growth. The most important revenue component, recurring maintenance revenue, showed strong organic growth of 6%. Operating cash flow (CFO) rose by 35% to EUR 107.7 million. "Free cash flow available to shareholders (FCFA2S)" — that is, the cash flow freely available for distribution to shareholders — increased by 40% to EUR 51.2 million.
For 2025 as a whole, we can speak of an operationally excellent year. Revenue rose by 20% to EUR 1.55 billion, while operating cash flow increased by 19% to EUR 412.7 million and FCFA2S grew by 23% to EUR 218.7 million.
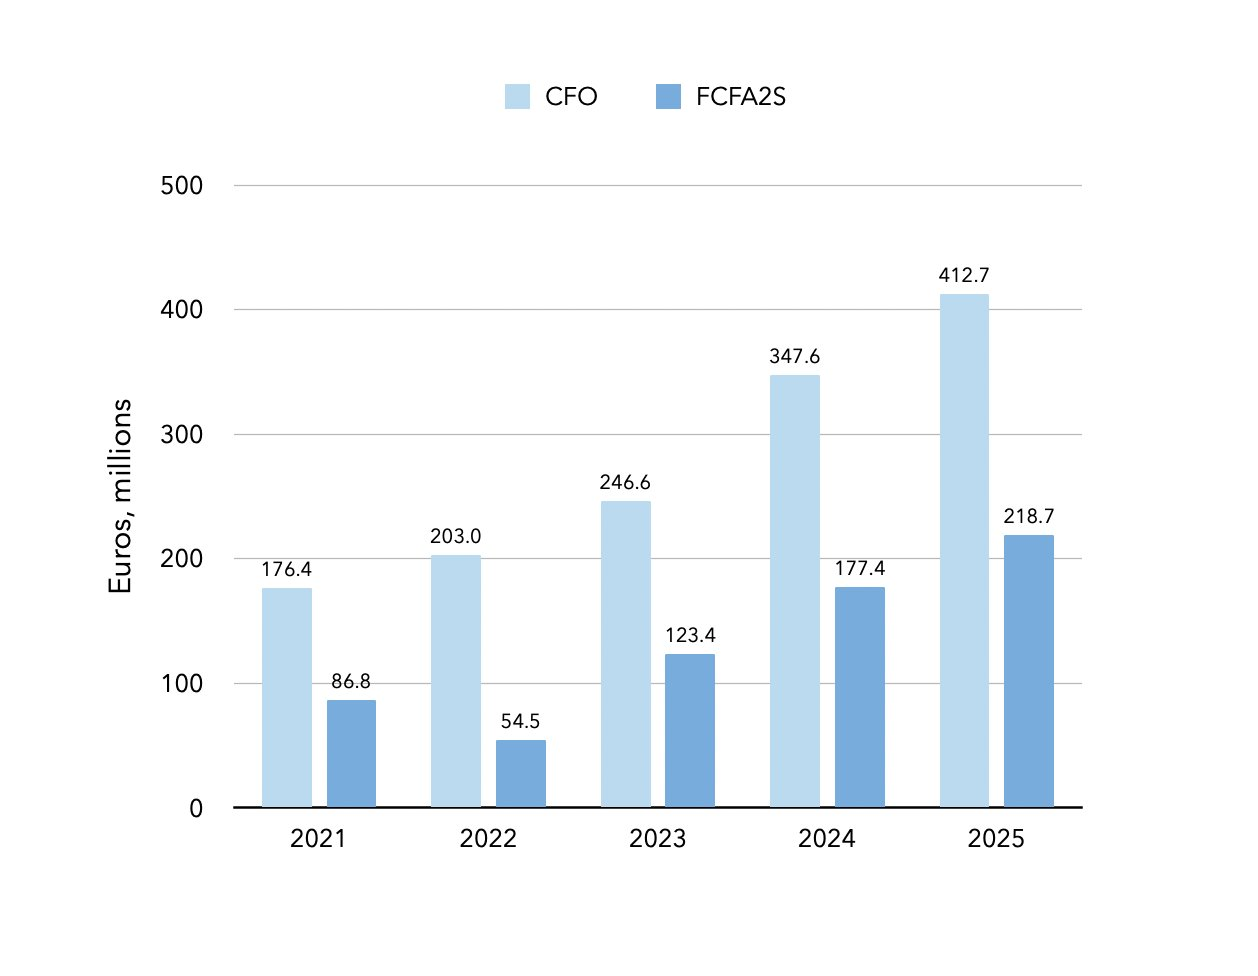
The figure above shows the development of cash flow between 2021 and 2025. Operating cash flow grew at a compound annual rate of more than 23%, while free cash flow as defined above showed even stronger annual growth of 26%.
Acquisitions
Whereas the third quarter was relatively light in terms of acquisitions (EUR 19.2 million), the fourth quarter showed a clear acceleration. In the last three months of 2025, Topicus spent EUR 69.8 million on acquisitions. In addition, the second tranche of the investment in the Polish serial acquirer Asseco Poland was completed, involving EUR 216.9 million. In total, Topicus spent more than EUR 700 million on acquisitions in 2025, a record and a multiple of what was spent in previous years.
Moreover, 2026 has already got off to a good start, as Topicus spent a further EUR 20.3 million on acquisitions in the first two months. With a debt ratio of roughly 1x operating cash flow, Topicus also still has plenty of firepower left for additional acquisitions. Given the uncertainty surrounding software companies and the valuations under pressure, this presents opportunities for an acquisition machine like Topicus.
Artificial intelligence
So the company is performing well: very high cash flow growth, healthy organic growth in recurring revenue and a strong quarter in terms of acquisitions. The elephant in the room, however, is investors' fear over the impact of artificial intelligence. You will not have missed that we have paid a great deal of attention to this in recent weeks, including in the Deep Dive below.
 Michael Gielkens
This week saw the publication of an interesting article by analyst Nikotes. He argues that the impact of AI on sector-specific software companies such as Topicus will remain largely limited, because their systems are deterministic and mission-critical. Customers demand absolute accuracy and strict regulatory compliance for their core operational processes, and this need for zero error tolerance cannot be reconciled with the probabilistic nature of modern AI applications. The competitive advantage of companies such as Topicus and Constellation Software is fundamentally rooted in specific domain knowledge and substantial switching costs, which make end users reluctant to trade reliable workflows for experimental solutions. Well-run VMS platforms, by contrast, will successfully integrate AI technology as a tool to increase their own efficiency and further consolidate their market position, in a process he describes as software Darwinism.
Nvidia CEO Jensen Huang also weighed in on the discussion in an interview with CNBC. Huang argues that the market is misjudging the impact of AI on the software sector and that the recent share price declines are unwarranted. Rather than replacing existing platforms and applications, AI agents will act as users of these tools. He emphasises that digital workers will not build new systems, but will simply make use of proven software such as browsers or accounting programmes to carry out their tasks. Because companies will in the future deploy not only "biological employees" but also hundreds of thousands of AI agents, total usage of software licences will, according to Huang, actually increase significantly. Established software companies retain their competitive advantage because their systems continue to serve as indispensable sources of data, and because they themselves will develop specialised agents for their platforms.
This is what the head of product at Anthropic said today in the WSJ and it makes perfect sense to me.
— Drew Cohen (@DrewCohenMoney) February 24, 2026
As I wrote before and said on The Synopsis Podcast yesterday,
the AI companies are not going to be able to create products and support teams around every single product that a… pic.twitter.com/Y7ZM3WzzvR
Another vote of confidence for software companies came from Scott White, Head of Product Management at Anthropic. He stated this week in the Wall Street Journal that platforms such as Cowork can actually help software companies deliver more value to their customers, and can help end users get the most out of that software. White states that Anthropic is not a company trying to own every workflow within every software tool, but is instead trying to help people get their work done. Ironically, it was precisely Anthropic's own product announcements that put pressure on software company share prices, on fears that Anthropic would replace them.
We continue to follow these developments with a level head and will keep you informed of developments in this area through our newsletters and client conversations.
Topicus is currently trading on the Toronto stock exchange at a price of CAD 92.76 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
HEICO shares stumble over minimal stumbling blocks
As usual, investment holding company Heico (New York: HEI-A) opened its earnings discussion with heartfelt thanks to God and to the more than 10,000 team members who keep the company's engine running day in, day out. It is something of a ritual within the company, one that also projects a culture that is difficult to copy and a track record that many a competitor can only be envious of.
The figures for the first quarter of fiscal 2026 were largely in line with analyst expectations. Revenue rose 14% to $1.18 billion, of which 10.2% was organic, a sign that growth is not driven purely by acquisitions but is broadly based. Operating profit climbed 15% to $259.9 million, with the operating margin remaining virtually unchanged at 22.1%, despite margin pressure from the Electronic Technologies Group (ETG) division. This translated into earnings per share of $1.35, comfortably above the analyst consensus of $1.27. Nevertheless, the shares plunged more than 10% intraday at the open. The market saw something it did not like.
Falling operating cash flow
The first unexpected negative figure came from operating cash flow, which fell from $203 million a year earlier to $179 million this quarter, a decline of almost -12%. At first glance this looks worrying, but there turned out to be a good explanation. CFO Carlos Macau explained that this was affected by payouts under the Leadership Compensation Plan (LCP) to a team member who has been with the company for more than 40 years. He clarified that these payouts are in fact cash-neutral for the company, since they are fully funded through investments in company-owned life insurance policies (which run through investing cash flow). Macau also noted that variable bonus payments for fiscal 2025 were considerably higher, simply because that year was exceptionally good. Management has already indicated that a further payout of roughly $73 million is planned for the remainder of the year, which will once again weigh on reported operating cash flow, but will not affect the company's actual cash position.
The 'Perfect Storm' at the ETG division
Another concern among investors related to the operating results of the Electronic Technologies Group (ETG). Although revenue there grew by 12.2%, operating profit fell by 4.3%. The margin contracted by as much as 330 basis points to 19.8%. According to the Mendelson brothers, however, this was a "perfect storm" in terms of product mix. This quarter saw more defence products with lower margins delivered, while high-margin aerospace shipments lagged behind. Moreover, the aerospace market is shifting. During the Q&A, a question was asked about the shift from the traditional GEO market to the LEO market; GEO refers to large satellites at high altitude that remain fixed over one point (such as for TV), whereas LEO refers to smaller satellites in a low, fast orbit around the earth (such as for Starlink internet).
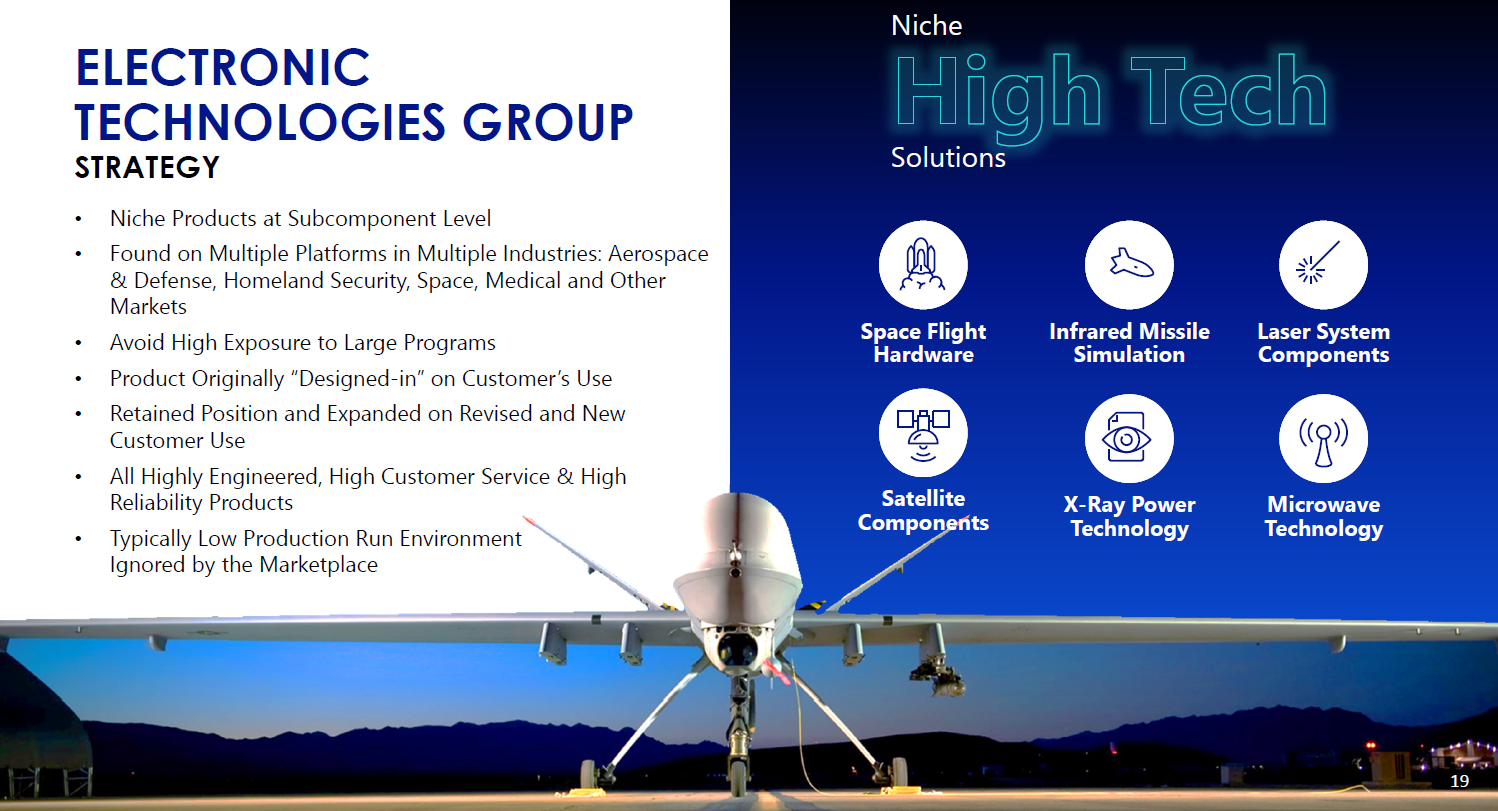
Originally the business was heavily oriented towards GEO, but we now have a stronger presence in LEO. The shift to LEO isn't cheap; margins are initially lower due to high R&D costs. But we go where the customers are. We now have a very strong offering in LEO with healthy margins, although it remains a choppy business quarter to quarter. - Eric Mendelson
Management emphasised that order books are at record highs and that such fluctuations are inherent to the niche market in which they operate.
M&A discipline in a hot market
Currently, the aerospace sector in particular finds itself in what may be an overheated market. More and more smaller companies are emerging that combine the words 'space' and 'AI', achieving billion-dollar valuations before they are even profitable. Victor Mendelson acknowledged that acquisition multiples are indeed higher at the moment, but stressed that HEICO is often the "buyer of choice" for family businesses seeking to secure their legacy. Paying for a company without cash flow is something HEICO will never do, the co-CEO emphasised.
"You don't compound by paying insane prices"
With a debt leverage of 1.79x operating profit, HEICO also has a highly flexible balance sheet to capitalise on new opportunities in its well-stocked acquisition pipeline. Even the increased competition in the PMA market (Parts Manufacturer Approval), the domain in which HEICO is market leader, does not worry the CEO. The fact that other players are now also buying PMA companies is something he views as a validation:
"People used to think we were crazy to get into repair and distribution. Now everyone sees the value. We have the best customer relationships in the industry, and you don't simply change that."
Conclusion:
The share price drop appears to be an overreaction to accounting noise surrounding the pension plan and a temporary dip in product mix. Those who look past the figures see a company that is growing organically at double-digit rates, has a rock-solid balance sheet, and nurtures a culture that simply cannot be bought elsewhere.
HEICO is currently trading on the New York exchange at a price of USD 243.83 per Class A share.
Brookfield CEO tempers private credit fears and doubles down on AI infrastructure
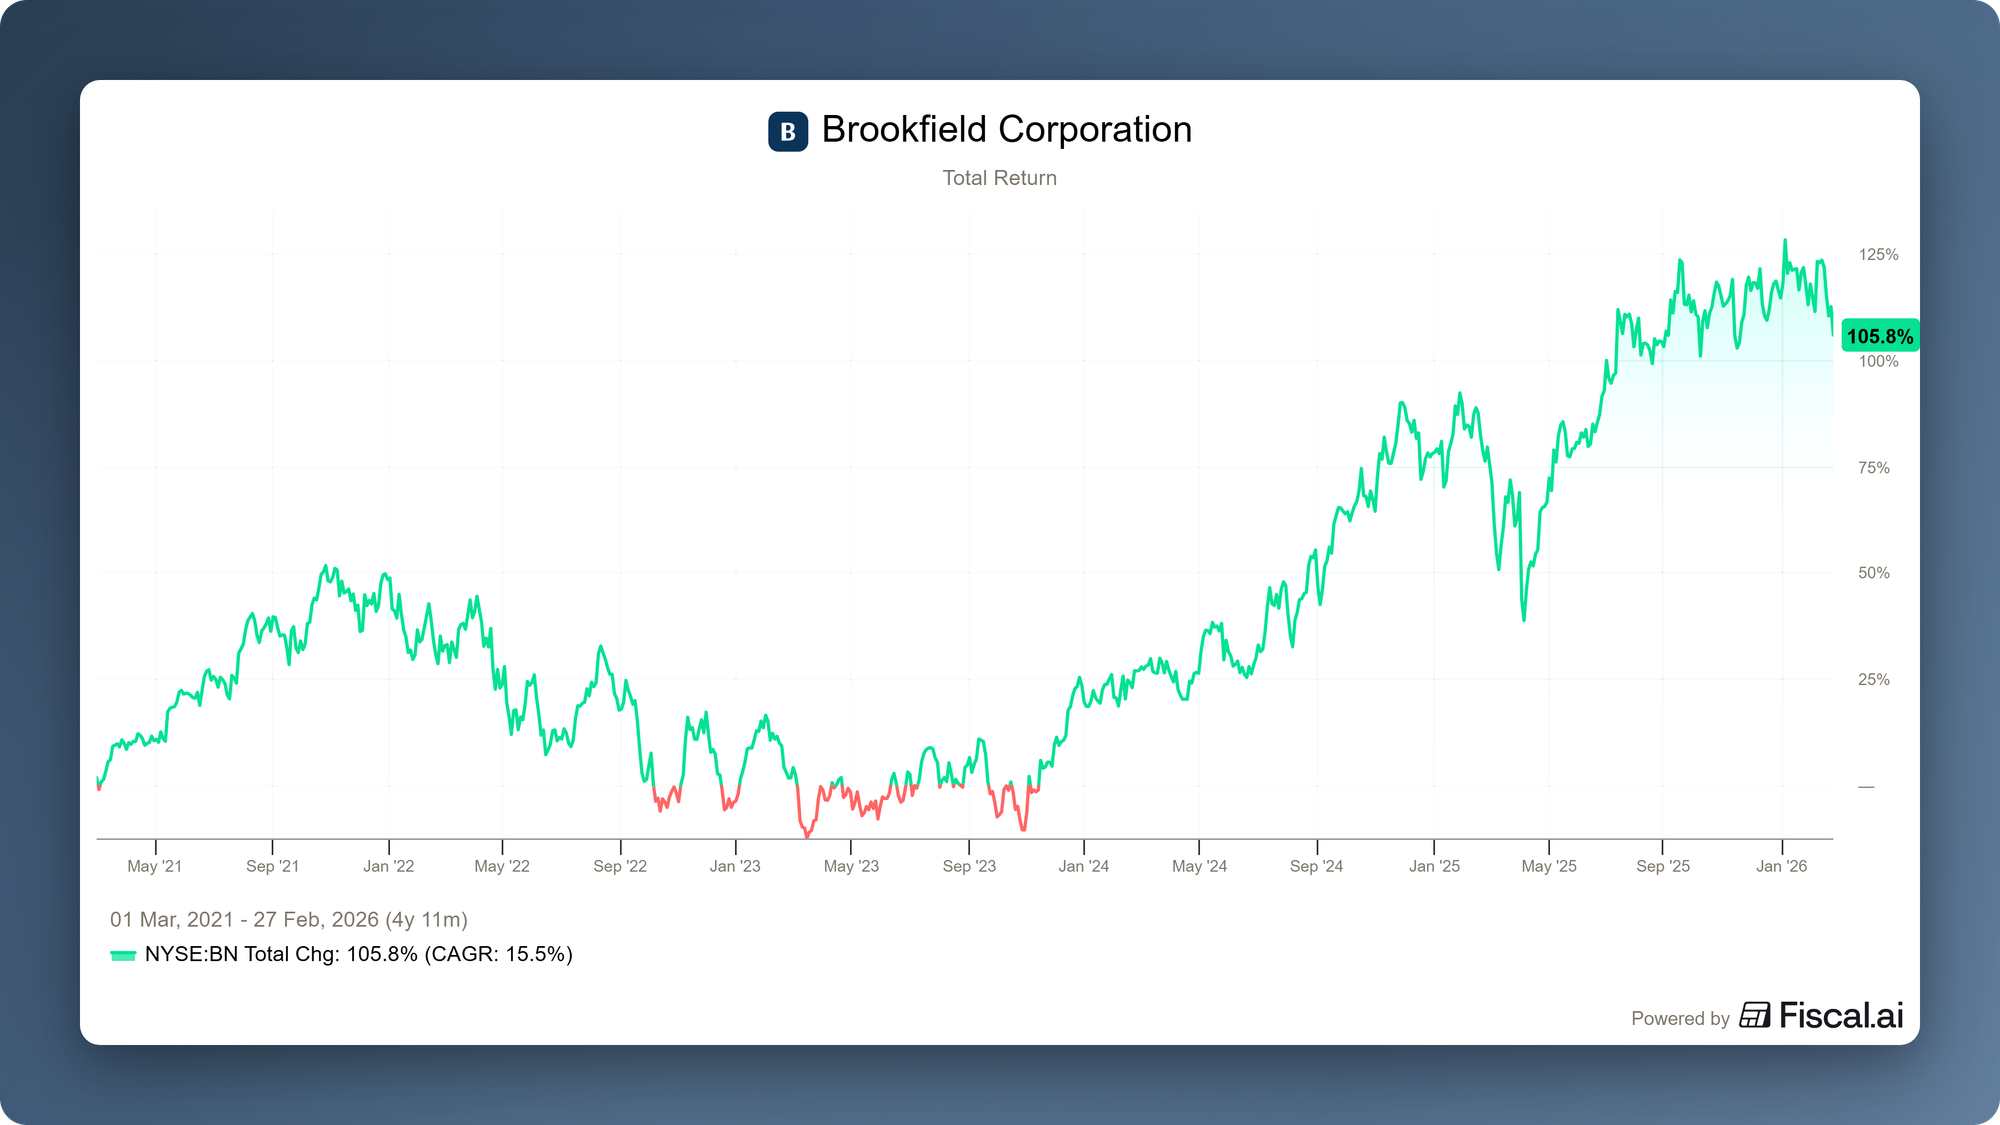
This week, Bruce Flatt, CEO and one of the major shareholders of the Canadian investment holding company Brookfield Corporation (New York: BN), was interviewed by Bloomberg.
Private credit fears are overdone
Following several bankruptcies at companies financed by private credit, investors have grown more uncertain about this sector in recent months. Shares of investment holding companies such as Brookfield and KKR, or Investor AB's EQT, are under pressure as a result. This has recently been compounded by software-related fears, given that many software companies have received financing from private credit firms. In the interview, Flatt tempered the recent nervousness surrounding private credit. In his view, it represents only a small part of the global credit market. Loans to software companies form an even smaller segment within that. He therefore does not see the unease as a risk that could spill over into the entire financial system.
Flatt also points out that private credit is often discussed as a single entity, whereas the market in fact consists of many different niches. He does not find it strange that some loans or valuations turn out, in hindsight, to have been too optimistic. In every cycle there are periods in which too much is paid or in which expectations fail to materialise. That can hurt specific investors and structures, but he does not view it as a chain reaction that would disrupt the credit system. According to him, the unease is being blown out of proportion, partly because the news media like to fixate on a small topic that happens to be in the spotlight at the time.
Flatt does acknowledge that private credit, precisely because it is arranged outside the public markets, is sometimes perceived as opaque. This, he says, feeds the sense that "something" might be lurking beneath the surface. But he stresses that the scale of private credit is limited relative to the total credit market, and that incidents within a niche should not automatically be translated into broad contagion. Even with loans to companies coming under pressure from technological change, he says, it is mainly a matter of individual cases, not a problem that spreads through the entire system on its own.

Artificial intelligence
In the interview, Flatt emphasises the role of AI as new basic infrastructure. Brookfield focuses on financing everything needed to make that growth possible, from energy and equipment to physical infrastructure. The investment sum that Brookfield cites in this context is enormous. The group estimates that the development of AI worldwide requires roughly USD 7 trillion in capital investment.
Flatt puts that development into perspective. Brookfield has been building what you might call the backbone of the economy for decades. It is just that its content changes over time. First it was about water networks, pipelines and toll roads. Then came, for example, telecom masts. Now attention is shifting to data centres and what he calls "AI factories". Flatt argues that the economy keeps acquiring new basic facilities and that AI is now part of that, comparable to the infrastructure that enabled earlier phases of growth.
Brookfield gave concrete shape to that AI infrastructure ambition this week with the acquisition of Ori Industries, a company that provides access to AI chips as a service. Ori has been folded by Brookfield into Radiant, its own platform that aims to offer companies and governments on-demand computing power. Brookfield approaches this as a rental model with tightly drawn-up contracts, under which customers keep paying the agreed fee even if their need for the chips subsequently declines. In doing so, Brookfield specifically wants to prevent returns from becoming dependent on the pace at which chips lose value or become technologically obsolete. Radiant also focuses on so-called sovereign clouds, computing environments in which data must remain within national borders, a theme that is becoming increasingly important for governments and large organisations.
Fear of overinvestment
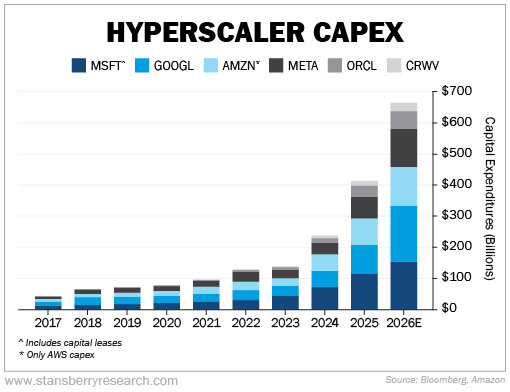
A question that quickly arises with such an immense wave of investment is whether too much is being built. In recent weeks we have seen investors grow nervous whenever the big technology companies announce their investment plans. Flatt draws an important distinction here with earlier technology periods. In earlier network investments, construction sometimes happened first, with the hope that customers would follow afterwards. With the projects Brookfield is working on, it happens differently. Construction only starts once contracts have been signed in advance with a country or a company. That means, in his view, that the risk of demand falling short lies not with the builder but with the party that has committed to the usage.
He emphasises that these are very strong counterparties. Countries that have this kind of facility built are highly creditworthy. The big technology companies are so large that he compares them to countries. They are looking for parties with the scale and capital to deliver not just the building itself, but the entire chain around it, such as the connection to energy, the links and the fit-out. According to Flatt, the bottleneck is not demand but the speed at which construction can take place. In his view, there is more of a shortage of capacity than a risk of overcapacity.
The three D's: digitalisation, deglobalisation and decarbonisation
Flatt sums up Brookfield's long-term direction with three themes. These are digitalisation, sustainability (decarbonisation), and a world in which countries want to build more locally (deglobalisation). He notes that these themes have remained the same, but that their content has shifted. Digitalisation used to be about facilities for the cloud, now it is about facilities for AI. Sustainability used to be mainly about renewable energy, but is now broader because simply far more electricity is needed. And whereas construction used to be drawn mainly to the United States, he now sees the need to set up local infrastructure in multiple countries at the same time.
Despite all the alarmist headlines, Flatt remains notably calm about the bigger picture. He says the world often thinks that now is the worst possible moment, fuelled by all those headlines, whereas there have been several periods in his career that felt tougher. Looking back a few decades from now, he says, one will see that the world has moved forward. And looking ahead now, one sees that developments in technology and medicine are boosting productivity and making people healthier. That fits with the type of investments Brookfield focuses on. These are projects with a horizon of decades, not a judgement on the sentiment of the month.
Brookfield Corporation is currently trading on the New York Stock Exchange at a price of USD 44.08 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
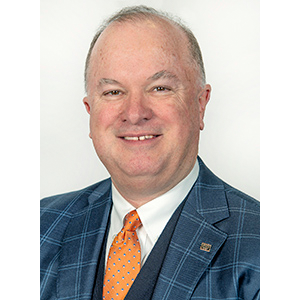
CEO Gayner regards Markel as a younger Berkshire Hathaway
Under the leadership of CEO Tom Gayner, Markel Group (New York: MKL) has evolved from a pure niche insurer into a diversified holding company driven by what Gayner describes as a "three-engine architecture". This structure consists of the core specialty insurance business, the investments in listed equities, and the growing portfolio of fully managed industrial and commercial companies under the Markel Ventures banner.
Flexible capital allocation
The central theme underpinning Markel Group's vision is the deliberate design of a system aimed at creating maximum flexibility in capital allocation."We're on the same path as Berkshire, but we're earlier on the curve," says Gayner.
In the 1980s, Berkshire found itself in a position of extreme over-capitalisation; in 1988, book value stood at $3.4 billion against just $600 million in insurance premiums. This meant the ratio of premiums to capital was less than 20%, giving Berkshire the freedom to invest its assets almost entirely in equities without jeopardising policyholder safety. It's a scenario Gayner would love to 'saddle' Markel with, he jokes:
"May the Lord strike us with the curse of also becoming that over-capitalised"
The mathematical consequence of this is that the leverage on the balance sheet decreases, which opens up "degrees of freedom" on the asset side of the balance sheet. Whereas a traditional insurer is required to hold a large share of its assets in high-quality bonds to meet future claims obligations, an over-capitalised company can shift these assets towards equities and the outright acquisition of unlisted businesses, which offer a higher expected return over the long term.
Market environment and future outlook
Markel Group's equity portfolio, worth approximately $12.5 billion at the end of 2025, is often misunderstood as being broadly diversified simply because of the 140 to 150 names it holds. Gayner notes that there is a reason for this too. He argues that the changes he is witnessing now, both technologically and geopolitically, are faster and more far-reaching than anything he has experienced in his 40-year career. This reinforces his belief in the "information value" of a broad equity portfolio. By not trying to predict the future, but instead responding to what the market tells him through price action, he aims to avoid errors of "omission".
Despite the huge diversification in the number of companies, Gayner points out that in reality the portfolio is highly concentrated from an economic perspective, with two-thirds of the value housed in four specific "buckets".
Berkshire Hathaway: Gayner regards Berkshire, in the current climate, as the "new S&P 500". Whereas the actual index has increasingly become a concentrated tech bet, Berkshire offers the original promise of the S&P 500: broadly diversified exposure to the real economy (railroads, energy, manufacturing) at virtually zero cost. As the portfolio's "anchor position", it gives Markel stability and access to Buffett's capital allocation, without Gayner having to hold enormous amounts of low-yielding cash himself.
The Magnificent Seven: Markel holds substantial positions in five of the seven big tech companies (Alphabet, Amazon, Apple, Microsoft, Meta), which are valued for their superior business models and returns on capital.
Large Asset Managers: Investments in companies such as JPMorgan, KKR, Apollo, Brookfield and Blackstone. According to Gayner, these companies act as "royalty override" businesses within the financial sector.
Market Leaders: Companies with deep competitive moats such as Home Depot, Lowe's, Visa and MasterCard.

According to Gayner, this equity strategy combined with the flexible capital allocation described above is the fuel for what he describes as a "perpetual motion machine" of shareholder value.
His vision for the future, shared in the letter to shareholders published this week, rests on the foundation laid in 2025 and early 2026 through making rigorous choices, such as exiting reinsurance and promoting Simon Wilson (Insurance) and Andrew Crowley (Ventures) to Executive Vice Presidents in order to simplify the organisation. Gayner describes the current improvements as the first "green shoots" of a renewed Markel. Although the company has now been listed for 39 years, he repeatedly states that he feels they have "only just begun". The ultimate ambition is to set up the organisation in such a way that, regardless of technological or geopolitical headwinds, it is able to compound capital across generations.
The full interview with In Practise can be found via the link below. It goes deeper into the following themes:
 Tom Gayner, Chief Executive Officer of Markel Group - In Practise
- Lessons from mistakes: Gayner discusses how he recognises "melting ice cubes" (companies in structural decline) and why he now places more value on the loyalty of management teams than on purely numerical forecasts.
- Markel Ventures vs. Private Equity: Why Markel has an advantage as a "permanent home" for family businesses, and how they compete without the need to sell companies again after a few years.
- The psychology of the investor: How his dual role as CEO and investor has taught him that running a company is much harder than analysing a spreadsheet, and how this influences his investment choices.
- Operational focus: The specific reasons behind discontinuing the reinsurance activities and how the focus on insurance profit forms the basis for all their other investments.
- Internal culture: The role of the small investment team and how they use "opportunity costs" to choose between buying shares, acquiring companies, or repurchasing Markel's own shares.
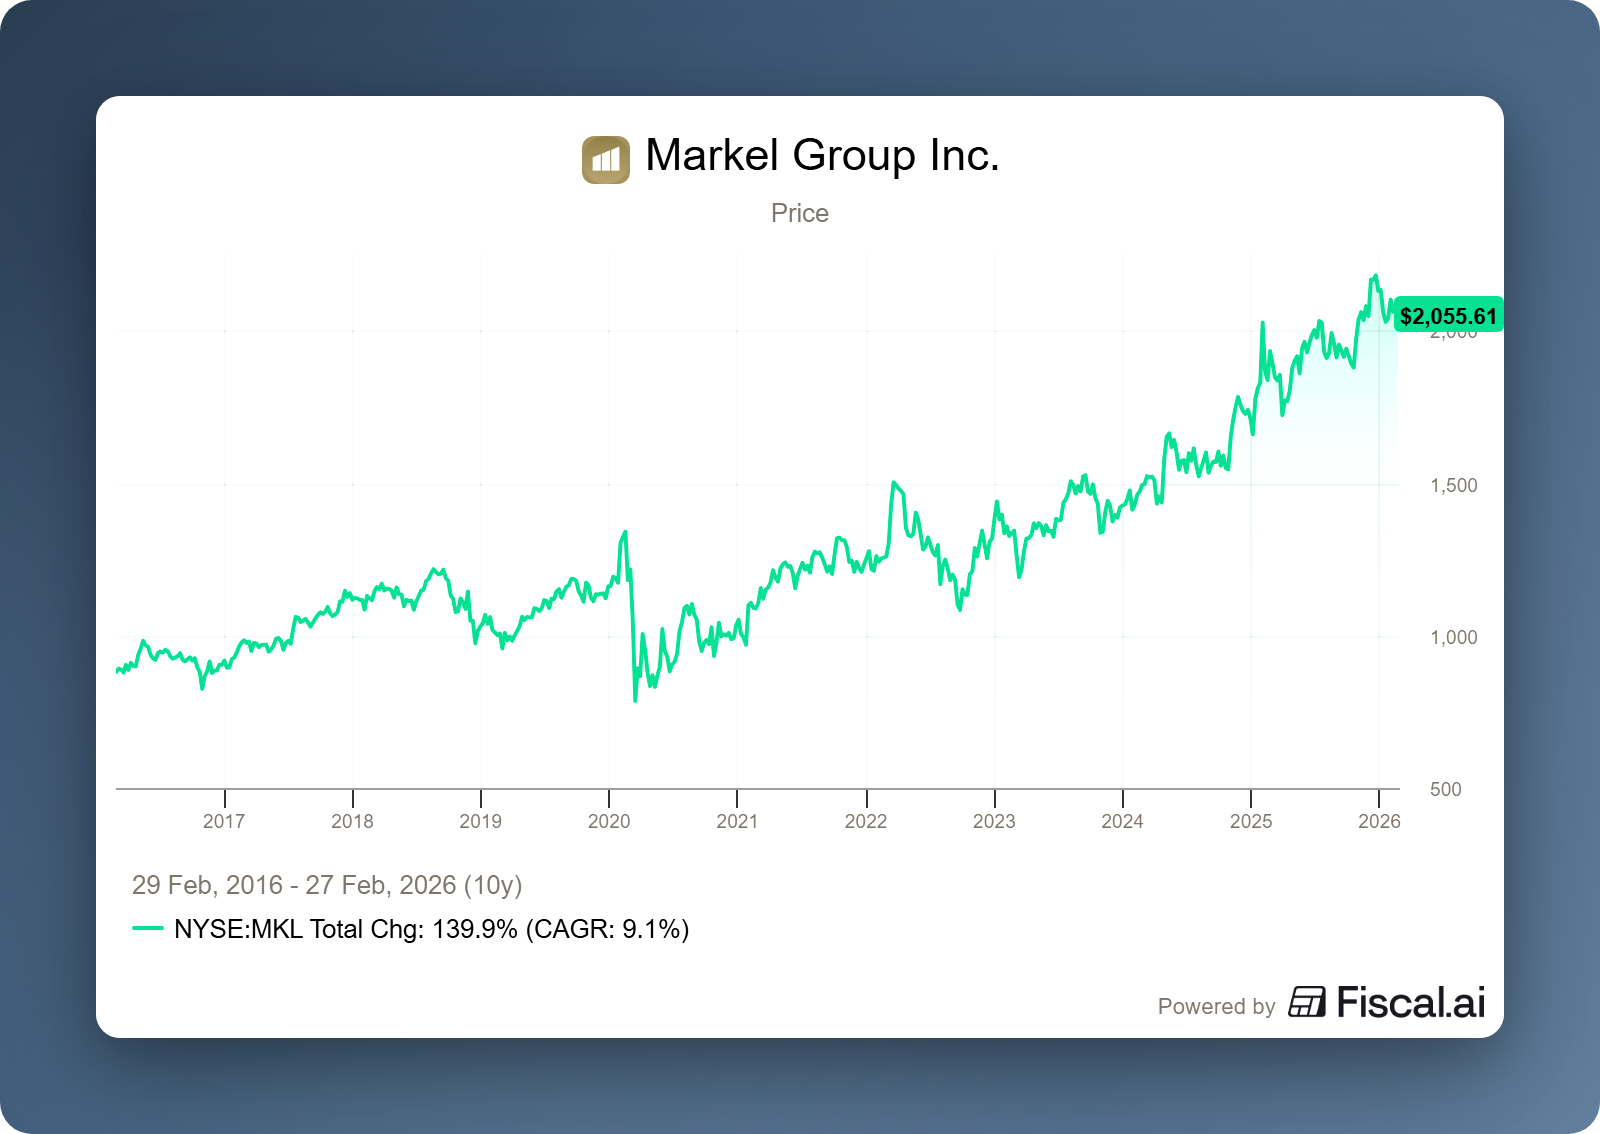
Markel Group currently trades on the New York Stock Exchange at a price of USD 2,055.77 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Contact us
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or on behalf of their clients.
You should carefully consider the risks before you start investing. The value of your investments can fluctuate. Past performance offers no guarantee for the future. You may lose (part of) your invested capital. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



