
Family Holdings #2 - Headlines vs. Fundamentals: Private Equity & Software


This week's topics:
A correction in private equity holding companies was driven mainly by headlines around private credit and politics, not by a deterioration in fundamentals. Events at Blue Owl and political noise were quickly translated into sector-wide concerns. At the same time, large platforms such as Brookfield, KKR and Apollo see 2026 shaping up to be mainly a transition year: less dependent on cheap money and multiple expansion, with more focus on underwriting, structure and operational execution.
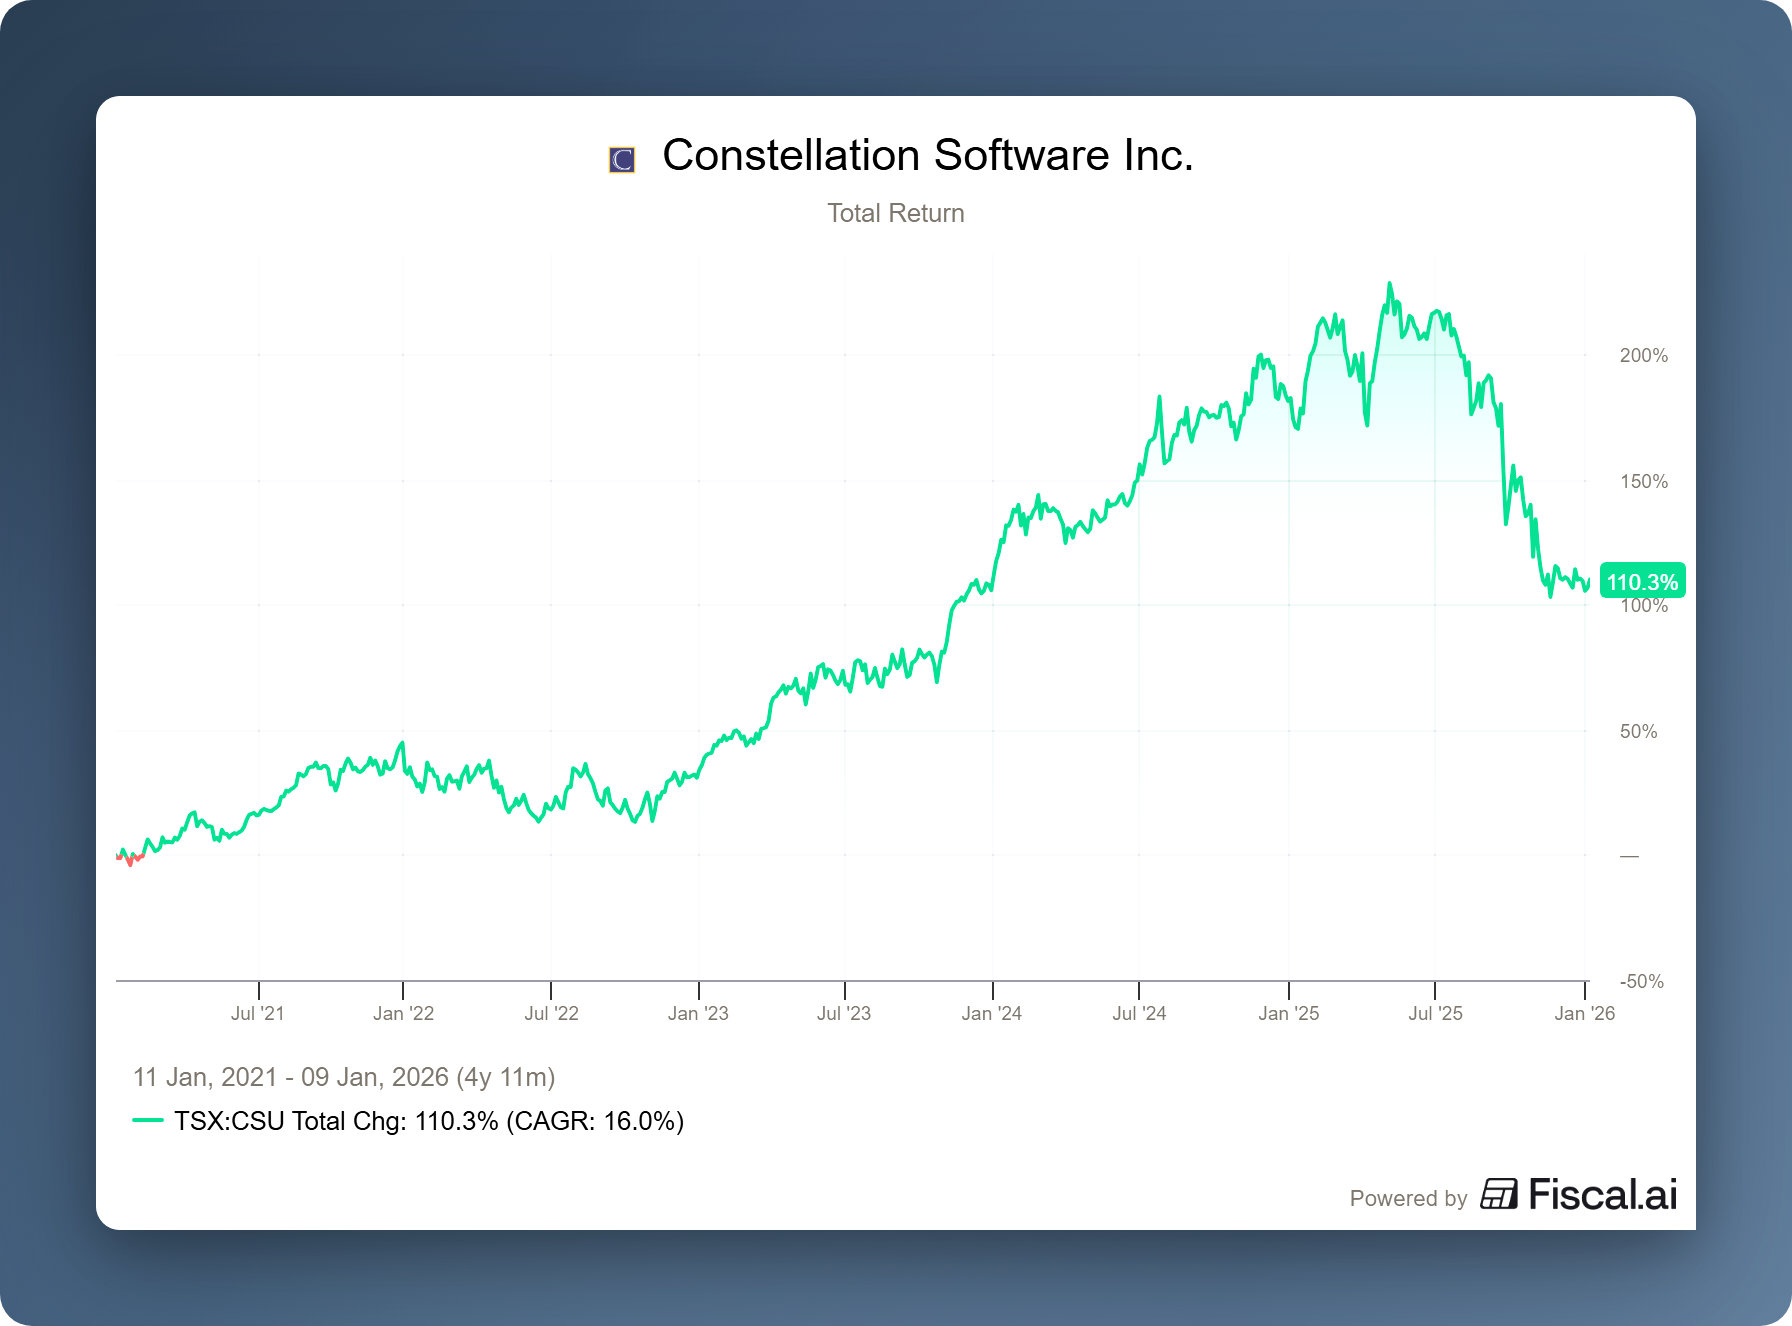
Constellation Software experienced a sharp share price correction in 2025, driven mainly by concerns about AI and the departure of founder Mark Leonard as CEO. According to analyst Paul Treiber (RBC), this pullback is mainly sentiment-driven, with the underlying fundamentals remaining very strong. Both RBC and Tresor Capital view the software sector, and Constellation and Topicus.com in particular, as attractively positioned for 2026, with further cash flow growth ultimately expected to lead to higher valuations again.
Prosus has voiced sharp criticism of European competition policy following the acquisition of Just Eat Takeaway, which was only approved after a mandatory sale of its stake in Delivery Hero. CEO Fabricio Bloisi argues that this regulation hinders large-scale investment and the formation of European tech champions, and runs counter to recent calls for easing the rules. According to Prosus, this undermines the investment climate in Europe and limits the ability to scale up against American and Chinese competitors.
In Brief:
Constellation Software (Toronto: CSU) has, through its venture capital arm VMS Ventures, taken a position in Layers, directly tapping into the digitalisation of the education market in South America. In addition, it has invested in AssetCore, which specifically focuses on the rise of AI within wealth management. Alongside these participations, regular activities are continuing unabated, as this week subsidiary Volaris completed the acquisition of BIG Consulting. This company from Wisconsin, founded in 1995, provides data analysis and business insights to the agricultural sector in the American Midwest.
TerraVest (Toronto: TVK) acquired the American company KBK Industries for USD 90 million, equivalent to an EBITDA multiple of 5.6x. KBK produces above-ground and underground fibreglass and steel storage tanks from Texas and Kansas, and strengthens TerraVest's position in heavily regulated markets such as C-stores, agriculture and energy. The acquisition fits seamlessly with earlier expansions in Canada and Maryland and improves geographic diversification, which is important given transport costs and exposure to trade tariffs. With plants in the north, east and south, TerraVest now controls a significant part of the North American fibreglass tank chain.
KKR (New York: KKR) is selling its majority stake in OneStream to the European private equity player Hg Capital, in an all-cash offer of USD 6.4 billion, representing a premium of 31% over the last closing price. For KKR, this marks a particularly successful exit. The firm expects a gross IRR of 24.9% on the original investment made in 2019, and has already realised USD 2.8 billion in proceeds since the IPO in 2024. Altogether, this translates into a return of 4.5x the original investment.
Sofina (Brussels: SOF) and Scottish Mortgage Trust (London: SMT) stand to benefit from a recent increase in the value of their holding in ByteDance. The Chinese parent company of TikTok is being valued by venture capital firm HSG (formerly Sequoia China) in a new fund at a range between USD 350 and 370 billion, above the level of a recent share buyback of more than USD 330 billion. The rising valuation is being driven by strong financial results, with revenue in the first two quarters of 2025 surpassing that of Meta, and annual profit expected to come in at around USD 48 billion. Sofina and Scottish Mortgage may sell part of their stake to HSG's new fund in order to take some profit.
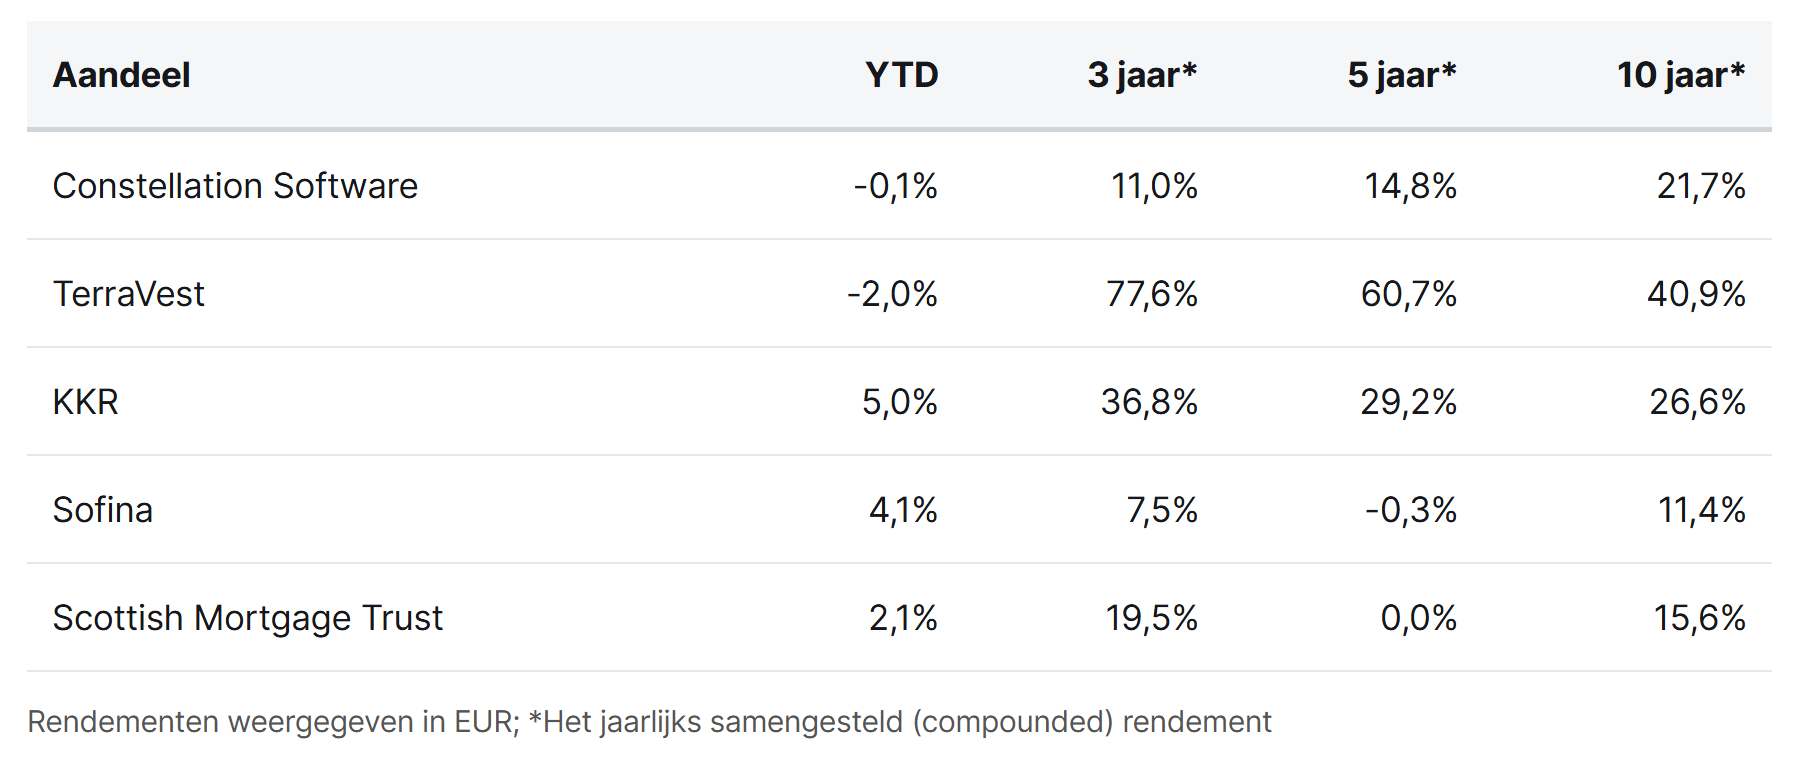
Constellation Software, TerraVest, KKR, Sofina and Scottish Mortgage Trust are currently trading on the stock exchanges of Toronto, New York, Brussels and London at prices of CAD 3,311, CAD 160.22, USD 132.38, EUR 257.20 and GBP 12.04 per share, respectively.
The 5 Predictions for 2026
On an investment forum, we were asked to make five interesting predictions for the year 2026. While we obviously do not have a crystal ball, this can be an interesting thought framework. We share them here without obligation, but explicitly draw attention to the disclaimer below.
Disclaimer: This piece is intended solely as a thought exercise on possible developments and scenarios for 2026. It does not represent a view, forecast or investment advice from Tresor Capital. There is no guarantee whatsoever that the developments described will actually occur. Do not base any investment decisions on this. Always do your own research and form an independent judgement.
- The revenge of the Other 493
2026 will be the year in which market breadth finally increases. At present the market is highly concentrated, which makes sense at this stage of the bull market, as investors' full attention is on the AI winners that most often make the headlines. However, if we look back at the internet era, we see a clear pattern: in such technological revolutions, it is the large technology companies that benefit most in the first phase. In the second phase, though, the focus shifts to the companies that manage to achieve efficiency gains by implementing the new technology. Instead of the Magnificent 7, in 2026 it will be the other 493 companies in the S&P 500 that take centre stage, as they successfully integrate AI into their operations. - Software is dead, long live software!
After the second half of 2025 proved a very difficult period for software stocks, in 2026 the focus will shift back to the durable nature of these businesses. Current share prices wrongly price in the assumption that software will be eaten by AI. However, software companies, and vertical market software companies in particular, with their deeply rooted customer relationships, are actually ideally positioned to implement AI and add value. In 2026 the market's perspective will turn, and it will become clear that AI is not a threat but an enormous opportunity for this sector. - The sleeping giant Berkshire Hathaway awakens
Berkshire Hathaway's new CEO, Greg Abel, will succeed in putting a substantial amount of capital to work, whether through large acquisitions or organic growth projects. Abel has built a foundation of more than 20 years of successful investing in energy infrastructure and an excellent track record at Berkshire Hathaway Energy. That fits seamlessly with current macroeconomic trends, such as the US government's large investment needs, for example in building nuclear reactors, and rising energy demand from AI data centres. This creates an ideal scenario for Berkshire Hathaway to put more capital to work at attractive returns. - The IPO window opens
2026 will be the year in which the IPO window swings wide open again. Trade tariffs and the resulting uncertainty meant relatively few listings took place last year, but once calm returns in 2026, companies will feel more comfortable taking the step to go public. Major players such as SpaceX, Anthropic and OpenAI already appear to be preparing for a listing, which will also encourage other companies. Listed holding companies such as Sofina and Scottish Mortgage Trust will benefit from this as more of their private holdings gain a listing. This brings greater liquidity, better price discovery and more certainty about the valuation of their unlisted positions, allowing them to realise attractive gains as well. In addition, private equity holding companies such as Brookfield, KKR and Apollo stand to benefit from the reopening of the IPO window through a narrowing of their discount and the realisation of gains and performance fees on their investments. - D'Ieteren brings Belron to the stock market
D'Ieteren holds a stake in Belron, the parent company of Carglass, alongside several private equity partners. Now that the investment cycle is largely coming to an end for these private equity parties, these partners want to realise a substantial part of their capital by bringing Belron to the stock market. It is possible that D'Ieteren will also sell part of its stake at the IPO to strengthen its cash position and top up its war chest. In any case, a listing of Belron will lead to more transparent price discovery around the valuation of the subsidiary. This could be an important trigger for a re-rating of D'Ieteren shares, which currently trade at a significant discount. Moreover, after an operationally somewhat more difficult 2025, 2026 looks set to be the year in which Belron stages a decent recovery. If the fundamentals continue to improve and the market allows, 2026 could be a very attractive time to bring Belron to the stock market.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Recent price pressure versus the reality at private equity holding companies
The private equity investment holding company sector finds itself in a transitional phase. The era of "cheap money" is behind us, and the market is forcing major players to return to the basics: underwriting quality and operational execution. Although the week began with turmoil caused by political statements and liquidity concerns, the contours of the future are becoming clearly visible in sectors such as nuclear energy and AI infrastructure.
Correction after a strong rally
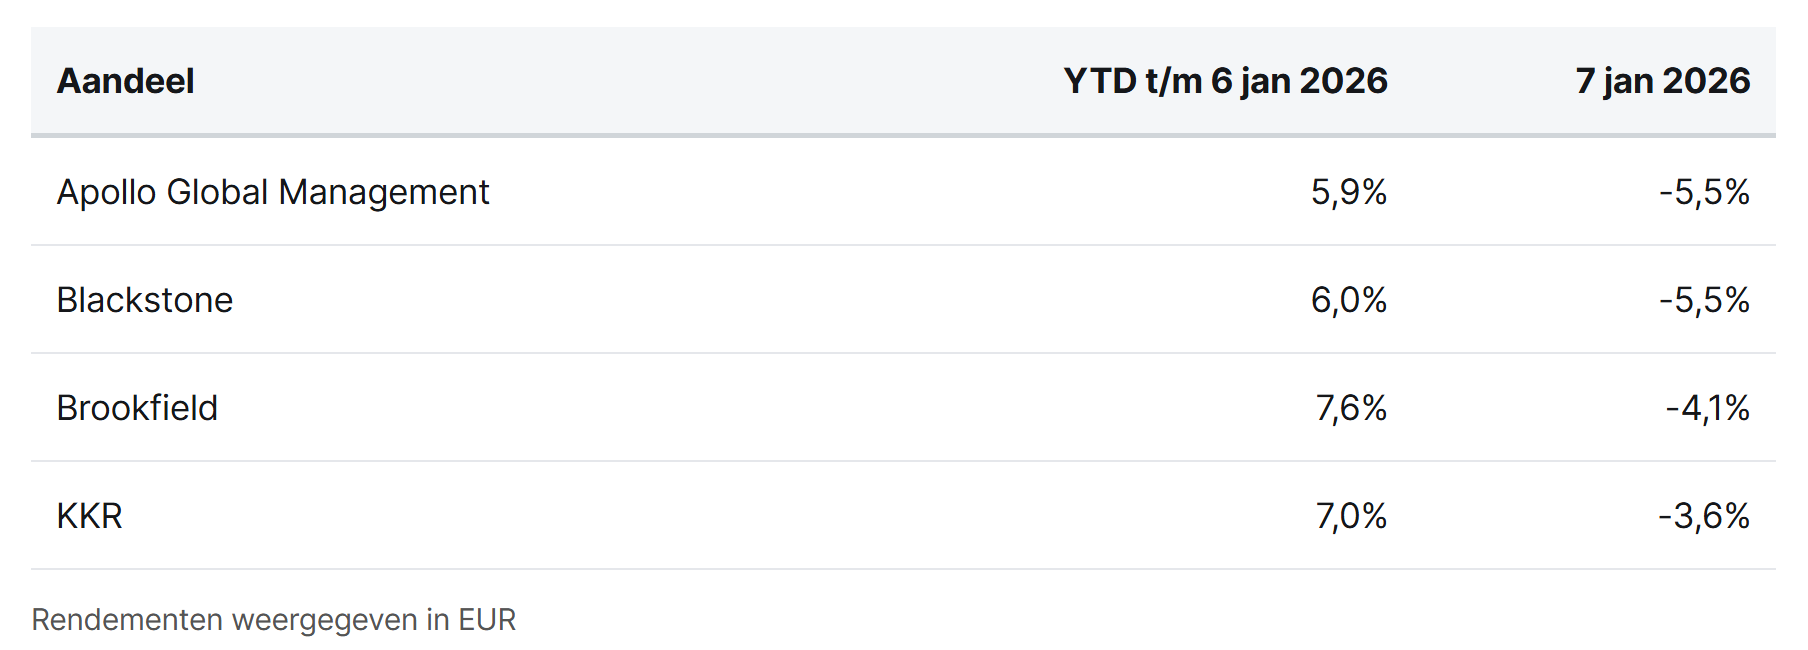
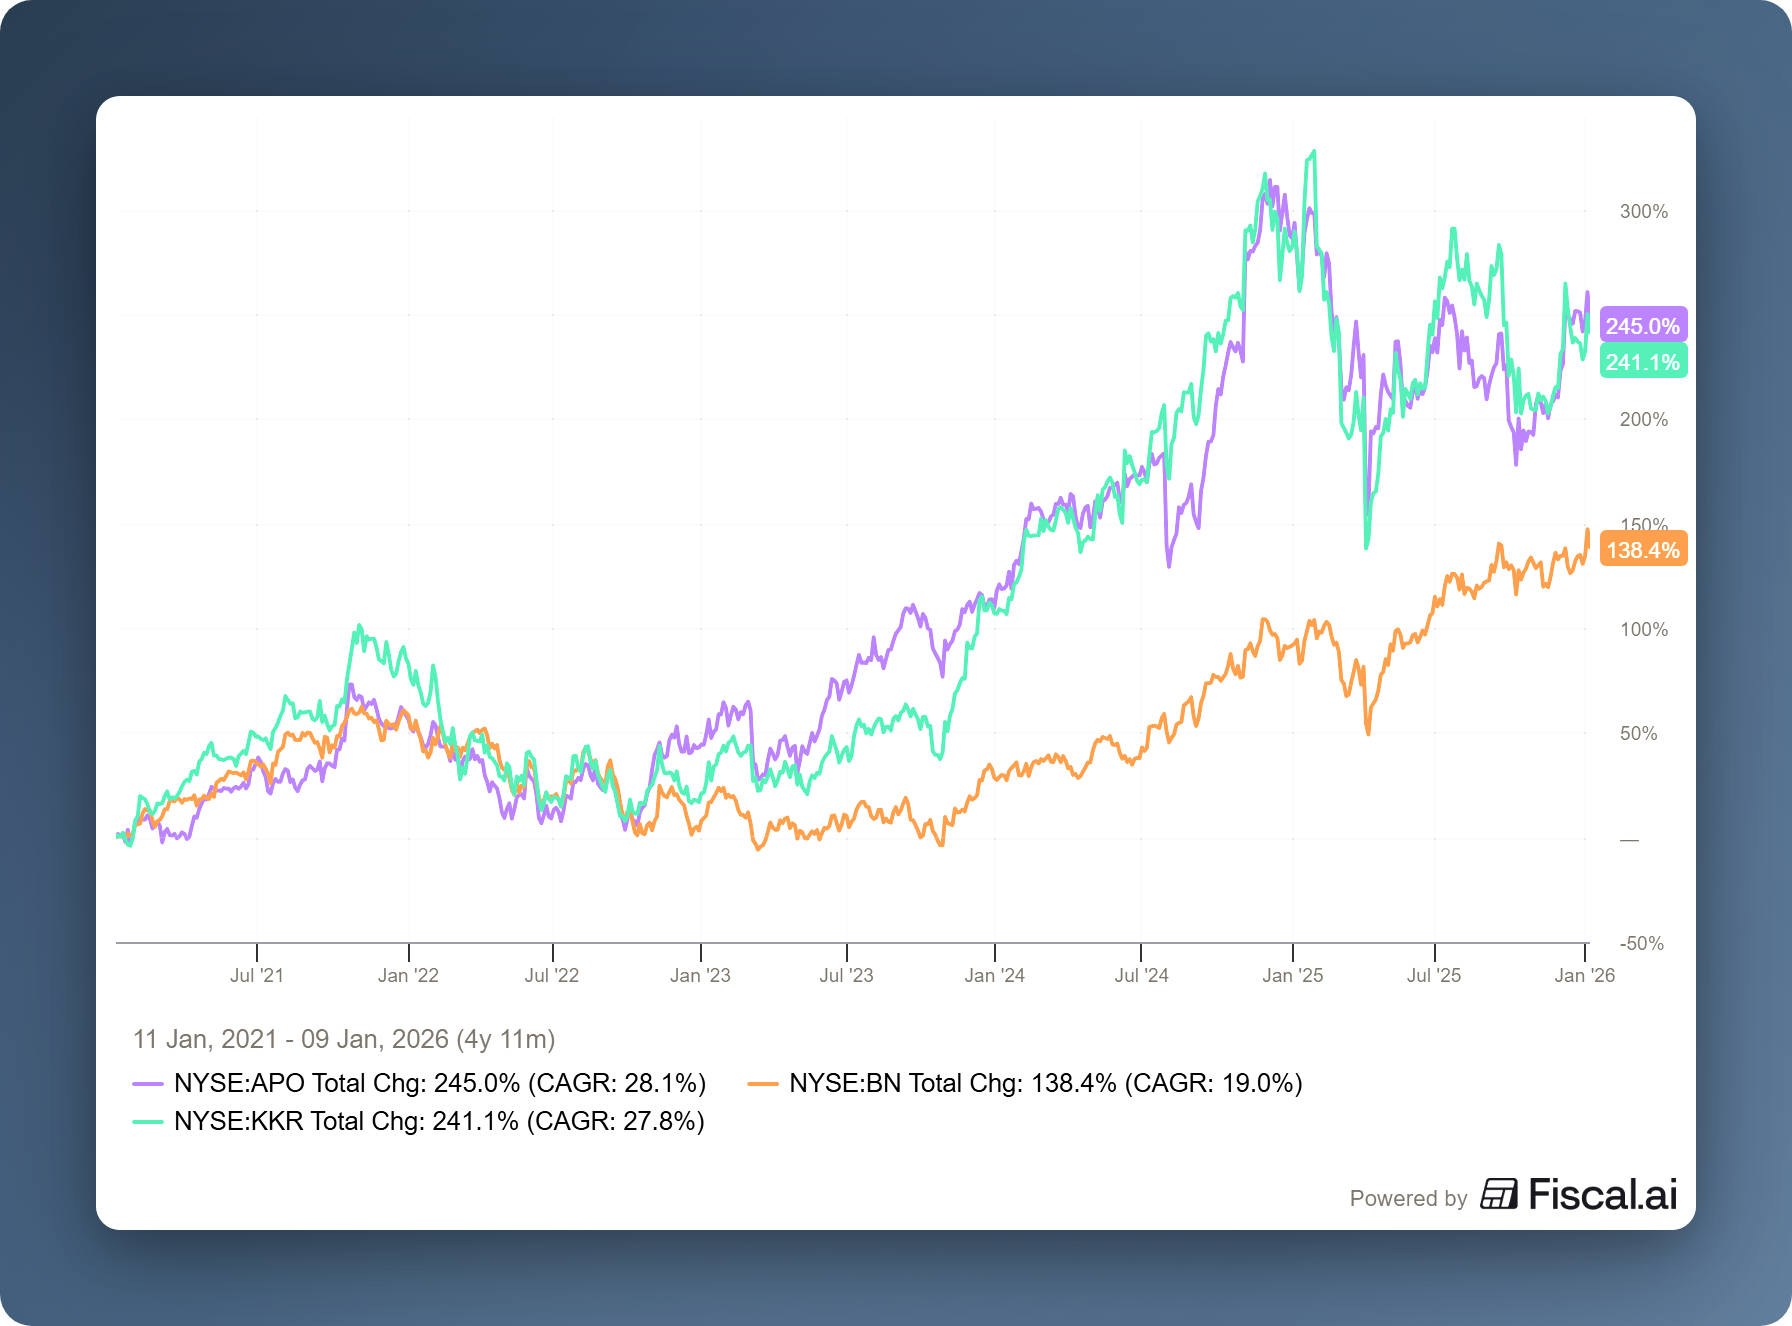
After a strong start to the year for private equity holding companies such as Apollo (New York: APO), Brookfield (New York: BN) and KKR (New York: KKR) and alternative investment manager Blackstone (New York: BX); with share price gains of roughly 6–7% in the first four trading days, a clear correction followed on 7 January. The shares gave up 3–6% that day. That move was caused by two separate events on that day.
First, there was news surrounding Blue Owl Capital, where investors were rattled by a sudden surge in redemption requests at a private credit fund. This concerned a so-called Business Development Company (BDC): a semi-liquid fund that provides loans to mid-sized companies and periodically offers investors limited redemption options. Following a sharp rise in redemption requests, Blue Owl decided to temporarily raise its redemption limit to around 17% of fund assets, far above the usual 5% per quarter. This step was not a proactive choice, but a response to the fact that more investors than usual wanted to exit at the same time. The market translated this incident into a sector-wide loss of confidence, putting other alternative asset managers under pressure as well.
BREAKING: President Trump announces steps to ban large institutional investors from buying single-family homes.
— The White House (@WhiteHouse) January 7, 2026
"People live in homes, not corporations." - President Donald J. Trump 🇺🇸 pic.twitter.com/MvG2mGodR2
In addition, political noise played a role. In a post on Truth Social, Donald Trump stated that large-scale institutional investors are contributing to the deteriorating affordability of homeownership for American households, particularly first-time buyers, and announced that he wants to explore ways to restrict their purchases of single-family homes.
As a result, listed private equity holding companies and 'alternative investment managers' came under pressure, as investors often lump them together with large-scale real estate investors, regardless of their actual exposure to this highly specific real estate sector.
What are the expectations for 2026?
This week's price pressure stands in sharp contrast to how the major private-market platforms themselves view the coming years. Despite the noise around liquidity, politics and sentiment, Brookfield, KKR and Apollo Global Management paint a remarkably consistent picture of 2026 as a transitional year, not a breaking point.
The era of cheap money and automatic multiple expansion is behind us, but demand for long-term capital for essential infrastructure, energy and digital backbone is actually increasing. As a result, the source of returns is shifting from financial leverage towards underwriting quality, structure and operational execution.
In its 2026 Investment Outlook, Brookfield focuses primarily on where structural investment demand is actually heading. CEO Bruce Flatt explicitly names digitalisation, deglobalisation and decarbonisation as forces that translate into hard physical bottlenecks: power grids, data centres, logistics and energy infrastructure. According to Brookfield, these are not cyclical themes but assets with contractual cash flows and long durations that remain essential even in a lower-growth environment. This explains why Brookfield has increasingly relied less on multiple expansion in recent years, focusing instead on scale, operational control and predictability.
This view is further explored in a recent interview with Sachin Shah, CEO of Brookfield Wealth Solutions. Speaking with Paige Ellis on the YouTube channel In the Money, Shah discusses how private markets are shifting from an exclusively institutional domain to a broader core allocation, partly driven by the need for stable, long-term cash flows. Shah explains how private markets have proven their value for institutional investors over the past decades, and why those same strategies can now play a role in solving the growing pension challenge.
In its recent High Grading outlook, KKR focuses specifically on portfolio composition itself. Henry McVey and the investment team argue that the compensation for taking on extra risk has shifted: risk premiums (spreads) now offer less compensation for lower quality. Their response is “high grading”: moving up within existing strategies towards stronger borrowers, higher up the credit structure (more senior and secured positions) and stricter credit terms. KKR shows that this is not a flight from risk, but a deliberate choice later in the cycle, in which additional return should come primarily from selection and structure rather than market direction.
In its 2026 Outlook, Apollo mainly addresses sentiment around private credit. CEO Marc Rowan points out that the public debate often projects a small, volatile corner of leveraged lending onto a much broader market. According to Apollo, around $38 trillion of the credit market consists of high-credit-quality positions, largely held on the balance sheets of insurers and pension funds, while the riskier segment that dominates the headlines is only a fraction of that. Apollo also stresses that at Athene, more than 97% of the bond portfolio is investment grade.
Together, these outlooks show that the sector is not becoming more defensive, but more selective. Relying less on easy beta (following the market), and more on discipline, scale and execution. That is precisely where the largest, proven platforms have historically demonstrated their edge.
The situation at Blue Owl says mainly something about the dynamics of rapidly grown, semi-liquid structures at the edge of the market. This contrasts sharply with the more mature platforms, where recent quarterly reports actually show record inflows and continued demand for credit, infrastructure and energy strategies. There is no sign of a broad liquidity problem at players such as Brookfield, KKR and Apollo. The concerns about single-family homes also lack proportion: for the large platforms, this asset class forms only a marginal part of the total portfolio, while the core of value creation lies in infrastructure, energy, data centres and high-quality commercial real estate.
At the same time, we do not take the risks lightly. The growth of private credit inevitably makes private equity holding companies more sensitive to the credit cycle, especially as 2021–2022 vintages face (expensive) refinancings in the coming years. However, the distinction does not lie in the label "private credit", but in quality, structure and funding. This is precisely where the reason lies why these players are increasingly linking their models to long-term, insurance-like capital and to investment-grade-like exposures. Not out of caution, but because this offers the combination of stability and firepower.
Our conclusion for 2026 is not that private markets will become "defensive", but that the sector is entering a new phase. The period in which returns were mainly helped by cheap money and multiple expansion lies behind us. For 2026, we therefore expect above all a year in which the distinction between "narrative" and "business model" becomes more visible again.
Apollo Global Management, Brookfield & KKR are currently trading on the New York stock exchange at prices of USD 144.96, USD 48 and USD 134.87 per share, respectively.
"Constellation Software will keep beating the market"
The Canadian investment holding company Constellation Software (Toronto: CSU) has had an unfortunate year. Halfway through 2025, the software giant was still up a healthy 12%, but by 31 December the loss in local currency exceeded 25%.
Investors are worried that artificial intelligence will replace (part of) Constellation's software. In addition, iconic founder Mark Leonard was forced to give up the position of CEO for health reasons. We wrote about this extensively several times last year, as in the Deep Dive below.
Analyst Paul Treiber of RBC Dominion Securities is known as one of the leading followers of Constellation. Last week he gave a clear signal by reiterating his 'Outperform' rating for the acquisition machine and raising the price target to CAD 5,600. This new price target lies well above the Wall Street average of around CAD 5,080.
Treiber states that Constellation will likely continue to generate one of the highest returns within the universe of stocks that RBC covers, based on the company's ability to keep compounding capital through acquisitions, the strong underlying fundamentals, and the ROIC-based compensation structure for management.
RBC expects the Canadian technology sector to show healthy returns in 2026 that could potentially outperform the broader market. Whereas performance in 2025 was still sharply divided, with outliers such as Shopify and Celestica masking the underperformance of most software stocks, the bank expects the recovery in 2026 to be much more broadly based.
Treiber notes that the compression of valuation multiples in the software sector has likely reached its trough and that solid growth in revenue and operating profit will support returns in 2026. An important part of this view is the fading of fears surrounding artificial intelligence; RBC believes that valuation pressure from AI concerns is unlikely to increase further and may even ease as the tailwind that AI offers becomes clearer. The bank identifies Constellation Software as one of its top ideas for the coming year.
We endorse Treiber's view and have already flagged the software sector as a contender for 2026 in a recent Deep Dive, in which, among others, Constellation Software and its subsidiary Topicus.com are mentioned. You can read the rationale in the article below.
 Michael Gielkens
The positive view on Constellation is supported by the consistently strong results. In the third quarter of 2025, revenue grew by 16%, driven in particular by acquisitions. Operating cash flow even grew by 33%, confirming that the investment holding company's engine is running at full speed and that operating leverage is working excellently.
In client conversations during the fourth quarter, we also pointed to the consistently strong figures of Constellation and Topicus.com, from which no negative impact from artificial intelligence can be discerned so far. The share price correction of these companies is therefore attributable to sentiment, a so-called valuation correction.
A share price reflects two things: the profit or cash flow per share, and how much investors are willing to pay for it (the so-called price/earnings ratio or price/cash flow ratio). If the market's current valuation already sufficiently accounts for AI risk, the bulk of the valuation pressure should now be behind us. If cash flow keeps growing by more than 30%, investors will sooner or later have to reflect this in the share price as well.
Benjamin Graham, Warren Buffett's teacher, once put it aptly:
"In the short run, the market is a voting machine but in the long run, it is a weighing machine"
The recent fear that artificial intelligence undermines the competitive position of niche software companies is based on a fundamental misconception about where the real economic competitive advantage lies. After all, the value of these companies does not lie in the source code, which is easier to replicate using AI, but in their deep entrenchment in specific business processes and the high switching costs that result from this.
We therefore do not regard AI as an external disruptor, but rather as a productivity lever that enables established players to improve their margins and optimise their service delivery. We accordingly do not share investors' fear that the more than 1,400 subsidiaries of Constellation and the more than 200 companies of Topicus will be disrupted on a large scale. On the contrary, we see this as an excellent opportunity to further boost productivity.
Constellation Software is currently trading on the Toronto stock exchange at a price of CAD 3,311 per share.
Prosus warns of European investment climate
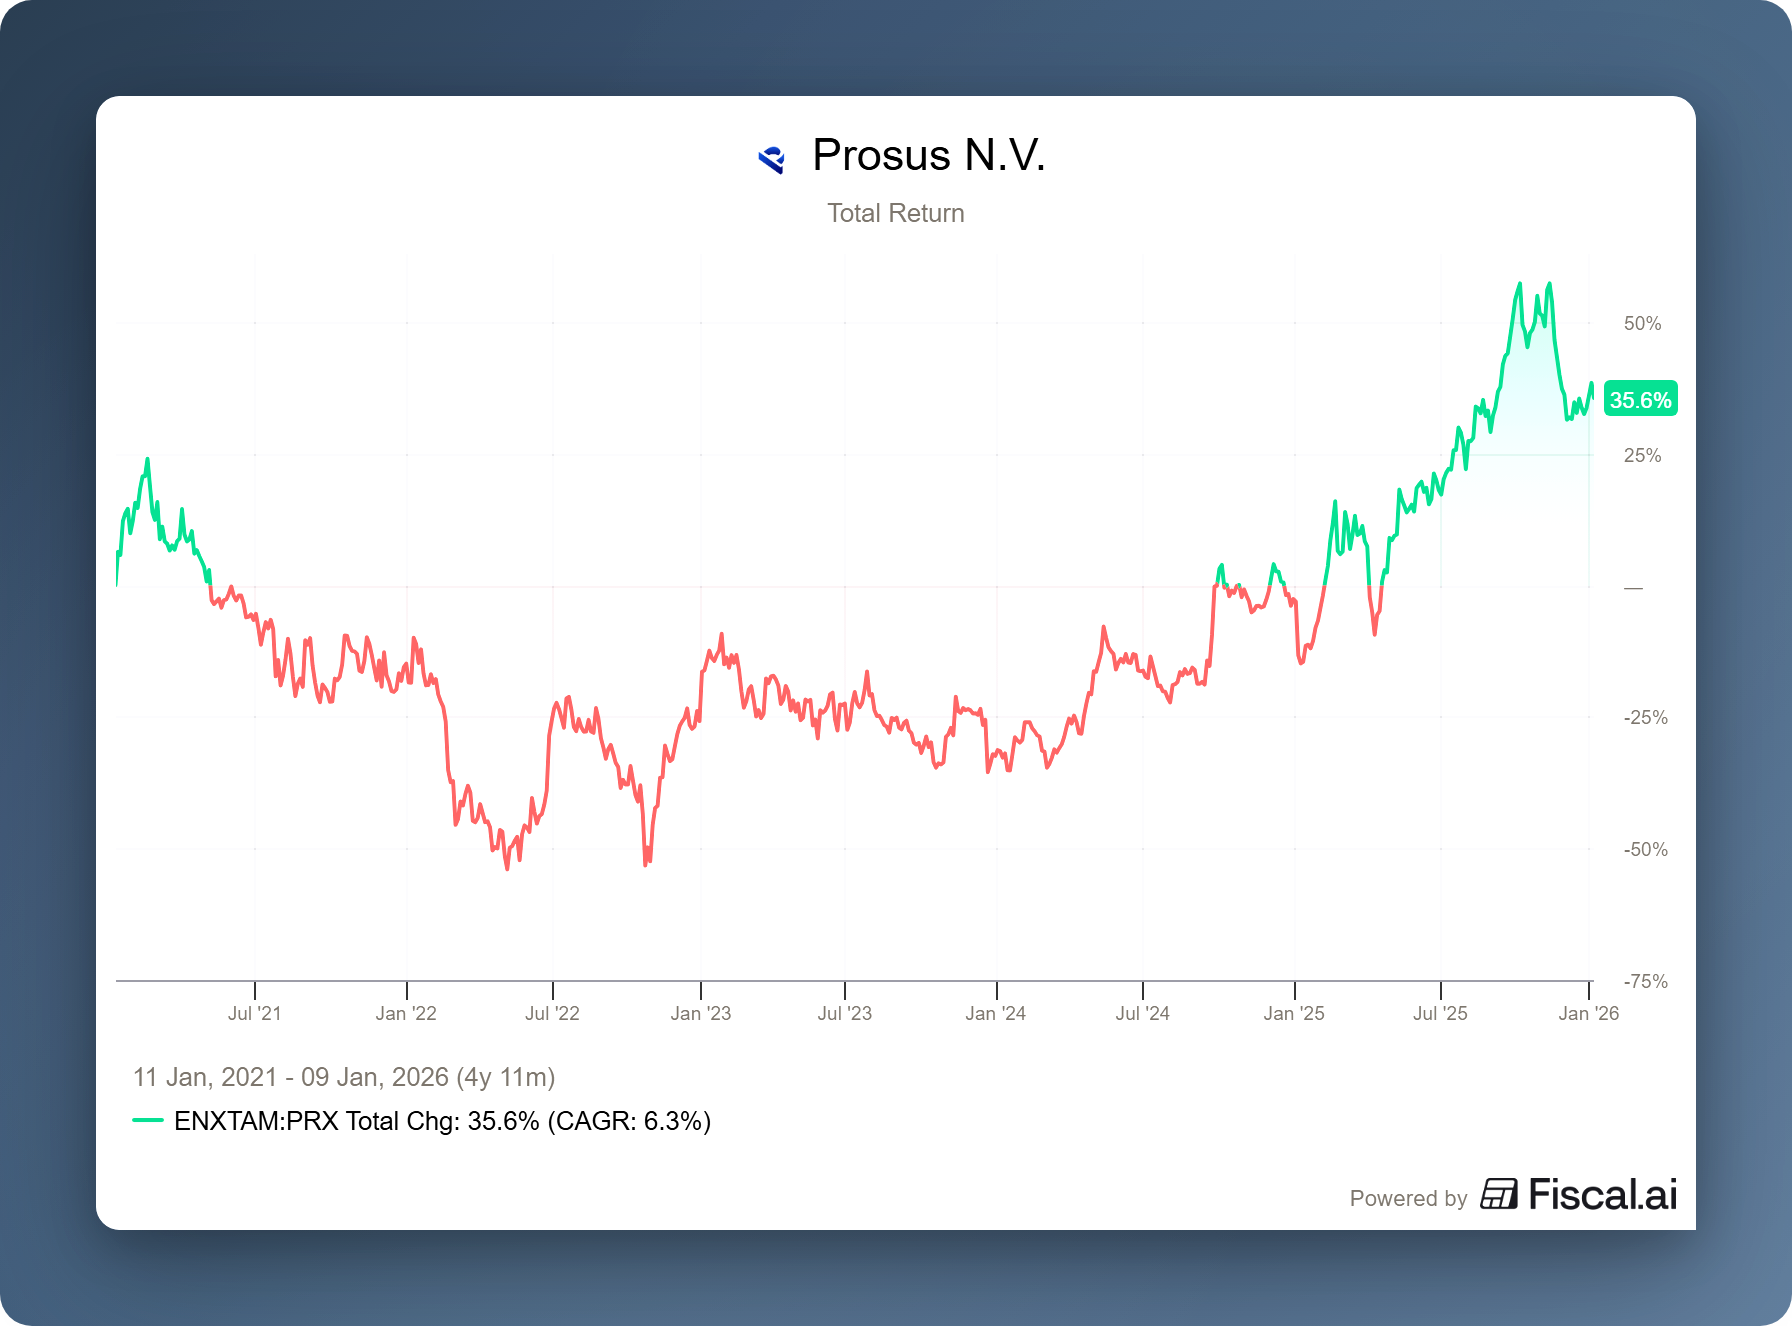
The Dutch investment holding company Prosus (Amsterdam: PRX) has voiced fierce criticism of the European competition authorities following its recent acquisition of Just Eat Takeaway. The regulator only gave the green light for the EUR 4.1 billion deal after Prosus committed to fully divesting its 27% stake in competitor Delivery Hero.
CEO Fabricio Bloisi states in the Financial Times that this forced sale thwarts his plans to invest USD 15 billion in the continent. The aim was to forge a European tech giant with a valuation of USD 100 billion, but current regulation, he says, makes this impossible.
According to Bloisi, this course of events runs directly counter to Mario Draghi's recent report. In it, Draghi argued precisely for looser rules to allow European champions to compete with American and Chinese rivals.
Prosus is currently trading on the Amsterdam stock exchange at a price of EUR 53.78 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts of it, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to make use of investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or on behalf of their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your investment. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is indicative only and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



