
Deep Dive: Software and Private Equity in the Grip of Artificial Intelligence
The narrative that AI will fundamentally disrupt existing business models has, in a short period of time, led to substantial share price movements. Where previously we could speak of healthy caution towards technological disruption, we have now arrived at a phase of total irrationality.


Financial markets showed a remarkable sentiment last week. The market is currently dominated by fear over the potential disruptive impact of artificial intelligence. The narrative that AI will fundamentally disrupt existing business models has, in a short space of time, led to sharp price movements. Where previously we could speak of healthy caution regarding technological disruption, we have now entered a phase of total irrationality. It seems that investors are judging first and only checking the facts afterwards.
An almost tragicomic example of this sentiment concerns the case of Algorhythm Holdings. This "penny stock", with a market capitalisation of barely USD 6 million that until recently sold karaoke machines, published a press release (which, according to experts, was incidentally full of unfounded claims) about a new AI tool. What followed was a shockwave that wiped out billions in market value at established global players in the logistics sector. Companies such as DSV and C.H. Robinson, which form the backbone of world trade, saw their share prices collapse. If a former karaoke manufacturer claims that AI can automate logistics, then the moats of these multinationals are apparently worth nothing anymore.
The voting machine is working overtime
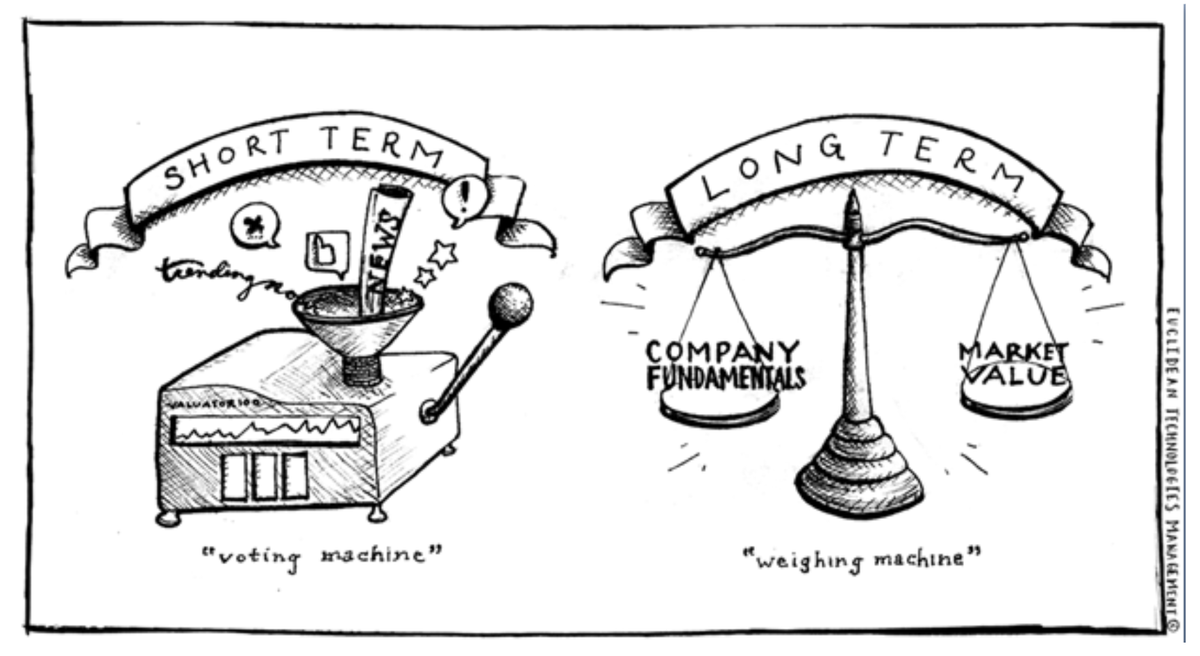
Our view at Tresor Capital has always been that, in the short term, sentiment determines share prices, but that over the longer term fundamental developments rise to the surface. Benjamin Graham, the teacher of Warren Buffett, once stated that in the short run the market is a voting machine, but in the long run it is a weighing machine. Over periods of several months to a year, sentiment can be dominant. But as more information filters through in the form of quarterly results, customer behaviour and strategic choices, perceptions are either confirmed or disproved, and economic reality eventually translates back into valuation and share price.
What we have seen in recent weeks is essentially a sorting of sentiment. It appears that hedge funds are currently working with baskets of AI winners and AI losers. Sectors regarded as safe are being bought up. Sectors labelled as "at risk" are being sold off. Anything that falls even remotely into the "AI disruption risk" category is being collectively sold, without any distinction in business model or customer relationships. That, in the first instance, says more about perception than about fundamental deterioration.
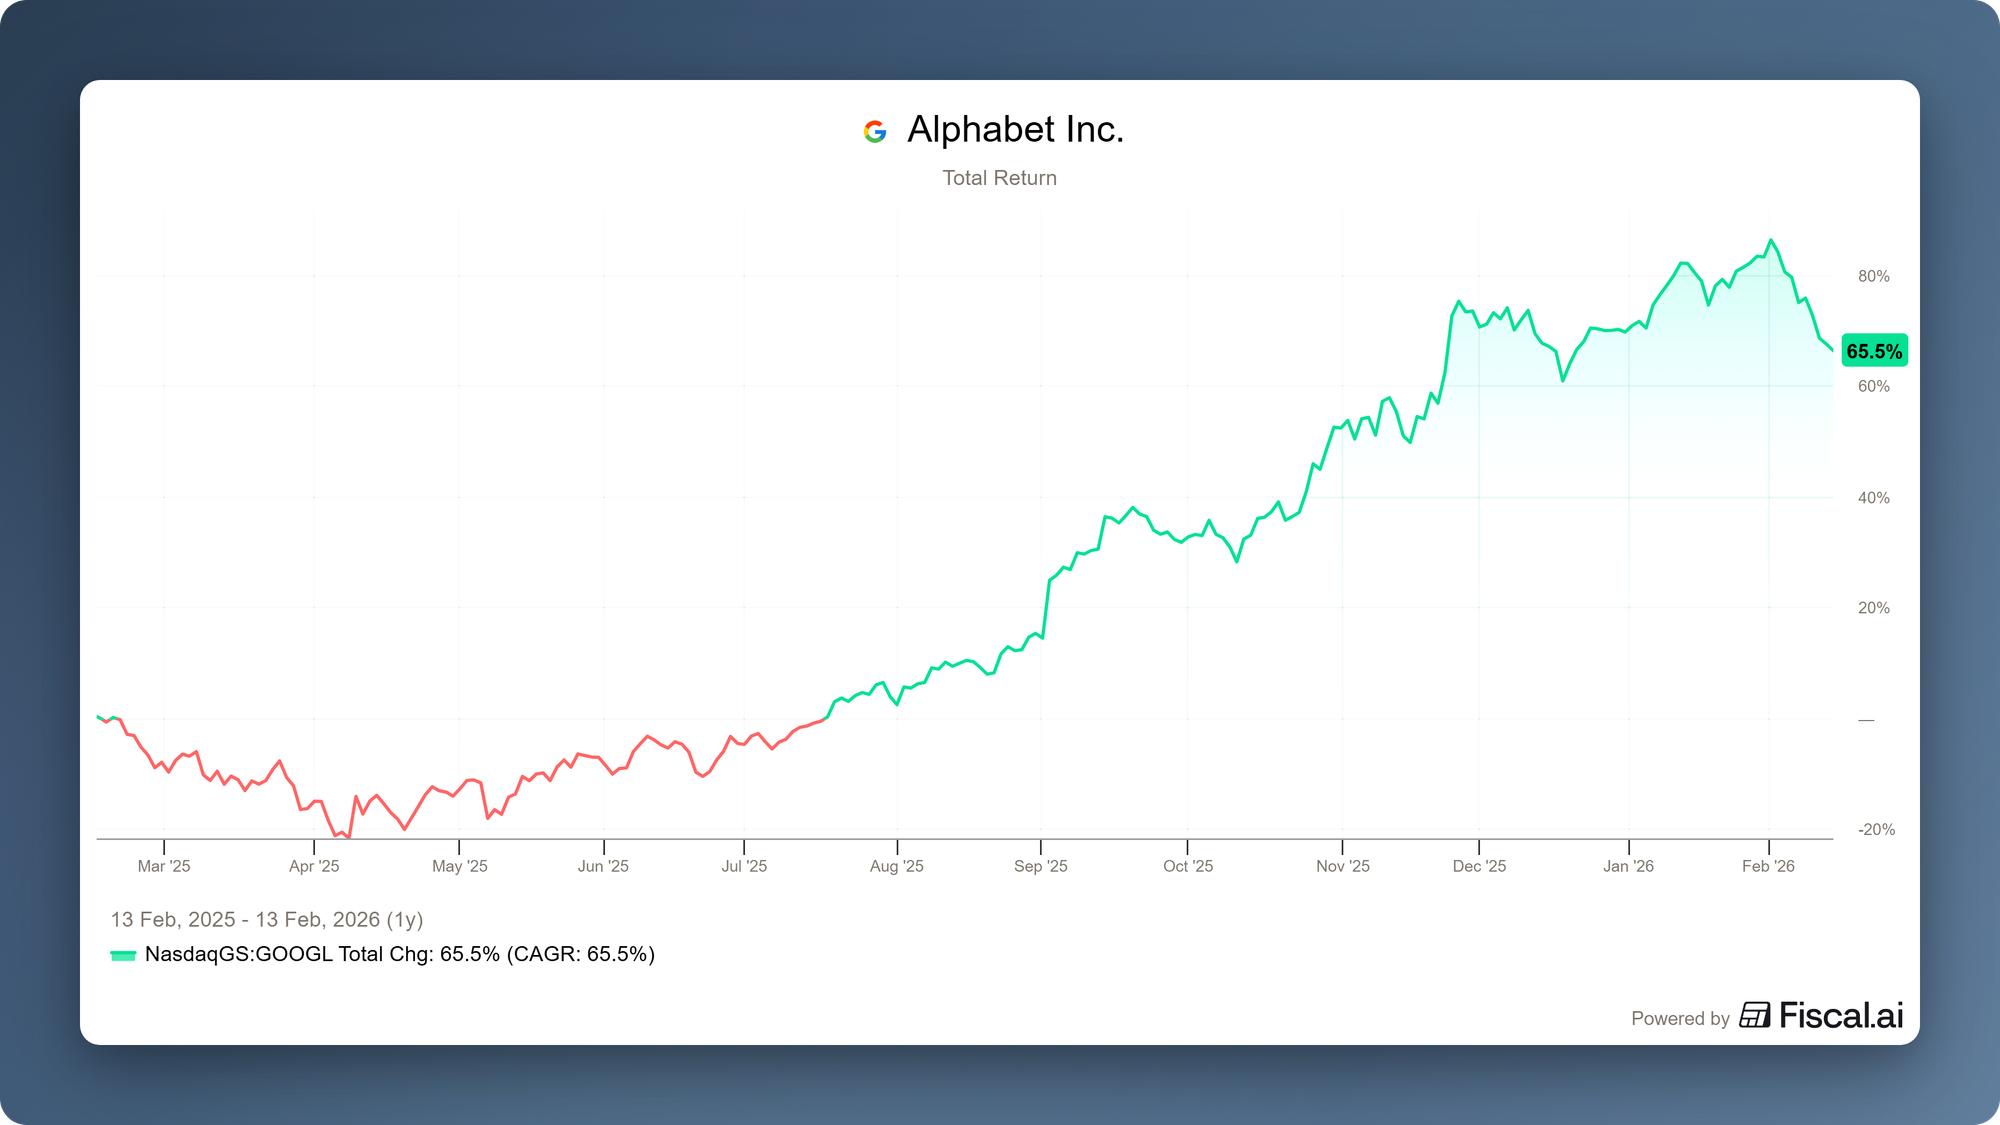
The most striking example of this mechanism is Alphabet. In 2025, the share price was pushed down to below USD 150 on fears that ChatGPT would structurally undermine traditional Google Search, Alphabet's cash cow. The dominant narrative was that generative AI would render the search model redundant. We gladly took advantage of this by taking a position in the American technology holding company for our clients. A few quarters later, the picture flipped completely. Alphabet was suddenly seen as an AI winner, with an integrated stack of its own data centres, the Gemini model, a strong cloud position and unmatched distribution through Google Search, Android on Samsung devices, and integration on the iPhone through agreements with Apple.
In less than twelve months, investors drove the share price from below USD 150 to above USD 300. The company had not become 100 percent more valuable in that period, but sentiment had turned 180 degrees. First investors were too pessimistic, then the quality of the business model was recognised again. It shows how dangerous it is to base investment decisions on the loudest story of the moment.
Private equity and the memory of Brookfield
We now see that same mechanism playing out more broadly, particularly in software and among private equity players with exposure to this sector. The market is projecting the same doom scenario onto the software sector, and thereby directly onto private equity. EQT, a subsidiary of Investor AB, has a relatively large allocation to software companies, at around 19% of fee-paying assets. KKR has around 7 percent of its assets under management in software, and Brookfield less than 1 percent. Yet we see that the share prices of these players sometimes fall much more sharply than their actual exposure would justify. That points to an overreaction.
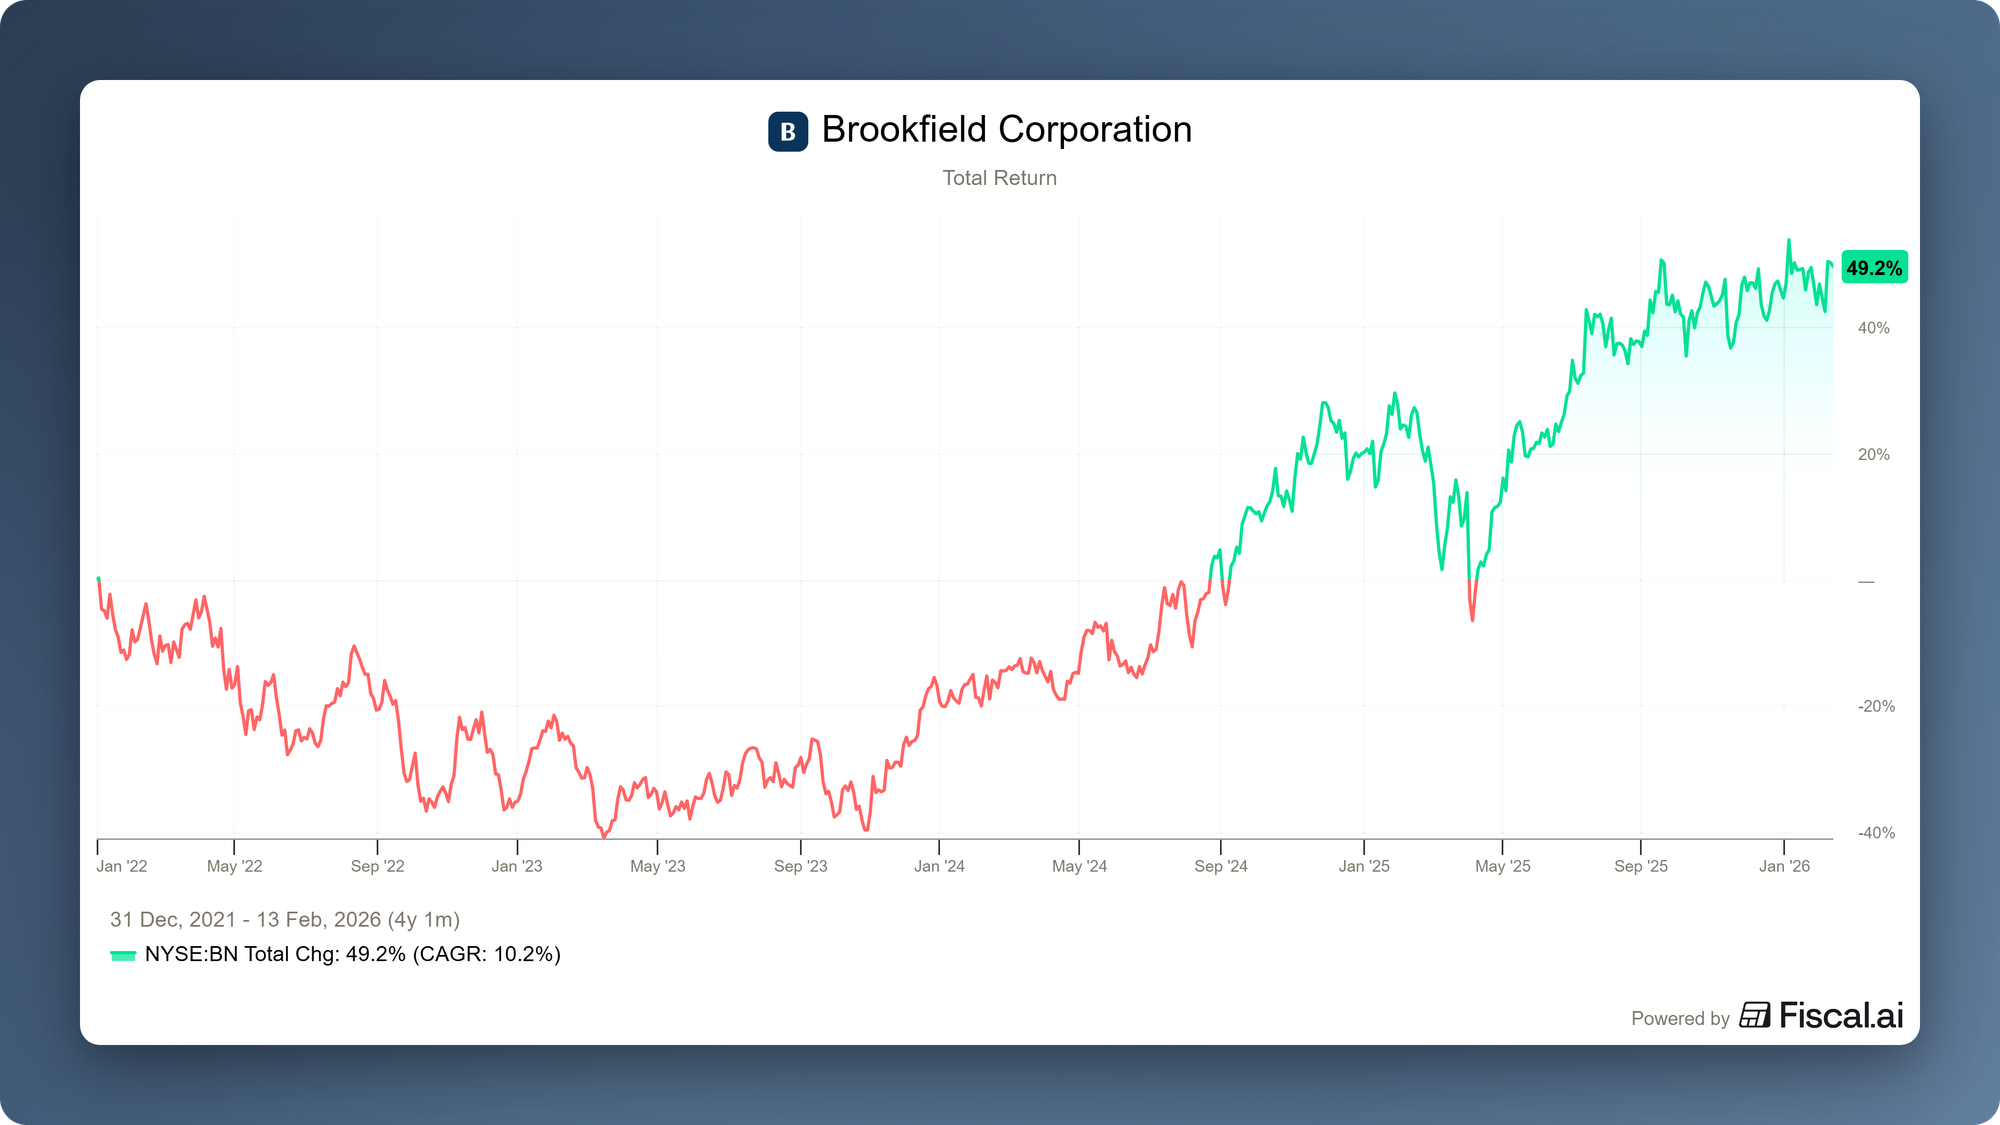
We saw this before with Brookfield during the coronavirus period. At that time, virtually no value was assigned any longer to the company's iconic real estate portfolio, with high-quality offices and shopping centres in prime locations worldwide. Investors acted as though we would never go back to the office again, and never go back to the mall to shop again. Brookfield stated at the time that office work remains essential for culture and collaboration, and that clients actually wanted to rent extra space in top locations. Nevertheless, sentiment was negative and the stock was sold off en masse. Once again, we bought Brookfield shares heavily for our clients at the time. Not long after, the share price recovered to record levels. What was presented as structural disruption turned out to be largely sentiment. The current software fear shows exactly the same characteristics of exaggeration.
Insiders are buying heavily
While the market is selling in a panic, the people with the deepest insider knowledge are doing the opposite. They are buying. It emerged last week that Investor AB, the investment company of the Wallenberg family and co-founder of EQT, has bought a substantial additional stake in EQT shares worth SEK 657 million. That is roughly EUR 58 million. They clearly do not see the share price fall as an existential risk, but as a buying opportunity.
We saw another insider transaction at KKR. Timothy Barakett, a board member at KKR, bought no fewer than 50,000 additional shares on 9 February. The total value of this transaction came to USD 5.2 million. When an insider with that kind of financial insight, who knows exactly what is in KKR's books, puts more than USD 5 million of his own money to work, that is a signal we cannot ignore.
"Insiders sell for all kinds of reasons. They want to buy a new vacation home. They want to send a kid to college. But they only buy for one reason, which is they think the stock is going up."
Peter Lynch
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
The shovel and the hamster wheel
Akre Capital Management, one of the most respected long-term investors and a major shareholder in both Constellation Software and Topicus, also made itself clearly heard in a letter to investors dated 6 February 2026. They acknowledge the pain of the recent declines, but their conviction remains undiminished. Akre uses a fitting metaphor here. If a super-powerful new shovel is invented, more people might start digging in their back garden, but the biggest beneficiaries are the actual mining companies that already own the mines. In this case, the VMS companies are the owners of the mines, in other words the data and the customer relationship.
Akre also points to the hamster wheel of continuous development. Software is never finished. AI may help with writing code, which currently makes up around 20 percent of the work, but the remaining 80 percent consists of maintenance, integration and customer-specific adjustments. The CEO of SAP recently confirmed this, stating that they are winning deals thanks to AI, not losing them.
Not all software is equal
It is essential to distinguish between generic horizontal software and vertical market software (VMS). On the stock market, virtually all Software-as-a-Service (SaaS) currently appears to be under pressure, from Adobe to Salesforce to SAP. These are large, broad platforms with generic applications. VMS, by contrast, is developed in close collaboration with customers within specific niches. Mark Leonard of Constellation Software put it aptly by stating that software is the result of ongoing conversations between customer and developer. The product is the answer to very specific requirements within a particular sector. That creates high switching costs and deep integration into the core processes of organisations.
Moreover, replacement is in many cases not even realistic. The niche markets in which VMS operates are often too small and too specialised to be attractive to enter, even now that development barriers have become lower. For hospitals, governments and other critical public services, reliability, security and uptime weigh many times more heavily than price or interface. Continuity and risk management are central. That principle does not change fundamentally because of AI.
The myth of savings
In conversations with our contacts within vertical market software companies and with clients who develop or use software, we hear a consistent message. Companies do not intend to build their entire software system single-handedly. Nor will they tear down their existing, deeply integrated systems in order to save a cost item of one to two per cent of revenue. That is not economically rational. AI is primarily seen as a means of optimising existing processes, not of replacing business-critical infrastructure.
"Excellent open-source alternatives to CRM systems and design software have been freely available for years. Yet companies overwhelmingly choose to pay for commercial solutions."
The argument that AI makes software development easier and thereby renders existing providers redundant should be put into perspective in that light. Excellent open-source alternatives to CRM systems and design software have been freely available for years. Yet companies overwhelmingly choose to pay for commercial solutions. Not because the free option is technically inadequate, but because with a paid solution one outsources responsibility and risk to a specialised party that is accountable for maintenance, security and continuity. It is about trust and stability, so that the company can focus on its core business.
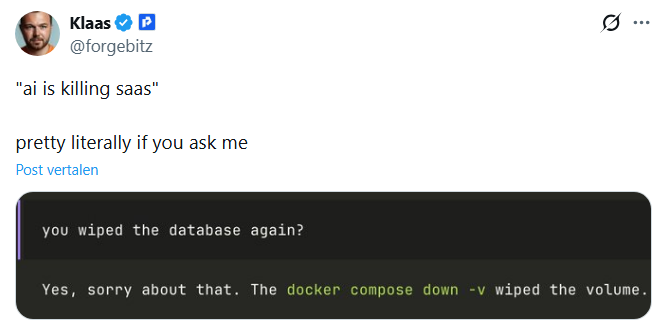
This is illustrated in a humorous but painful way in a recent post on X by user Klaas. He shares an interaction with an AI agent that asks whether the database has been wiped again, whereupon the developer has to admit that the AI accidentally deleted the volume. It perfectly illustrates why companies are wary of simply letting autonomous AI loose on their critical infrastructure.
The view of the tech giants
The architects of the AI revolution themselves confirm this view. During the recent quarterly earnings discussion, Sundar Pichai, CEO of Alphabet, was crystal clear about the impact of AI on software. He sees no hollowing-out, but rather integration. Google Cloud's largest customers integrate models such as Gemini deeply into their workflows to make their own products better. According to Pichai, AI is a tool that widens the moat of existing software companies.
Jensen Huang, the head of NVIDIA and perhaps the most influential voice in the AI world at present, also called the idea that AI would replace the software industry the most illogical thought in the world. According to him, software is not an end product that disappears, but the fundamental building block on which AI runs. After all, computing power is worthless without the applications that translate that power into usable solutions for the end customer.
Innovation and security from Europe
Constellation Software proved this week that VMS companies are not standing still, with the announcement of a new AI tool. This is one of the many AI developments we have seen recently within our VMS companies, which confirms that these companies are in fact very active in adopting new technology in order to serve their customers better.
 Michael Gielkens
Another crucial aspect that is often forgotten in the current discussion is data sovereignty and security. This is a theme we covered extensively in our Deep Dive of 30 January, and it is now being confirmed in practice. Topicus recently won a prestigious tender from the Association of Netherlands Municipalities (VNG). With this, municipalities are collectively choosing Topicus KeyHub's software to secure their digital access and security. Governments and public institutions simply cannot afford to partner with unproven AI start-ups that may process data outside Europe. They choose parties they trust and that meet the strictest European requirements. As we analysed earlier, Topicus responds to this by using European data centres and European AI models. The real competitive advantage here does not lie in the code, but in the guarantee that the digital keys remain in trusted, local hands.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Conclusion
While we agree that artificial intelligence is groundbreaking and will change the world, mainly through higher productivity, we remain level-headed. In almost every year, some company or sector in our portfolio comes under pressure. That is inherent to financial markets. A wholesale sell-off of a sector is often more a sign of a sentiment-driven overreaction than of a fundamental implosion.
Has the so-called terminal value of some software companies become more uncertain as a result of AI? Yes. Technological acceleration by definition increases uncertainty about very long-term scenarios. In that sense, a correction in valuations is justified. But what we are seeing now goes beyond a rational revaluation. The correction has turned into broad-based panic in which everything that smells of software is being sold off collectively, regardless of the nature of the business model. An obscure karaoke producer wiping out billions in market value with a single press release shows just how far the current sentiment has swung.
Interestingly, retail investors appear less susceptible to these panic narratives than professional hedge fund managers. Data from Reuters shows a record inflow of retail money into software stocks. That may well contribute to a turn in sentiment, but ultimately it will be the fundamentals - in the form of company results and evidence that VMS companies are actively integrating AI - that will have to drive the actual shift in the narrative.
As always in financial markets, it is unwise to move with the panic. In the short term, sentiment dominates; in the long term, fundamental value rises to the surface. Ultimately, cash flows, customer relationships, competitive advantages and strategic positioning will weigh more heavily than the narrative of the moment. Precisely in times when emotion takes over, it is essential to keep looking rationally at the facts as they stand. That is the foundation on which sustainable value creation rests.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts of it, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to take up investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or on behalf of their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance is no guarantee of future results. You may lose (part of) your invested capital. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



