Economy & Markets #48 - How a butterfly in Japan can cause a whirlwind in Brussels

This week's topics:
Calm cautiously returns to Wall Street
Over the past two weeks, the S&P 500 and the Nasdaq found renewed support following the sharp correction earlier in November. The main driver behind the recovery is the markedly increased expectation that the Federal Reserve will already cut interest rates in December. Both John Williams, president of the New York Fed, and Governor Christopher Waller stressed that the labour market is cooling and that inflation is moving towards target, which in their view leaves room for a 25 basis point rate cut. The market-implied probability of such a cut has since risen to around 85%, a remarkably swift shift compared with the previous week. Volatility has fallen sharply as a result: the VIX dropped from a peak of around 26% to roughly 17%, pointing to calmer market conditions and a greater willingness among investors to take on risk.
Asia's butterfly effect
Last week we wrote about the rapidly deteriorating financial position of the Japanese government. Yields there are rising sharply and the Japanese yen is weakening at a rapid pace. Gross government debt now stands at more than 240% of GDP. However, when we look at the net position, which corrects for the state's substantial financial assets, it comes out at a much lower level of around 76% of GDP. This difference is partly explained by the fact that the Japanese Ministry of Finance itself has bought up a large share of government bonds. In addition, Japanese pension funds and the country's extensive domestic savings are among the largest in the world.
Looking at other countries facing similar structural challenges (demographic decline, rising social spending and the risk of higher interest rates), it is not inconceivable that the dynamic we are now seeing in Japan could eventually spread to countries such as Belgium, France or even Germany. This is a striking example of the so-called butterfly effect: a seemingly local disturbance in Asia can ultimately lead to a much larger shock in Europe.
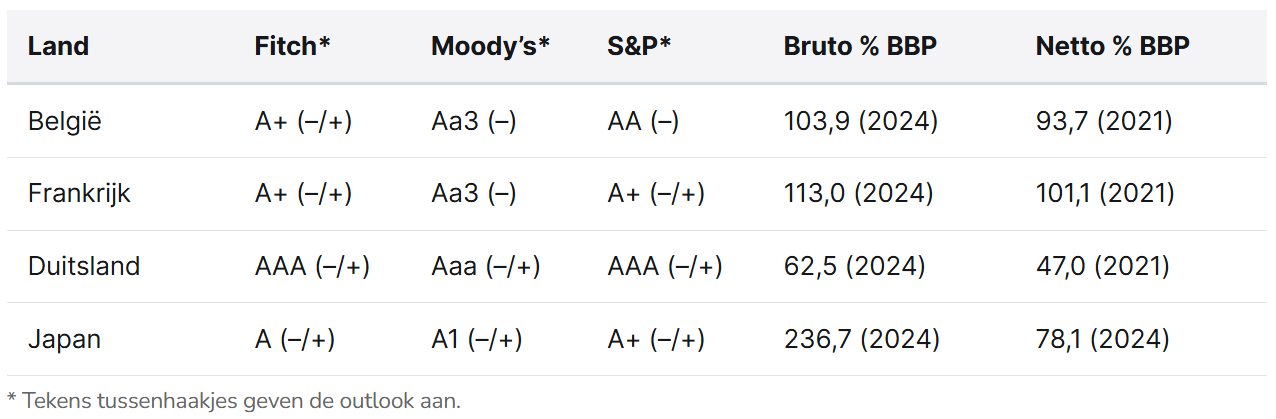
Belgium's gross government debt stands at around 104% of GDP in 2024. An official calculation of net government debt is lacking, apart from an estimate from 2021, which makes it difficult to form a nuanced assessment of the true debt position. At the same time, budget deficits remain stubbornly high: a deficit of around 5.5% of GDP is expected in both 2025 and 2026. It is therefore unsurprising that the De Wever government is coming under increasing pressure from the capital markets to push through structural reforms.
Bart De Wever's reform agenda
This week, prime minister Bart De Wever presented a new agreement to reduce the budget deficit in 2026 and 2027. The package consists of a combination of tax increases and targeted savings. For instance, taxes on share transactions, airline tickets and natural gas will rise, an additional bank levy will be introduced, and various areas of government spending will be more strictly curbed.
In addition, the socio-economic measures from the summer agreement of 2025 are being implemented at a faster pace. These include labour market reforms, tax adjustments and a revision of the unemployment benefit system, under which the duration of benefits will be shortened to boost labour market participation.
Notably, unlike Germany and France, Belgium is also taking steps to rein in future pension costs. From 2027, anyone wishing to retire early at the age of 63 will need to show at least 42 years of career history, with each year counting 156 worked or equivalent days. Anyone who does not meet this condition but still retires early will receive a reduced benefit, in proportion to the number of years by which they retire early.
Table – New taxes and fiscal measures for investors (private & corporate)
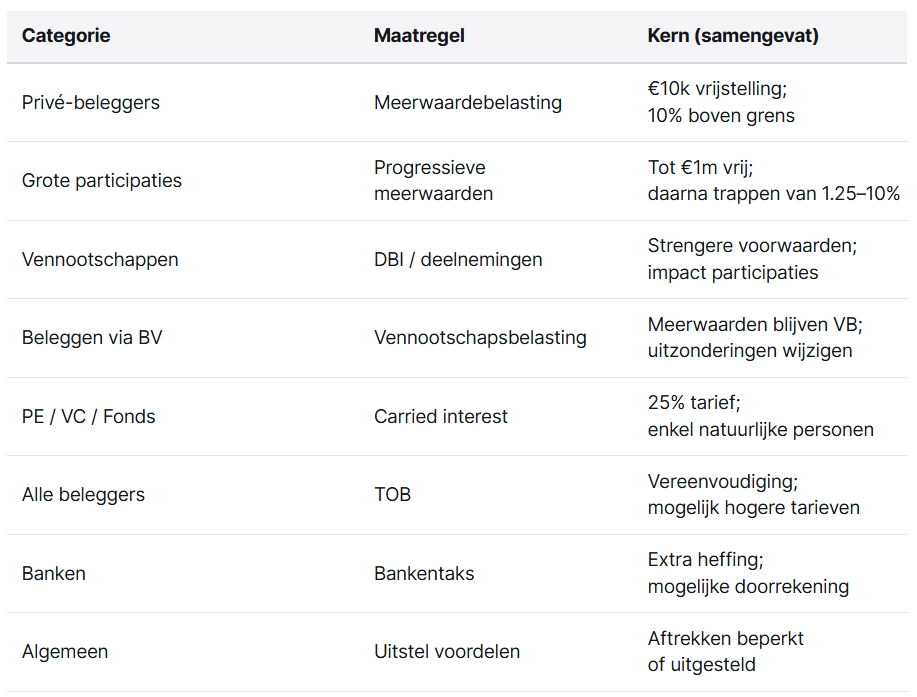
According to the government, total savings of €9.2 billion should cover a substantial part of the deficit. Still, it remains uncertain whether this will be enough to bring the deficit back below the European budgetary norm of 3%. After all, part of the planned revenue depends on behavioural responses from citizens and businesses. For example, there is a risk that private individuals will trade less on the stock market, which could cause the revenue from the stock exchange tax (TOB) to fall short of projections. For other measures too, it remains uncertain whether the expected revenues will be fully realised.
Is political crisis looming in Germany?
Do you remember how European stock markets rallied earlier this year when Germany announced large-scale investments and reforms? Chancellor Friedrich Merz now finds himself in a political crisis, however: his own party's youth wing within the CDU is blocking the pension plan intended to secure benefits until 2031.
It is hardly surprising that the pension issue is turning into a structural risk for the European project. Like France's, the German system operates on a pay-as-you-go basis: current pensions are funded from the tax revenues of working people, without the support of accumulated reserves. As the population ages, this model is coming under ever greater strain. Within the CDU/CSU, younger members accuse Merz of opting mainly for delay rather than genuine reform, and of continuing to avoid the necessary structural measures. His reputation as a "great reformer" is eroding further as a result; there is a growing risk that, like former chancellor Angela Merkel, he will go down in history as someone who put off major economic problems for too long. This is putting the government's political stability under pressure.
The investment plans for more than €500 billion in infrastructure and defence, equivalent to roughly 15% of German GDP, are also being delayed as a result. Combined with the fact that the German economy has now been in recession for three years, this shows just how quickly the political and economic climate in Germany can shift, and not in a positive direction.
The Bitcoin correction and the self-reinforcing effect around MicroStrategy
Bitcoin has corrected sharply over the past two months, falling from around US$126,000 to a range of US$80,000–90,000. This decline coincided with outflows from spot ETFs, broader risk reduction across financial markets, and heavy liquidations in the derivatives market. Together, these factors weakened intraday liquidity and accelerated the downward price action.
An additional source of pressure comes from companies with large Bitcoin positions, particularly where those positions have been built up with borrowed money and Bitcoin itself serves as collateral. MicroStrategy is the best-known example. In recent years, the company has issued several tranches of debt and used Bitcoin as a strategic balance-sheet instrument within its financing structure. CEO Michael Saylor once summed it up succinctly: "We are a leveraged long Bitcoin operating company."
This model works excellently in times of rising prices, but vulnerability increases rapidly during sharp declines. When the value of the collateral (Bitcoin) falls, lenders may demand additional security. If that is not available, there is a risk of forced sales, which can intensify price pressure precisely during downward markets. This dynamic applies more broadly to companies that combine leverage with digital assets, and in volatile periods it acts as an accelerator of downward moves.
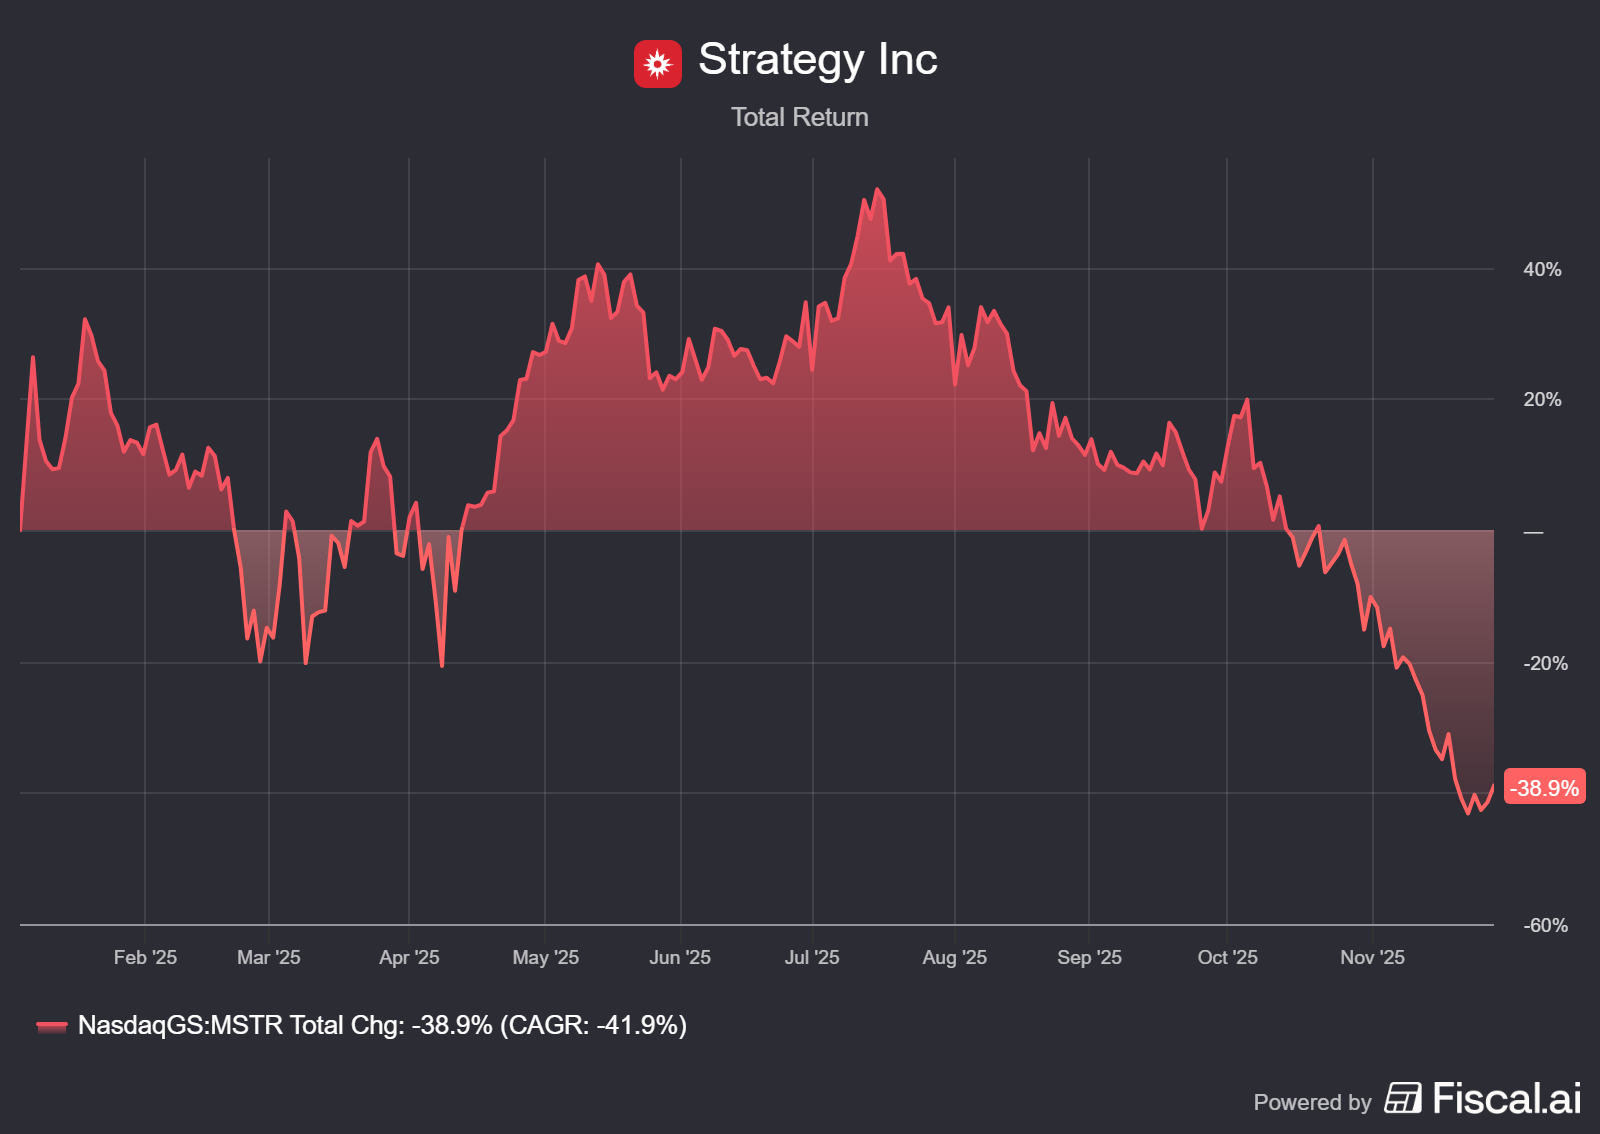
MicroStrategy shares have fallen by around 41% this year, and given the recent price action, the stock risks losing its place in certain equity indices. Such an index removal could trigger forced selling by ETFs and index funds, which would again put additional pressure on the share price. A lower share price also reduces MicroStrategy's ability to raise new capital through share issuances, making the company even more dependent on Bitcoin-related collateral.
This creates a self-reinforcing mechanism:
A lower Bitcoin price depresses the value of the collateral → this increases financing pressure → which leads to possible forced sales → which puts further pressure on the Bitcoin price → causing MicroStrategy's share price to fall again.
A fragile equilibrium, especially in an environment where both market risks and liquidity shocks can turn quickly.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services? Feel free to get in touch.
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted with prior written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information must therefore expressly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to take up investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or on behalf of their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance offers no guarantee for the future. You may lose (part of) your original investment. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was originally written in Dutch and automatically translated into English with the help of AI. In case of any difference, the Dutch original prevails.