Economy & Markets #49 - Europe splits on pace and vision

This week's topics:
Swiss voters choose a different path from the British
The Swiss vote four times a year in binding referenda on national, regional and local political proposals. Last weekend's agenda included, among other things, a proposal to tax inheritances above CHF 50 million at fifty percent and use the proceeds for sustainability purposes. The outcome raised eyebrows across Europe, as the proposal was rejected by an overwhelming majority. At first glance this seems to defy all logic: only a fraction of the Swiss population holds wealth of that magnitude. If every voter had simply followed their own personal interest, this proposal should mathematically have secured an enormous majority. Yet eight in ten Swiss voted against it. That choice says a great deal about how differently taxation, growth and prosperity are viewed across Europe, and about whether limits can be placed on the costs of the energy transition.
In countries such as Belgium, Norway and the United Kingdom, the political debate quickly turns to new wealth taxes as soon as the affordability of the social welfare state and the energy transition come under discussion. The Swiss population takes a clearly different and less ideological approach. Taxes are levied to a large extent at municipal level, which means Swiss municipalities compete with one another to remain fiscally attractive. As a result, local residents quickly grasp that beyond a certain point a higher tax rate actually yields less. The Laffer curve is therefore not an academic or theoretical discussion in Switzerland; at local, regional and national level, there is a clear awareness that tax revenues fall once the tax burden becomes too high.
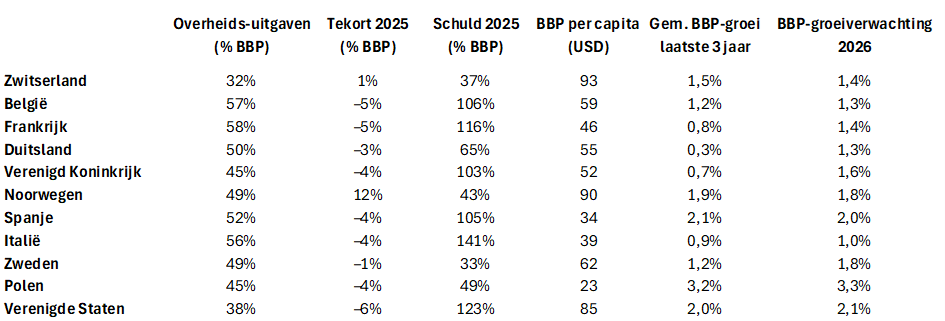
Whereas the American economist Arthur Laffer worked in the 1970s and 1980s as an adviser to President Reagan on determining the optimal tax level for maximising revenue, the American economist Richard Rahn serves as an important reference point for classical liberals. Rahn argues that once total government spending exceeds 25% of GDP, this begins to hold back a country's economic development. The Rahn curve is admittedly a more theoretical model. Many economists warn that the "optimal" level of spending depends heavily on how the money is spent (infrastructure, education, social security, etc.), but looking at how government debt keeps structurally rising, one could well argue that Swiss citizens are (consciously or not) applying the theories of Rahn and Laffer to preserve prosperity for future generations as well.
The table below offers a rough picture of how different countries are positioned. We recognise that fully consistent data is scarce, but a clear trend can nonetheless be observed. With the rising costs of ageing populations and the social welfare state over the coming decades, the table gives a clear indication of where, as investors, we can expect economic dynamism (but also rising debt and an ever-higher tax burden for businesses and consumers).
That dynamic was again visible in practice this week. Lakshmi Mittal, the founder of ArcelorMittal and one of Europe's wealthiest industrialists, announced last weekend that he is leaving the United Kingdom. According to the Sunday Times Rich List 2025, Mittal (75) has an estimated fortune of £15.4 billion and has been a fixture of British business life since 1995. He is also known for his substantial donations to the Labour Party during the Blair and Brown years.
The news follows the Labour government's controversial tax reforms, including the restriction of the 'non-dom' regime and possible tightening of inheritance and wealth rules. An estimated 11,000 wealthy entrepreneurs and high-net-worth individuals left the UK in 2024, and in 2025 the count already stands at around 17,000.
The fact that entrepreneurs of precisely this scale, wealth and international influence are leaving underscores how sensitive wealthy families and investors are to deteriorating fiscal conditions, and how quickly capital can flee once a country structurally loses its competitiveness.
Polish economy continues to impress
It is not only ultra-high-net-worth entrepreneurs who are leaving the United Kingdom; increasing numbers of Poles who previously emigrated to the UK as low-cost labour are also returning now that the economic outlook in Poland is becoming more attractive. In that respect, the Polish economy continues to impress. In the third quarter of 2025, the country grew by 3.7%, well above the EU average of 1.5%. This puts Poland among Europe's fastest-growing economies. Within Central and Eastern Europe too, the country clearly outperforms its neighbours: the Czech Republic posted growth of 2.7%, while Hungary managed only 0.6%. The main driver behind this lead is strong domestic consumption; Polish households continue to spend freely.
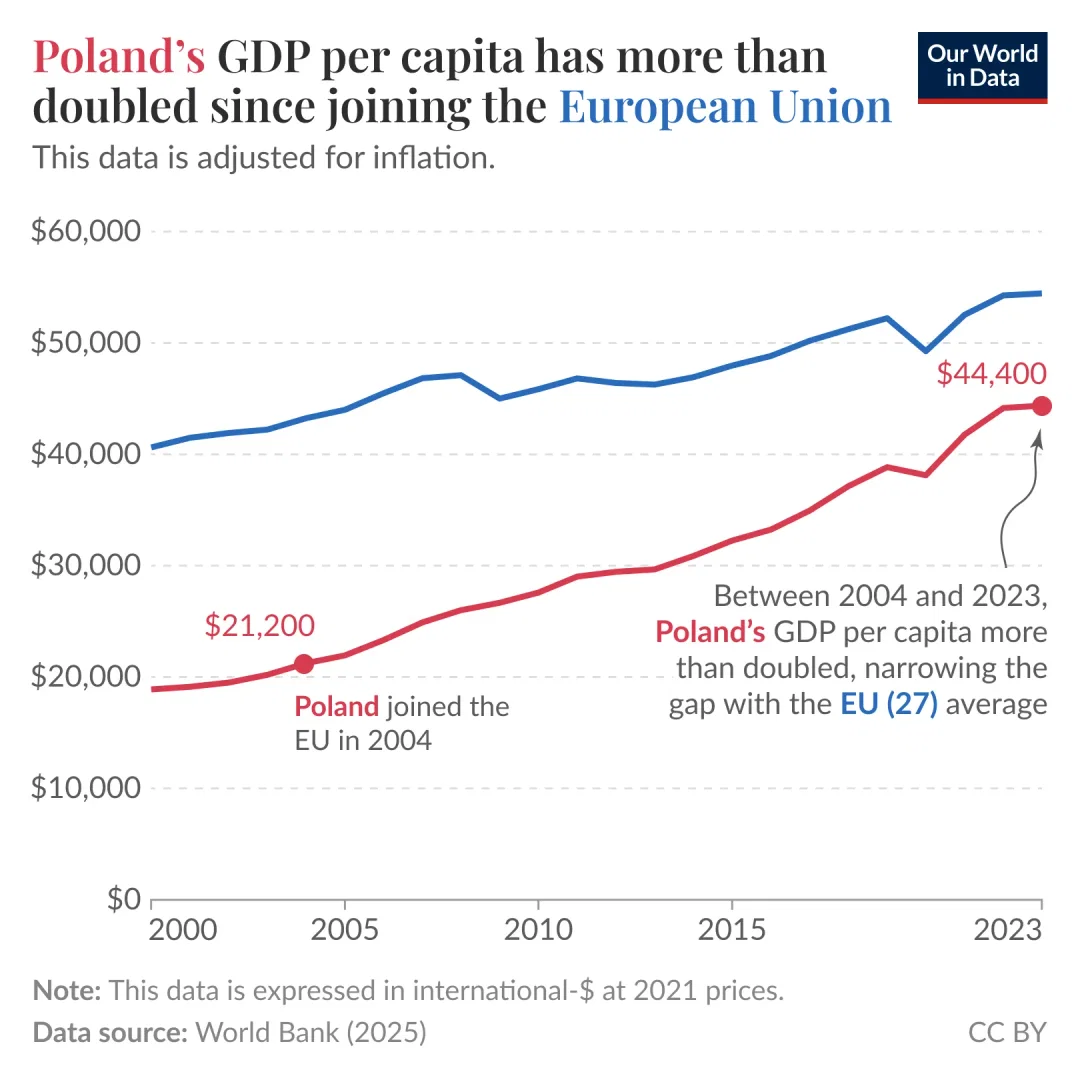
Although investment is lagging due to the slow disbursement of European funds, this is barely holding back the economy. Sector-wise, Poland shows broad resilience: industry is slowly climbing out of a slump, retail continues to grow, and the services sector is once again the main driving force. Only construction is under pressure, as is the case in many other European countries.
Compared with Europe's largest economies, the contrast is becoming ever clearer. Germany shows barely any growth, France remains below one percent, and Italy rarely exceeds that level. Even Spain, which is performing relatively solidly, is growing significantly slower than Poland. Poland's economy is thus not merely growing faster, but structurally stronger than most Western European countries.
Macroeconomically, Poland is also on solid footing: the current account deficit is limited, inflation is close to target, and the economic fundamentals look stronger than in many EU member states. The outlook remains positive. Growth of around 3.5% is expected for 2025 and a little over 3% for 2026, which means Poland is expected to once again rank among Europe's fastest-growing economies. Once the investment resources from European funds are fully activated, this could provide an additional boost on top of already strong domestic consumption.
It is therefore no surprise that this macroeconomic strength is finding its way to the stock market. In 2025, the broad WIG index (the Warsaw stock exchange) is up by around 28.6%, while the twelve-month return stands at around 36.8%. These results reflect strong investor sentiment, underpinned by solid growth, robust consumption and high business confidence.
Europe's green transition: climate gains with an economic downside
In The Wall Street Journal, a sharp article appeared this week on the costs of Europe's energy transition. Over the past twenty years, Europe has carried out one of the most ambitious climate programmes in the world. Since 2005, CO₂ emissions have fallen by around thirty percent. In the United States, that figure is seventeen percent. Europe therefore remains the global leader in climate policy.
The WSJ points out, however, that over the same period the US economy has continued to grow and is actively pursuing re-industrialisation. Europe, by contrast, has seen a significant share of its industry shift to Asia and the US. The energy transition turns out to come with high economic costs that are being felt by both households and businesses.
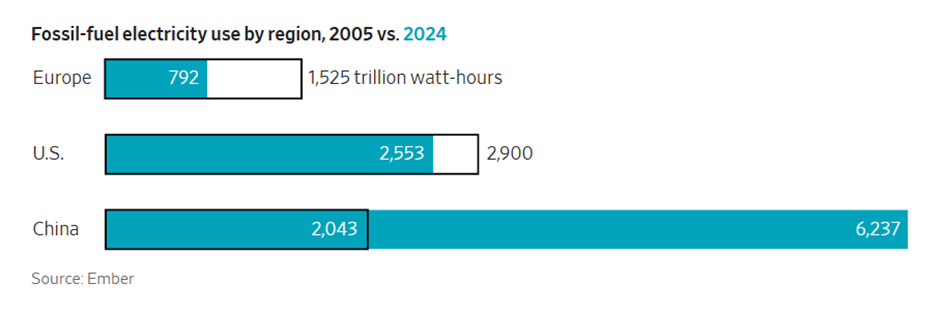
Energy prices form a major part of the problem. Industrial electricity in Europe now costs roughly twice as much as in the US and is around fifty percent higher than in China. This gap is structural. It is not just generation costs but, in particular, the associated system costs (such as grid reinforcement, storage, congestion management and balancing) that are pushing prices up.
The consequences are not limited to existing industry. According to the WSJ, the current energy infrastructure is even hampering the growth of strategic sectors such as artificial intelligence, which requires cheap and reliable electricity. Higher energy costs are also increasing the pressure on households, which is eroding public support for climate policy. More and more anti-establishment parties are presenting the energy transition as an elitist project that mainly affects workers, consumers and peripheral regions.
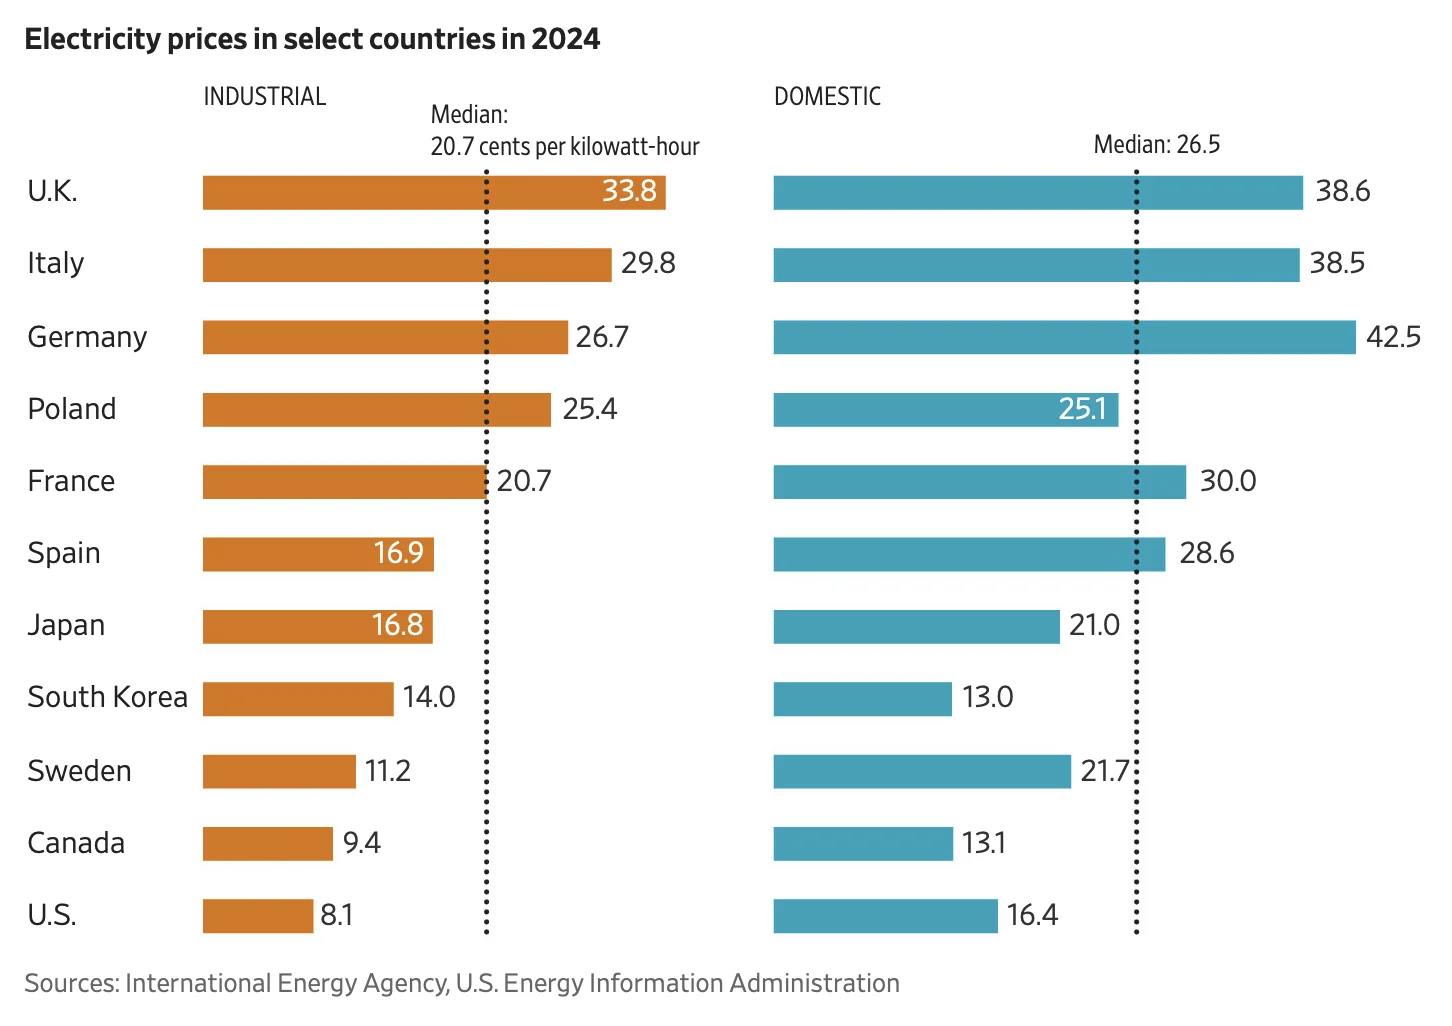
Several examples illustrate the urgency. Jerome Evans, head of a German data centre operator, wanted to expand in Frankfurt, Germany's digital heartland. However, the local grid operator reported that additional capacity would not be available until 2035. Aurora Energy Research calculated that a fully clean energy system in the United Kingdom will only become cheaper for households from 2044 onwards. Similar expectations apply to Germany. By that time, the economic damage could already be substantial.
Sweden's deputy prime minister and minister for energy, Ebba Busch, has also voiced sharp criticism of Germany's course:
"You cannot afford, in global competition, to pursue ideologically driven energy policy."
She points out that Germany has become too dependent on wind and solar power and, on windless or overcast days, draws large amounts of electricity from neighbouring countries, driving up prices there.
The broader economic effects are becoming increasingly visible. Energy-intensive companies are losing competitiveness, production is being relocated, and new investment projects, including data centres, are getting stuck due to a lack of grid capacity. In Ireland, data centres now consume more than twenty percent of all electricity. New applications are therefore barely being approved any more.
For households and businesses, all this results in structurally high costs and growing uncertainty. As a result, political resistance to additional climate policy is increasing. The core of the WSJ story is that Europe is achieving impressive climate gains, but that the current model is bringing ever heavier economic and infrastructural burdens.
For investors and entrepreneurs, this development is crucial. Energy prices, infrastructure and industrial competitiveness are closely intertwined. The coming years will reveal whether Europe can combine its green ambitions with a sustainable economic foundation, or whether a change of course becomes inevitable.
What happened on the capital markets last week?
- The likelihood of the Federal Reserve cutting rates next week has risen further; the market is now pricing in a probability of just over eighty percent. This expectation is being fuelled by deteriorating economic sentiment in the US. Consumer confidence fell, the Chicago Business Barometer weakened, and the labour market is clearly cooling: ADP reported a contraction in private-sector employment, while new jobless claims declined slightly. Producer prices (PPI) were neutral, giving the Fed extra room to ease policy.
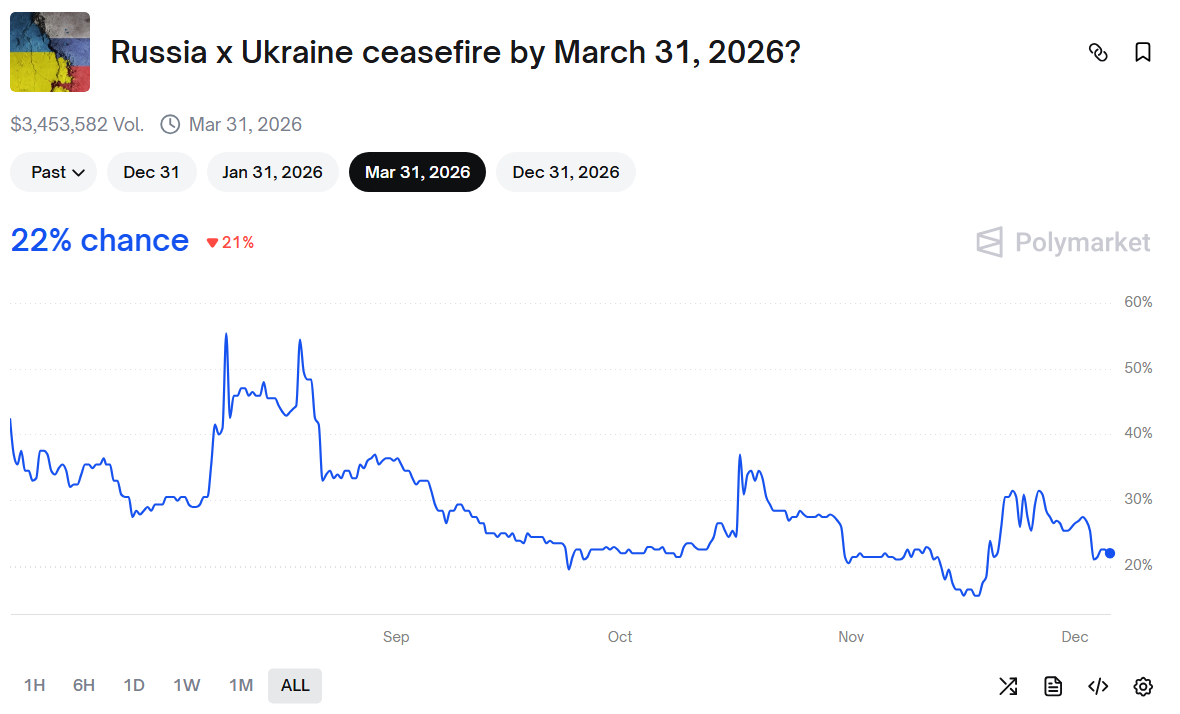
- Diplomatically, the situation around Ukraine remained largely unchanged. New talks in Switzerland yielded little progress due to ongoing disagreements over security guarantees and territorial concessions. On the trading platform Polymarket, the probability of a ceasefire before the end of the first quarter of 2026 is estimated at around twenty percent.
- Capital market rates declined further worldwide. In the eurozone, inflation fell again in November, ranging from 0.9% in France to 3.1% in Spain. In the United Kingdom, the ten-year rate fell as the government's funding plans proved less extensive than feared. Japan was the exception: higher core inflation and stronger industrial production pushed rates higher there.
- Equity markets staged a broad recovery. During the shortened Thanksgiving week, global equities rose by 3.3%. Precious metals performed strikingly well, with silver in particular climbing thirteen percent on the back of lower rates and strong industrial demand. The oil price edged lower, which among other things led to the lowest US petrol prices since 2021.
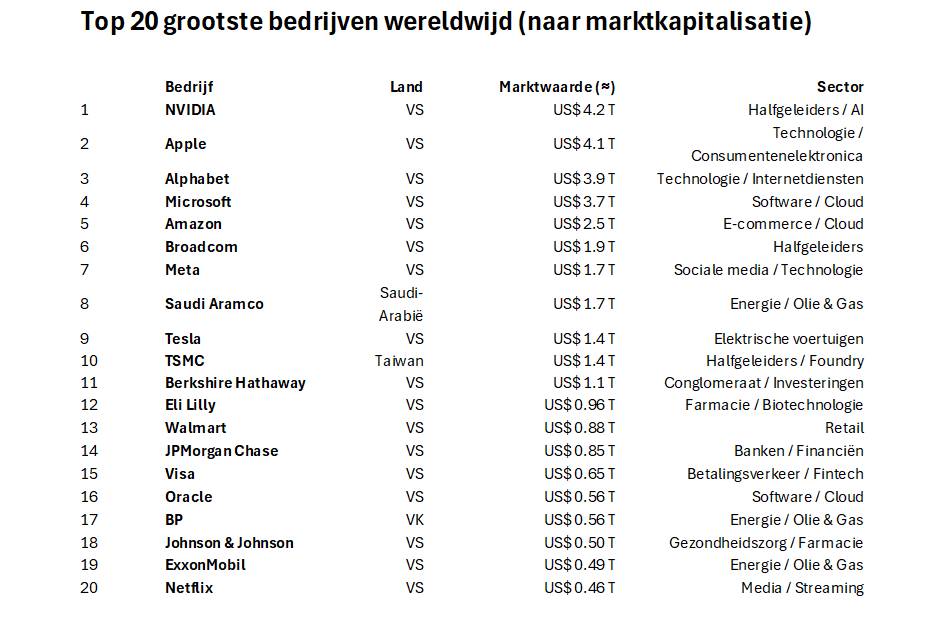
- In equity markets, the K-shaped dynamic remains visible. Cyclical companies are being hurt by weaker macro data, while technology stocks are benefiting from falling rates. In the US, the Magnificent Seven continue to carry the market, with Broadcom one of the standout winners of the year (+66% YTD) thanks to sustained demand for AI infrastructure. The company, like Nvidia a fabless chip manufacturer, recently passed the USD 1.9 trillion mark in market value. As a result, new names are once again being coined for the group of the largest US tech companies.
- Concentration in the global equity market continues to increase. The effective number of stocks in the MSCI World Index stands at a historic low, driven by the dominance of US megacaps. Among the twenty largest listed companies in the world, only three are no longer from the US; from Europe, only BP remains.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services? Feel free to get in touch.
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts thereof, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information must therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to obtain investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments may fluctuate. Past performance offers no guarantee for the future. You may lose (part of) your investment. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was originally written in Dutch and automatically translated into English with the help of AI. In case of any difference, the Dutch original prevails.