
Family Holdings #20 - Earnings Season in Full Swing at the Family Holding Companies


This week's topics:
Prosus and Tencent presented updates this week that painted a mixed picture. At holding company Prosus, the market reacted with disappointment, resulting in a sharp share price decline, despite the fact that all operational e-commerce units are profitable for the first time in the company's history. The unease centres on the decision to invest significantly more in subsidiary iFood to counter a competitive offensive, and on a communication style that came across to investors as more reactive than confident. At the same time, crown jewel Tencent demonstrated its strength with a strong quarter, in which profitability grew faster than revenue and the first fruits of the AI strategy became tangible, particularly in the advertising division and via its own language model Hunyuan 3.0. Moreover, Tencent announced it would step up both its AI investments and its aggressive share buyback programme by accelerating the sale of liquid positions from its investment portfolio, a development that works out favourably for Prosus shareholders.
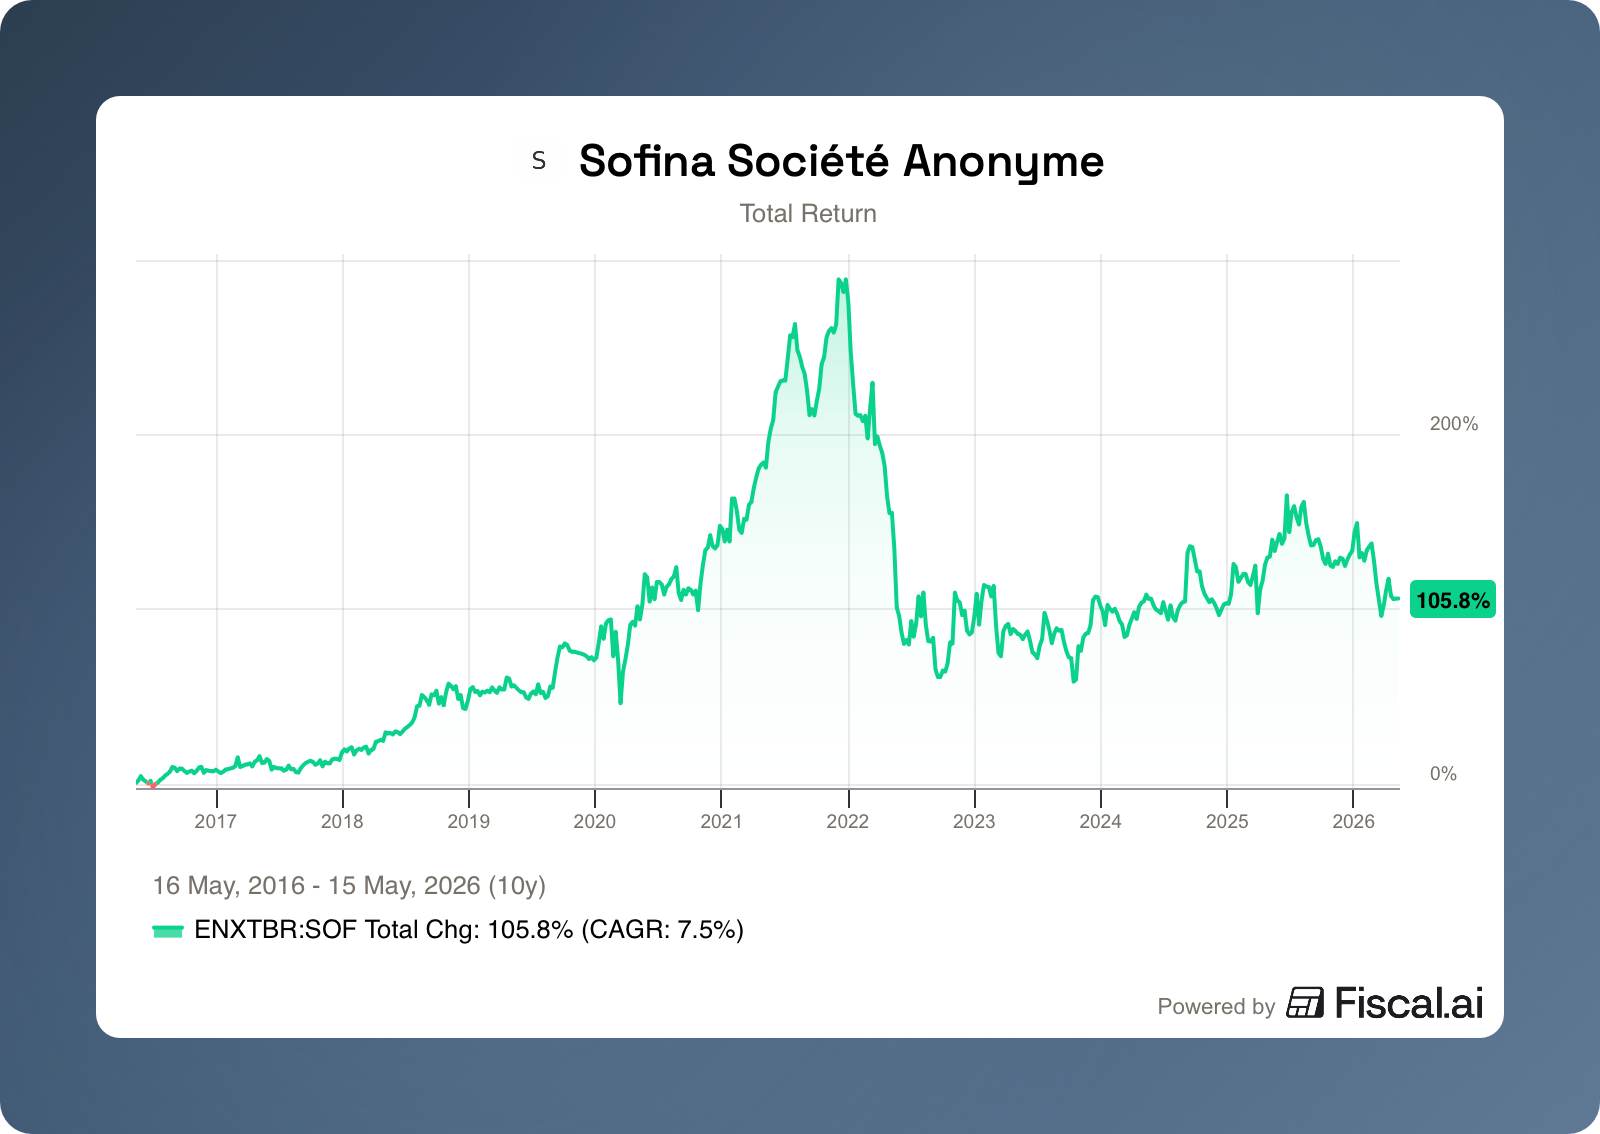
At the annual shareholders' meeting, CEO Harold Boël painted a picture of a Sofina that, after a difficult period, has settled back into calmer waters, with a normalisation of investments and divestments. Net asset value per share remained nearly stable, while the share still trades at a discount of over 30 percent. Boël emphasised that the venture capital landscape is heavily dominated by AI, with energy as a related theme, an area in which Sofina is active through, among others, Xbow, OpenAI and SpaceX.
In Brief:
Constellation Software (Toronto: CSU) has completed quite a few acquisitions again in recent weeks. Volaris, one of the operating groups, took on two companies: Accent Technologies from Melbourne (Florida), a provider of enterprise sales enablement software for regulated sectors with clients such as DHL and Boeing, and Socoto from Trier (Germany), a marketing and campaign software company with clients such as BMW, Shell and Husqvarna. In addition, subsidiary Vertus, part of the Jonas group, made an acquisition in Toronto: Magnusmode, a platform that builds accessibility tools for financial institutions and public transport. Finally, Vela subsidiary Datamine made a strategic investment in Commit Works from Fortitude Valley (Australia), a software company that digitises operational planning and execution for the mining industry.
Topicus (Toronto: TOI) acquired Lighthouse Software as of 1 May 2026. The software company from Ede is known in the healthcare market for QuestManager, a platform that healthcare organisations use to measure treatment outcomes and patient experience. With this acquisition, Topicus Healthcare further expands its portfolio in healthcare IT.
Lifco (Stockholm: LIFCO-B) CEO Per Waldemarson bought 15,000 shares in the company on 12 May at SEK 278.50 per share, for a total amount of SEK 4.2 million. This is already the CEO's second purchase of own shares in a short period. As of 24 April, Waldemarson held 948,500 shares in Lifco.
Prosus (Amsterdam: PRX) was active on both the buy and sell side this week. The company led an investment of USD 240 million in India's Rapido, the country's largest and most affordable mobility platform, active in more than 400 cities. The deal values Rapido at USD 3 billion. At the same time, Prosus sold a 5% stake in Delivery Hero to Aspex Management for approximately EUR 335 million, at a premium of around 22% to the 30-day average price. That sale follows an earlier divestment of 4.5% to Uber in April and stems from commitments Prosus made to the European Commission as part of the approval for the acquisition of Just Eat Takeaway.
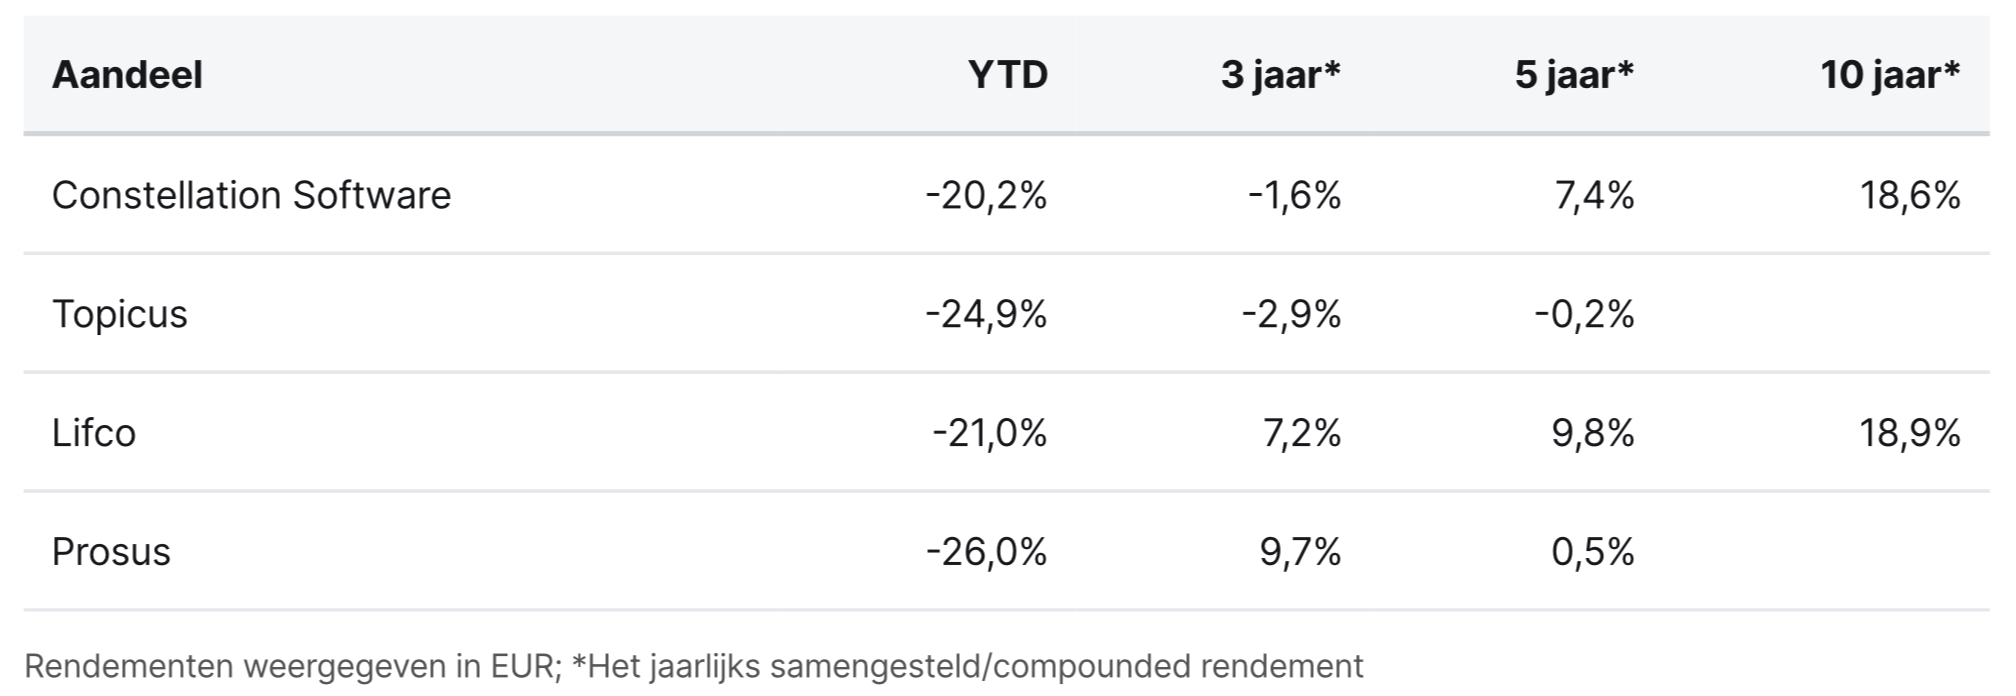
Constellation Software, Topicus, Lifco and Prosus ended the trading week on the Toronto, Stockholm and Amsterdam stock exchanges at prices of CAD 2,612.34, CAD 93.93, SEK 279.40 and EUR 39.10 per share, respectively.
KKR delivers strong quarter despite ongoing concerns about private credit
Last week, KKR (New York: KKR) presented its results for the first quarter of 2026, and at first glance they look excellent. Fee Related Earnings, the profit the company generates from fixed management fees, and therefore the most stable and predictable part of its earnings model, came in at $1.13 per share, up 23% from a year earlier. Total Operating Earnings of $1.47 per share rose 18%, and Adjusted Net Income (profit adjusted for one-off items that management steers on) came in at $1.39 per share, +20% year-on-year. Each of these figures ranks among the highest KKR has ever reported.
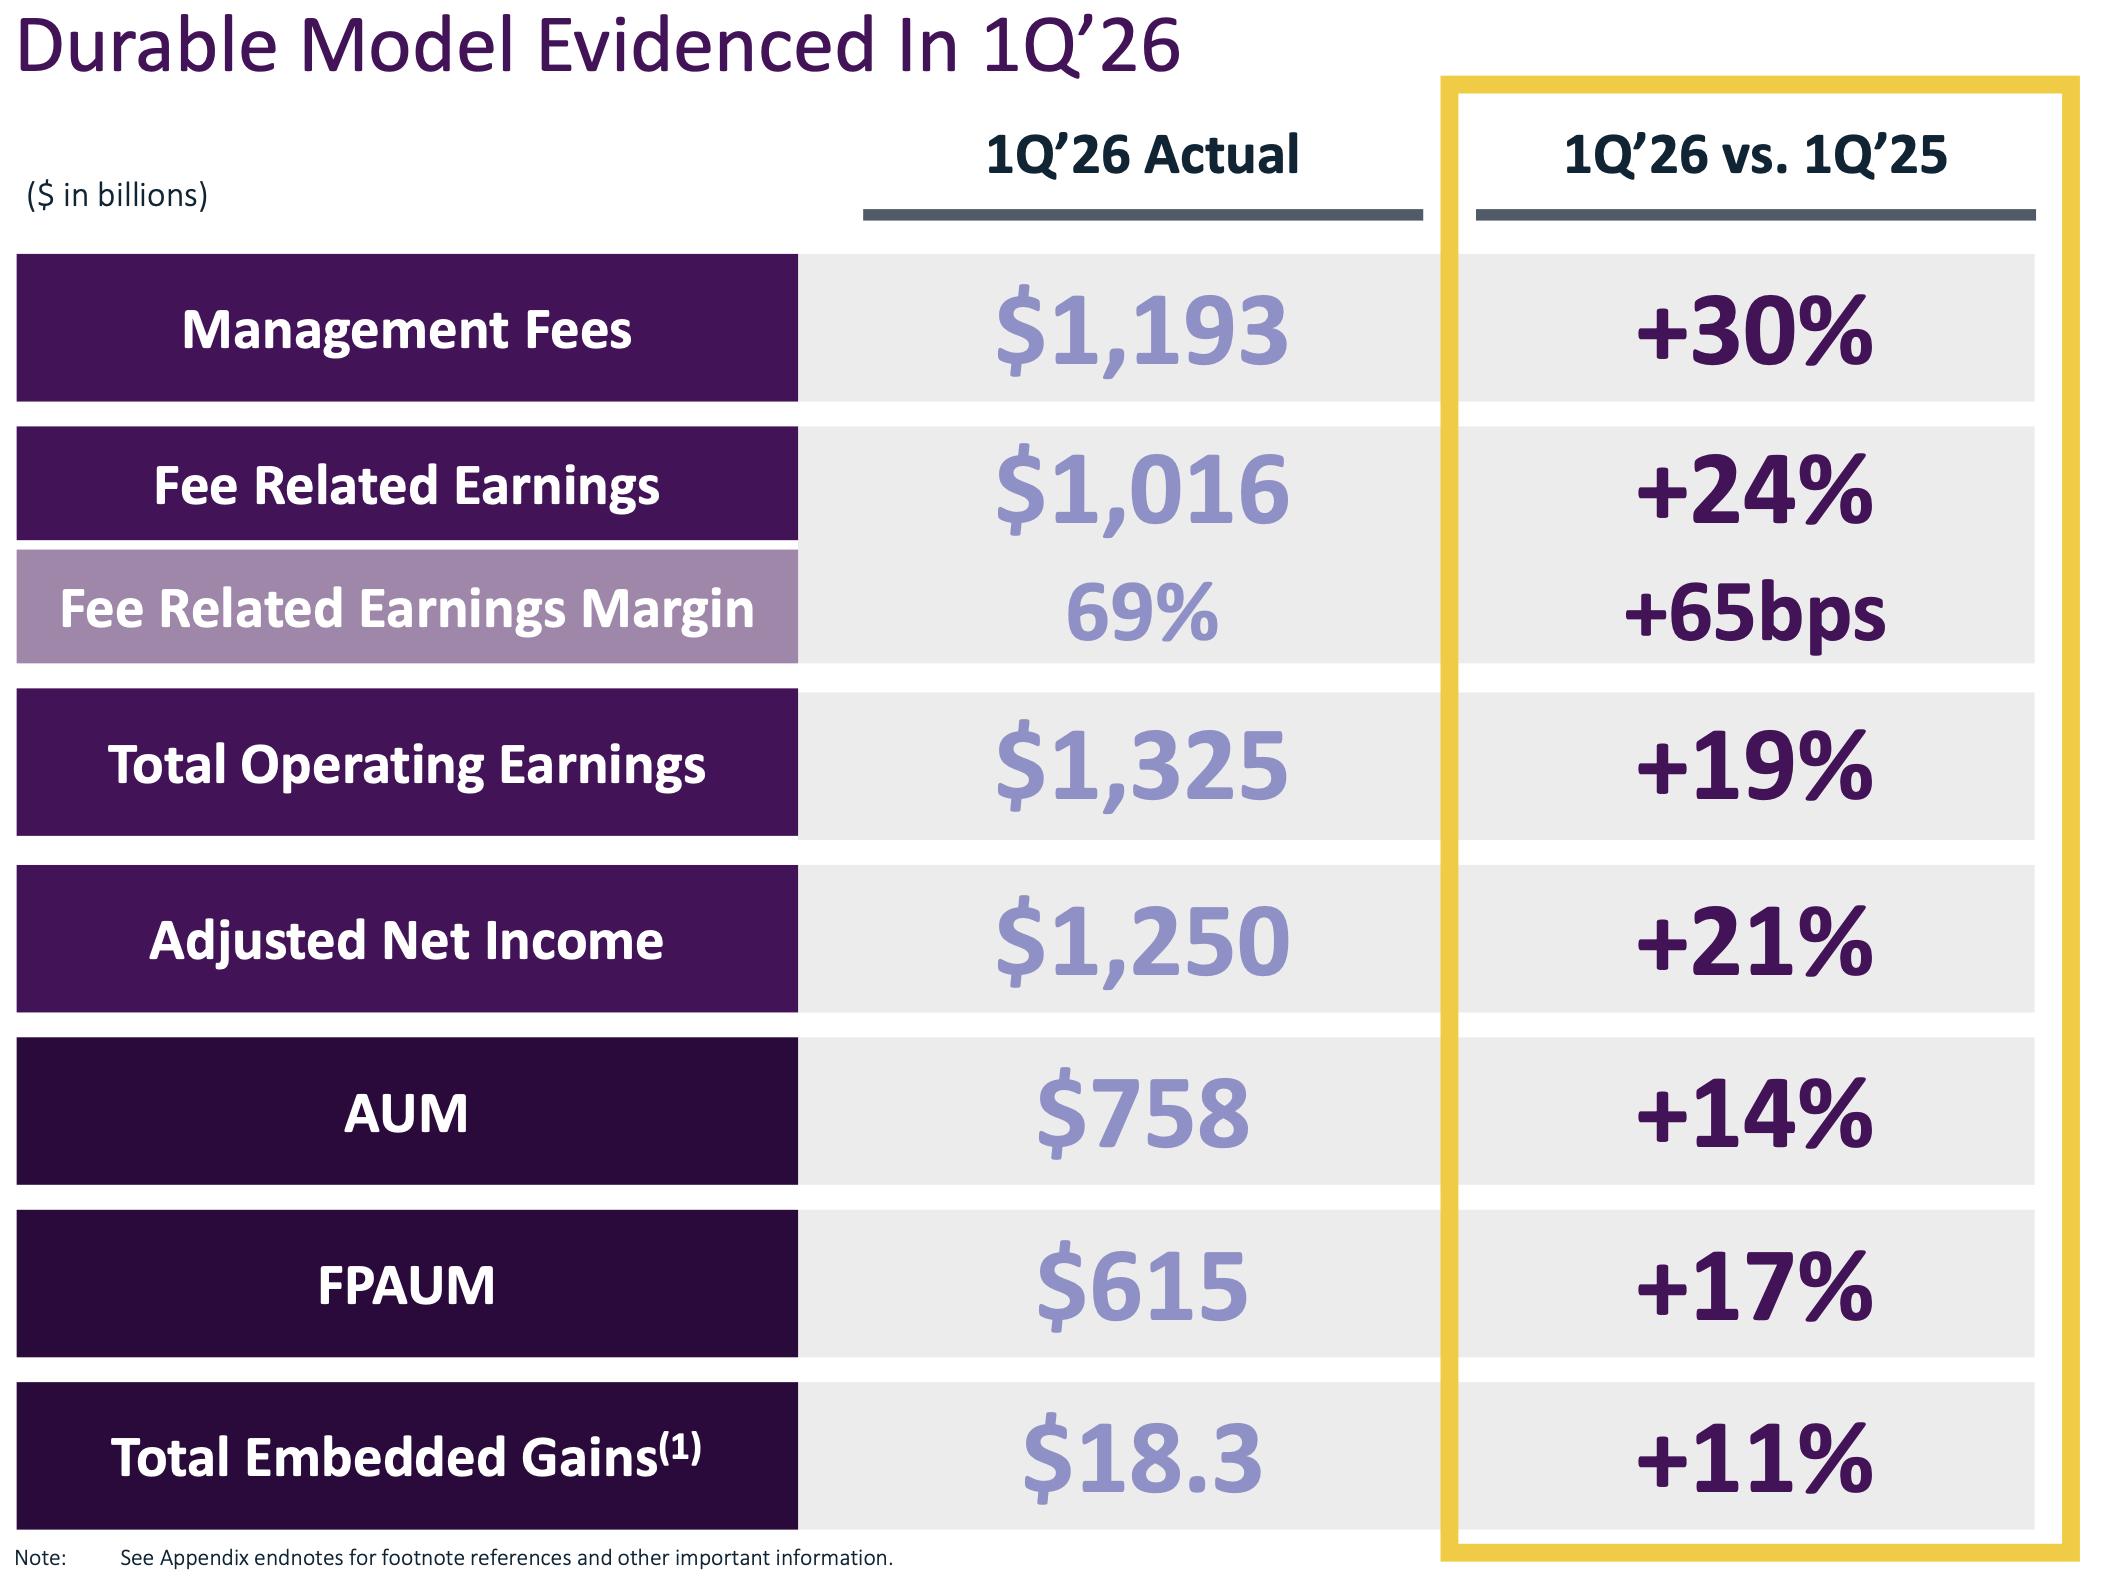
If you only read the headline figures, you might think KKR has the wind fully in its sails. And in many respects it does. But the reality is more nuanced. A significant part of the beat comes from so-called "catch-up fees" — a one-off backdated fee that fund managers receive when a fund closes, allowing the manager to collect fees retroactively on all the capital raised. This quarter, KKR closed its North America XIV fund at $23 billion (the largest vintage ever, and larger than the $19 billion of the previous fund) and raised additional capital for Global Infrastructure V. Good news, but it is important to realise that this type of fee does not recur every quarter. If you strip out the catch-up fees from both periods, there is still healthy growth of just above 20% in management fees.
A second nuance lies in Strategic Holdings, a relatively young segment through which KKR participates in its core PE strategy via its own balance sheet. There, the result of $48 million came in roughly 15% below consensus. Management did, however, maintain its full-year 2026 guidance of at least $350 million in Strategic Holdings Operating Earnings, with a concentration of this in the second half of the year.
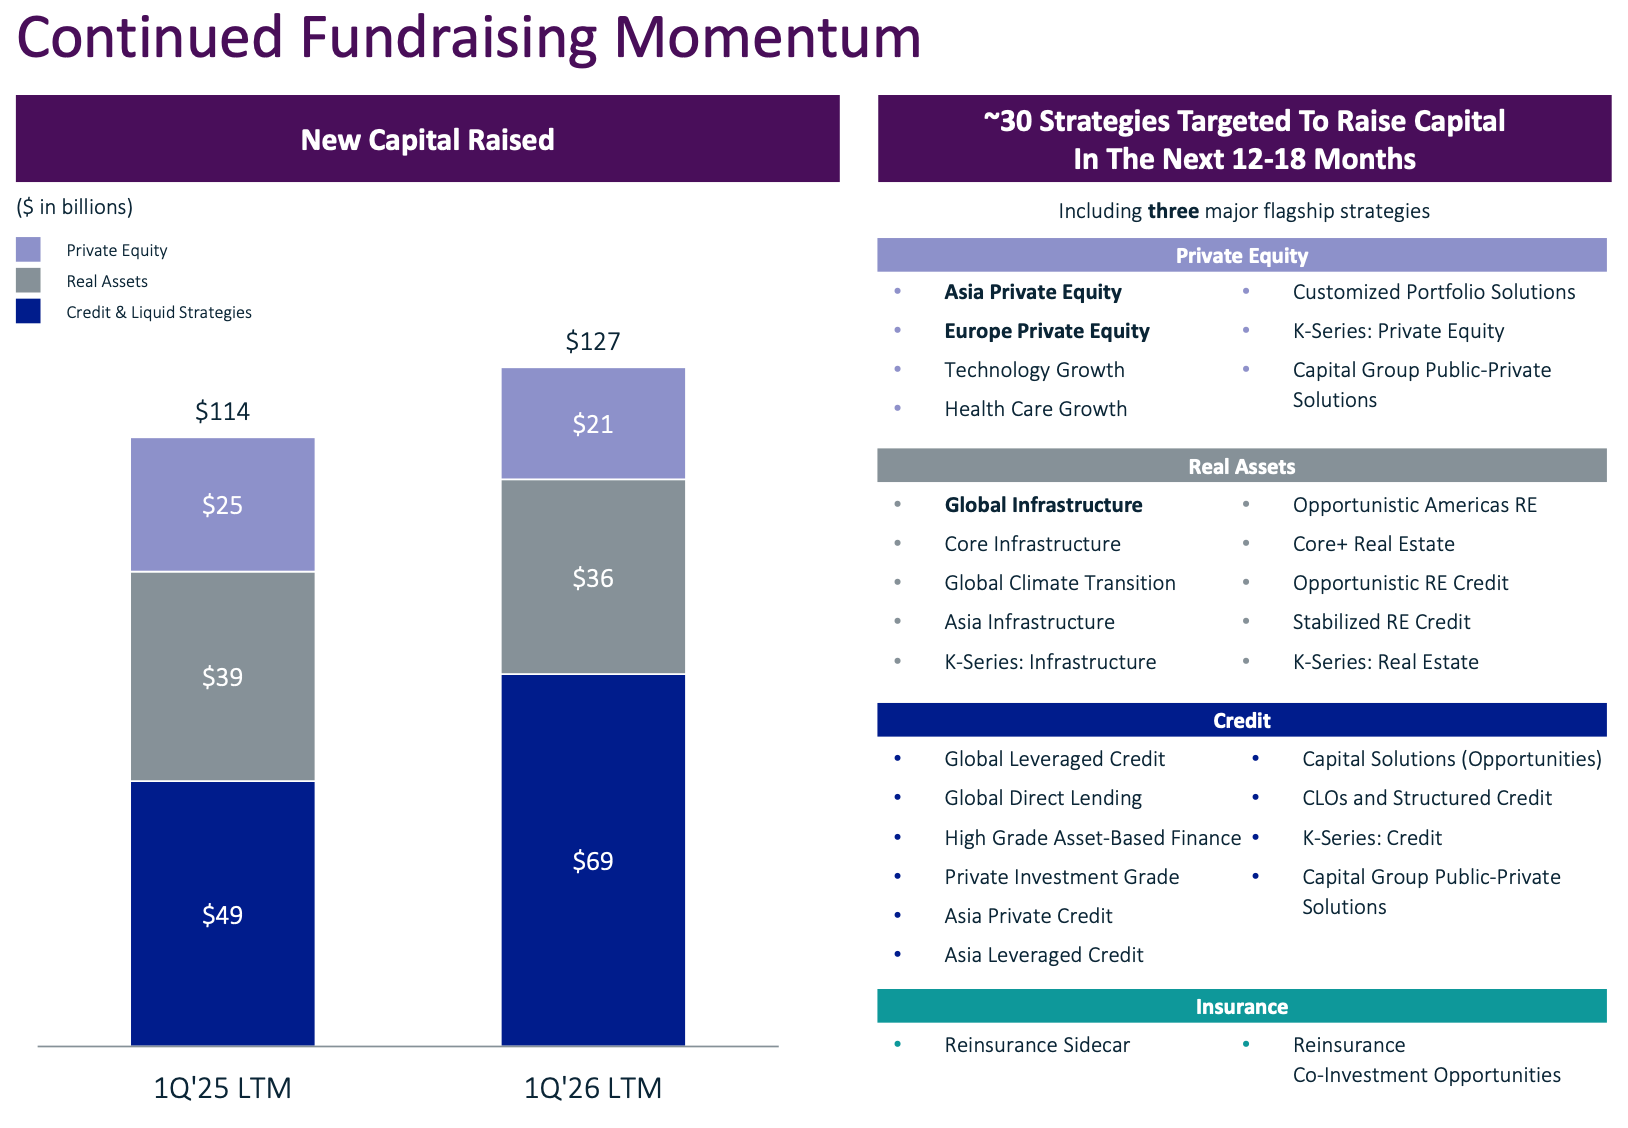
However, a healthy private equity holding company is not judged primarily on its quarterly profit figure, but also on how much new capital is coming in (fundraising). KKR raised $28 billion in new capital in the first quarter, comparable to the previous quarter. Over the past twelve months, that amounts to $127 billion, a record, and it shows that the engine keeps running despite the macro turbulence of recent quarters. The largest contribution this quarter came from Credit & Liquid Strategies with $15 billion, followed by Real Assets with $7.8 billion and Private Equity with $4.7 billion. KKR identifies around thirty strategies that will be actively raising capital in the market over the next 12 to 18 months. The slide above underscores how broadly diversified fundraising has become: flagship funds accounted for only 15% of the capital raised this quarter, compared with a much higher dependency five years ago.
Co-CEO Scott Nuttall added an interesting observation about what he is seeing in the market.
"Fundraising just feels really good. We have momentum on multiple fronts, globally, including in the Middle East and among pension funds, sovereign wealth funds, insurers and high-net-worth clients."
He then pointed to an underlying trend that, in his view, works in KKR's favour: institutional investors increasingly want to concentrate their capital with fewer but larger partners. That pattern is intensifying precisely now, because performance within the private markets sector is increasingly diverging. Nuttall called this a "K-shaped industry": a reference to the idea that a small group of large, well-performing managers is pulling further ahead, while the middle tier is falling behind. In his words: "We think that's where the opportunity lies for us to keep taking market share."
The concerns
Alongside the positive underlying story, there are two clear shadow sides that KKR has been transparent about. The first concerns the full-year guidance.
Management acknowledged for the first time that the ambition to exceed $7 in Adjusted Net Income per share in 2026, growth of roughly 45% year-on-year, has become less likely. CFO Robert Lewin put it this way on the earnings call: "If you were to guess right now whether we hit the $7 per share, we think we're more likely to come in below that level." According to him, the cause does not lie with the portfolio itself, but with market timing. In a turbulent macro climate marked by geopolitical uncertainty, KKR prefers to postpone a number of planned exits rather than sell a strong portfolio company below its worth.
Co-CEO Scott Nuttall summed it up succinctly: "This is about timing, not about the size." Delayed monetisations shift into 2027 and beyond, so the value is not lost, it still sits within the portfolio. Another figure underscores this: total embedded gains (realised but not yet distributed value increases on the balance sheet and in carried interest) stand at $18.3 billion, 11% higher than a year ago and close to an all-time high.
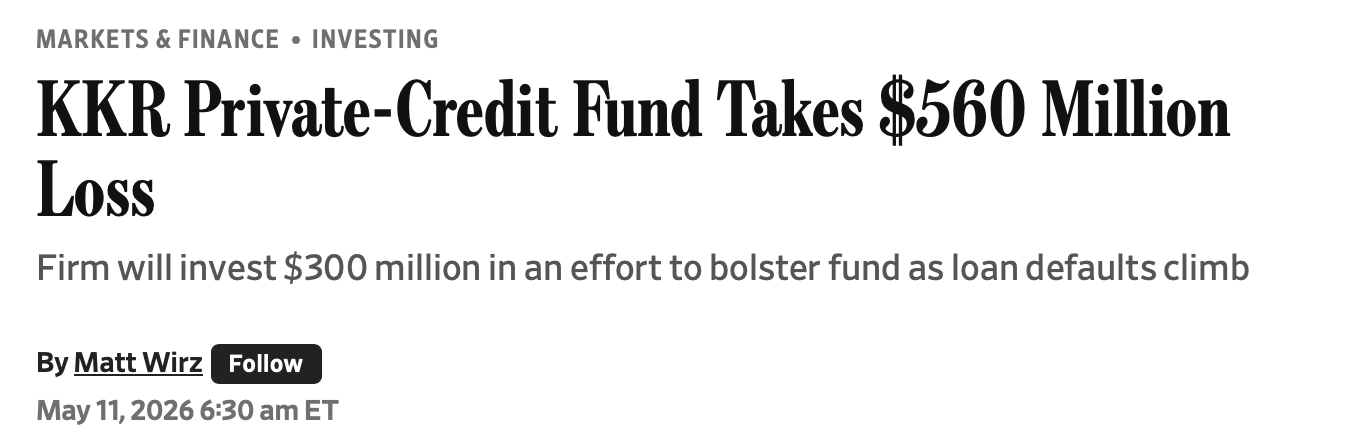
The second concern is more material and received broad media attention last week via an article in the Wall Street Journal. FS KKR Capital, or FSK for short, is KKR's largest listed Business Development Company (BDC), a vehicle that provides loans to mid-sized US companies and is held primarily by retail investors. In the first quarter, FSK took a loss of $560 million, roughly 10% of its net asset value. The default ratio in the fund (the percentage of loans on which repayment has stalled) jumped from 5.5% in December to 8.1% in March. Two rating agencies have since downgraded FSK's bonds to junk, and the share price has almost halved over the past year.
KKR is digging deep here, with a support package consisting of $150 million in new convertible preferred shares, a $150 million tender offer for ordinary shares at $11 apiece, and the repurchase of another $300 million in its own shares by the fund itself. As if that were not enough, KKR is also forgoing half of its quarterly incentive fees for the coming year, amounting to roughly $50 million at the current level.
Behind these generous gestures lies a harsh reality. The loss is real, and the pattern of earlier problems at FSK keeps repeating itself. Following the earlier write-down on the largest investment, defaults are now occurring at software company Medallia and dental chain Affordable Care. This points to a persistent vulnerability in specific parts of the portfolio, which proves that the broader concerns about private credit exposure among retail investors are absolutely not unfounded.
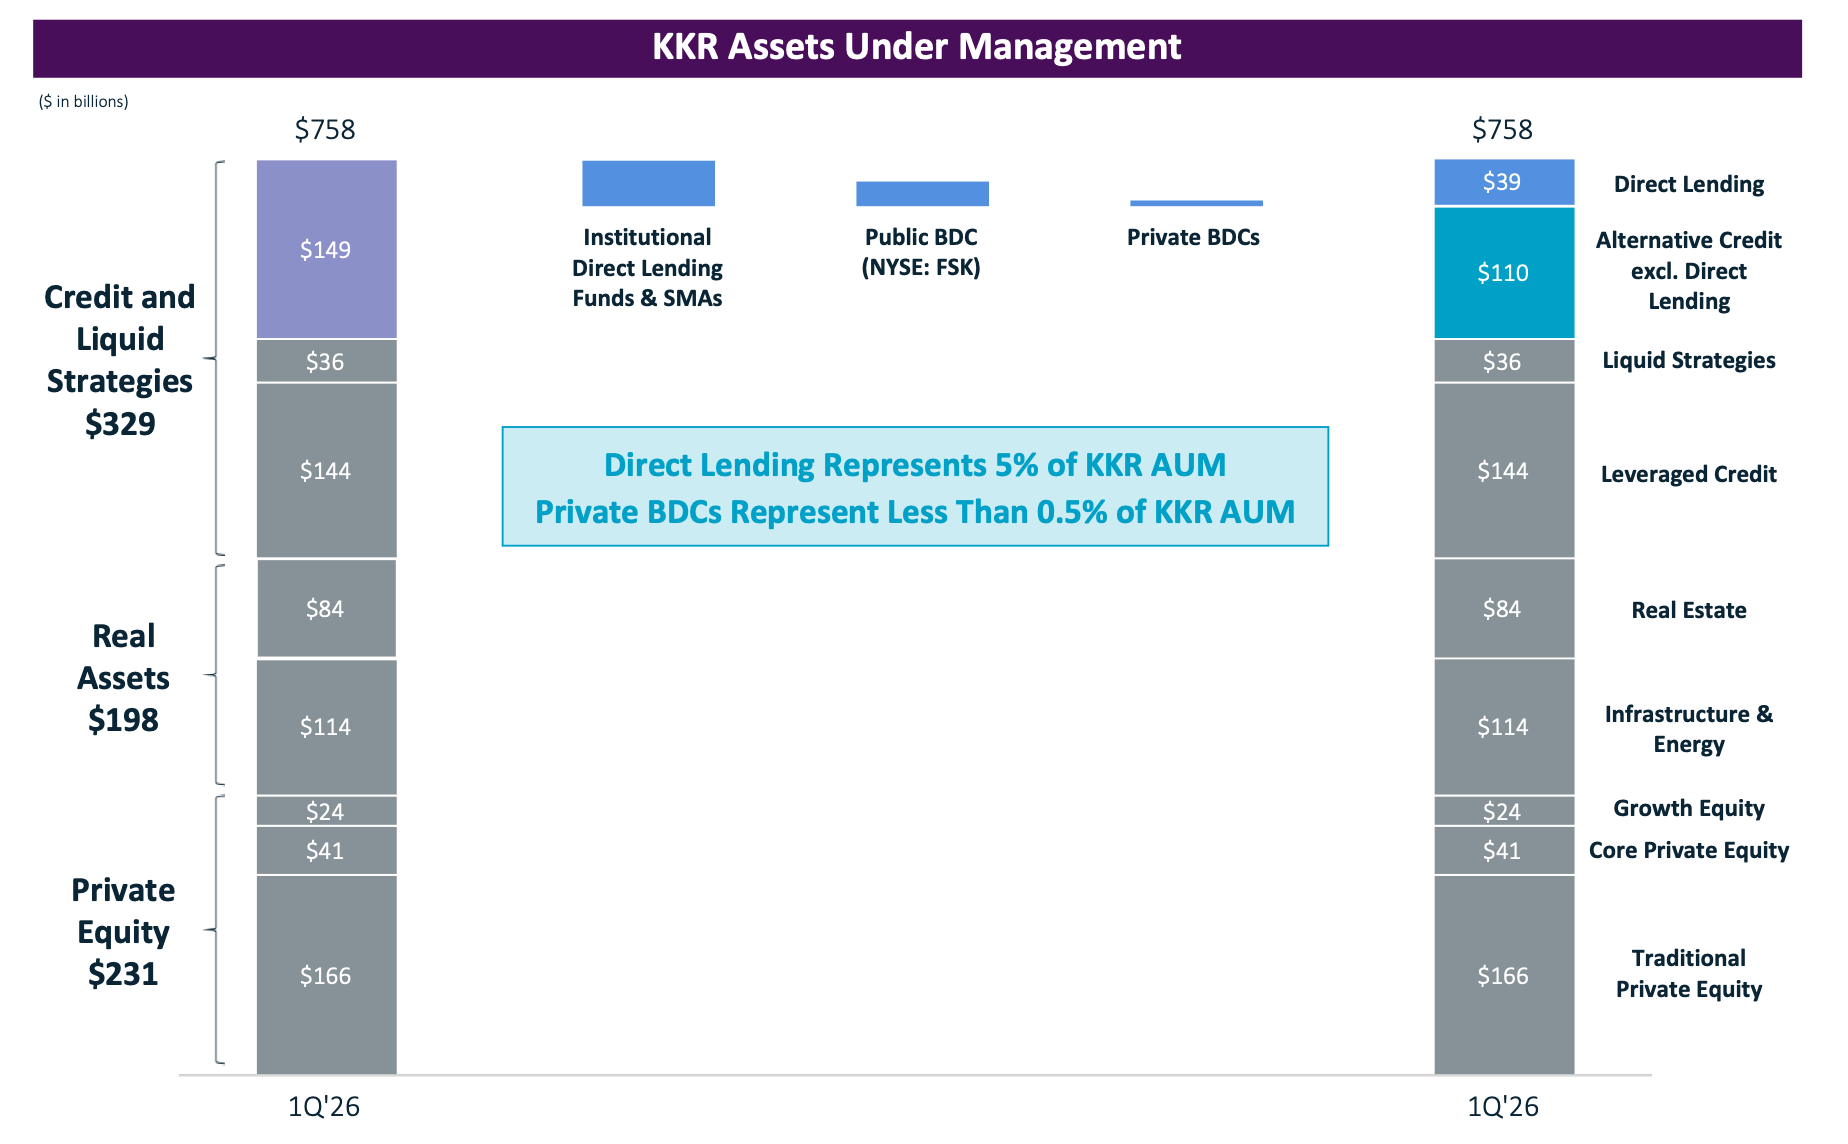
Zoom out, however, and the picture looks different. The slide above shows that direct lending accounts for just 5% of total AUM of $758 billion, private BDCs for less than 0.5%, and FSK itself for slightly under 2%. The problem is therefore confined to a small corner of the organisation.
A Reuters analysis from last week underlines that the recent 13F filings show institutional parties actually increased their exposure to listed private credit funds in Q1. Of the more than 6,000 investors, 11.5% added to their positions, against just 3.2% who sold. Scott Nuttall confirmed that pattern: "Institutional investors are coming back to direct lending. They see the headlines about wealthy individuals and conclude that the risk-reward on new deals is actually improving."
Conclusion
Putting the figures in the right proportion shows that KKR has become a strongly diversified business. These are objectively strong quarterly results, with one clear problem area that deserves to be taken seriously, but which needs to be put in perspective. KKR's core engine, raising capital, investing with discipline across all asset classes and delivering value over time for both clients and shareholders, continues to run at full speed.
KKR ended the trading week on the New York stock exchange at a price of USD 96.97 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Tencent performs strongly, but Prosus could use a lesson in communication
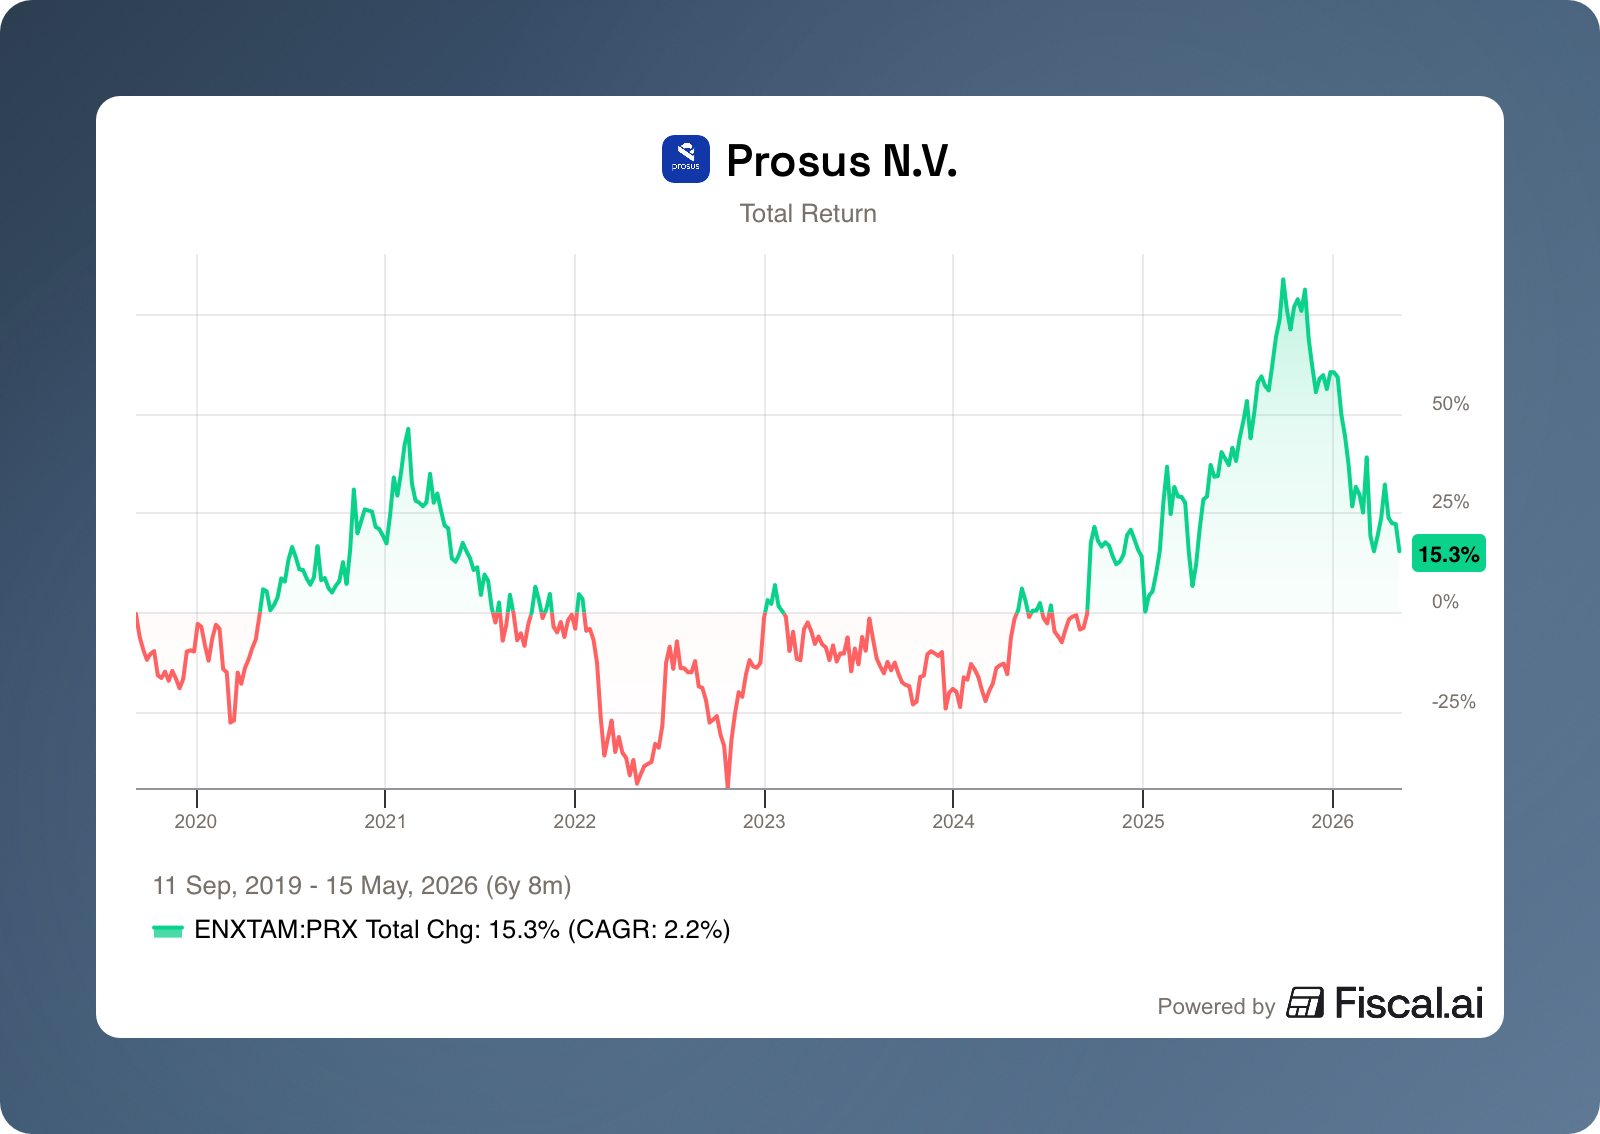
The market reaction to the recent updates from Prosus and Tencent tells a story of two different worlds: that of the holding company, where uncertainty about new investments is dominating, and that of crown jewel Tencent, which is proving with rock-solid figures that its fundamentals are more stable than ever. Although Prosus consists of 80% Tencent, the remaining 20% caused quite a ripple in the share price this week.
CEO Bloisi's letter
Let's start with the company's own letter to shareholders, in which CEO Fabricio Bloisi provided the following update:
Although the official annual results will only be presented in June, it is already clear that the company has comfortably achieved its ambitious targets. With total revenue of $7.3 billion and adjusted e-commerce EBITDA of $1.1 billion (excluding JET and La Centrale). For the first time in the group's history, all operating e-commerce segments are profitable, and free cash flow continues to grow steadily, even without Tencent's contribution.
This all sounds great, yet investors were not satisfied with the update, and the share closed 7% lower on the Amsterdam stock exchange that day. The reason for this appears to lie in two things: (1) the additional investments that will be needed in the coming year, and (2) the way the company communicated.
The core of the unease lies with iFood, where Prosus has decided to go on the offensive from a position of strength. Although the Brazilian market leader is currently performing strongly, competitors have pledged to spend more than $1.5 billion this year to gain market share. Prosus management believes this level of spending is not sustainable, but at the same time says that this is precisely why it is necessary to invest more itself. A rather peculiar way of communicating.
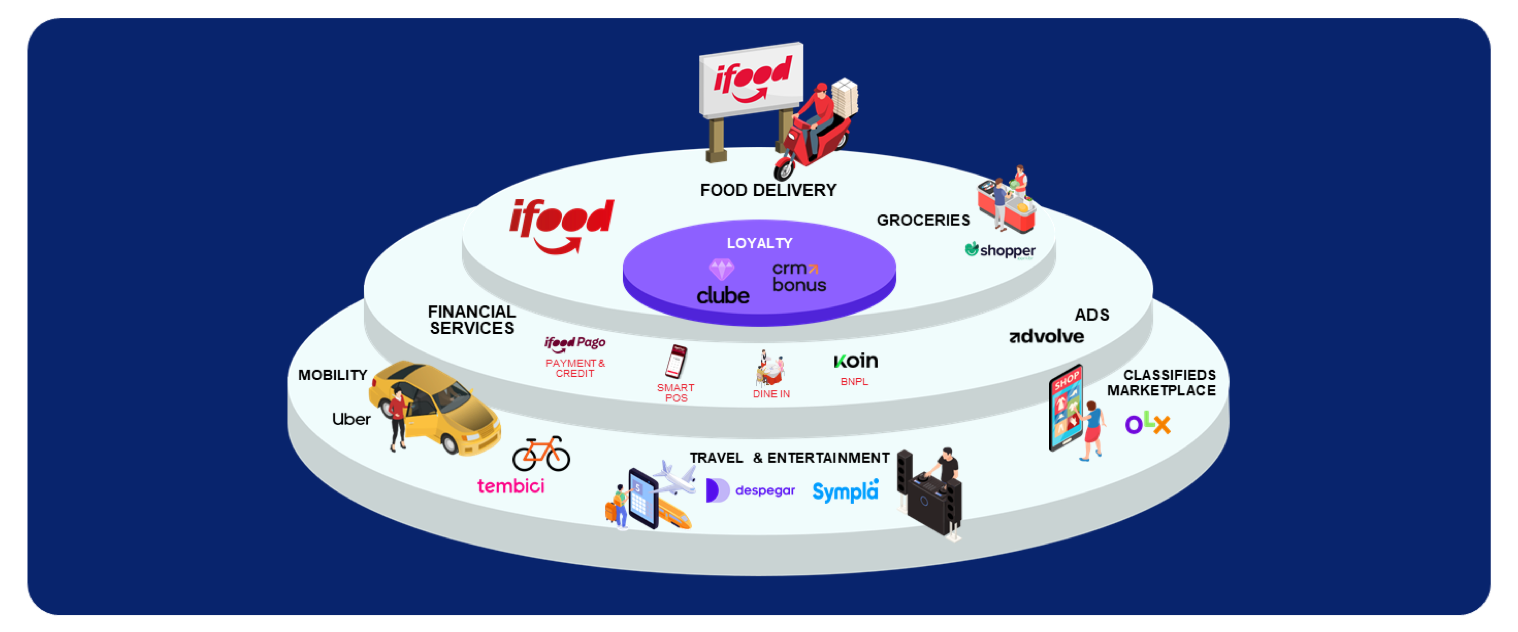
However, this offensive strategy has a direct effect in the short term. Expected adjusted EBITDA for iFood in FY27 has been sharply revised downward to a range of $100 to $150 million. For investors who mainly hold Prosus as an indirect stake in Tencent (and there are many), this feels like a bitter pill. These investors would prefer every euro available for investment to be allocated to share buybacks instead. Still, investments in AI within Prosus's ecosystems do appear to be paying off.
A crucial tool within these investments is the Large Commerce Model (LCM), which has been trained on billions of transactions and is already delivering significant results at iFood. Here, conversion on notifications rose by 75%, while customer acquisition costs fell considerably and conversion on personalised offers increased sharply. This technology is now being scaled up to other markets, including PayU in India and platforms such as OLX, Just Eat Takeaway and eMAG in Europe. The impact of agent technology is also substantial on the operational front; every day, 5,000 AI agents within the company's own ecosystem complete around 4 million tasks per month. According to management, this delivers an efficiency benefit equivalent to the impact of more than 1,000 full-time jobs. The first tests of these applications have already led to 22% growth in car sales at OLX, a 30% increase in leads at Just Eat Takeaway, and 32% higher restaurant retention at iFood.
Although you might give management the benefit of the doubt based on the strong innovation figures, investors are stumbling over the way this strategy is communicated. Prosus argues that competitors' billions in spending are not sustainable, yet nonetheless feels the need to sharply scale up its own investments now. The market does not interpret this wording as a deliberate choice made from a position of strength, but rather as a reactive stance: 'if the competition is doing it, we have to keep up'.
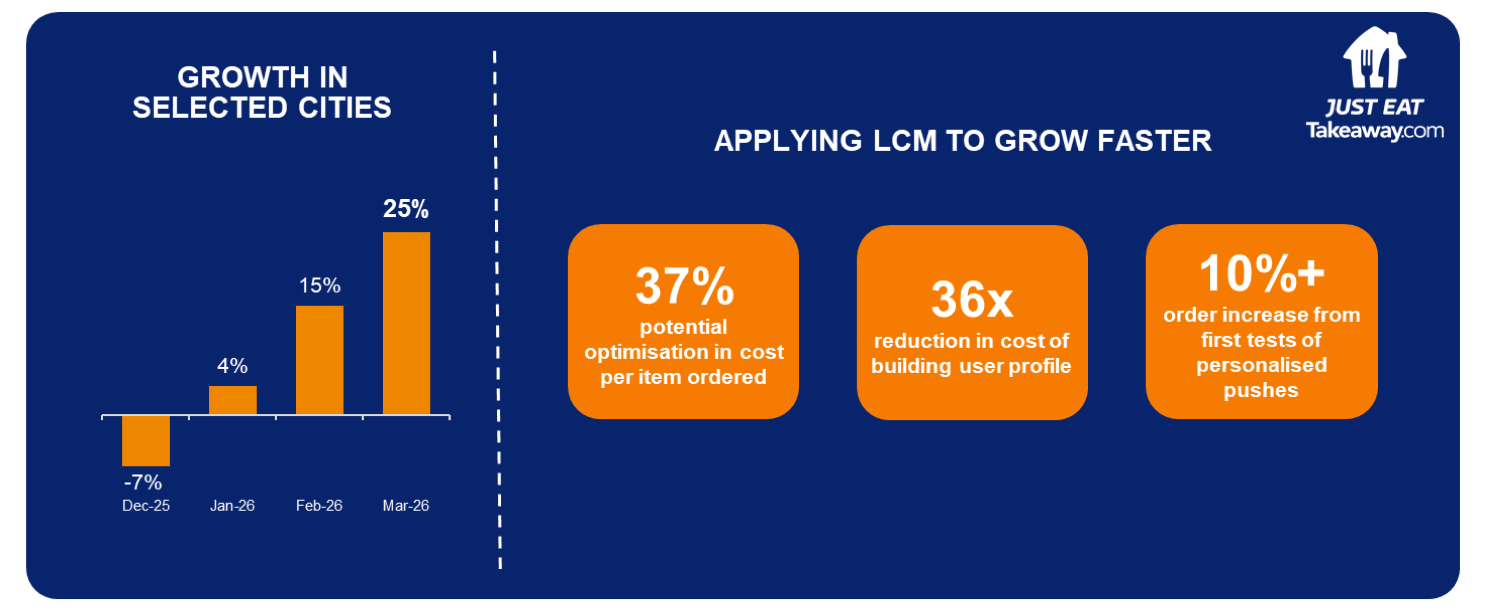
In addition, disclosure on Just Eat Takeaway (JET), acquired last year, was extremely limited and vague. Management reported a 7% decline in the number of orders, but tried to soften this by pointing to "selected cities" that grew by 25% following successful experiments. Because concrete details—such as which cities were involved, what their share of total revenue is, and what exactly these experiments entailed—were entirely absent, this did not sit well with investors.
Bloisi closes the letter with:
We believe we are building something special with results that will compound for many years into a great future for Prosus. I am investing alongside you, and so is Prosus. We continue to repurchase shares at ~$5 billion annual run rate which will bring the total amount returned to you to ~$50 billion across Prosus and Naspers in four years.
Crown jewel Tencent
While the holding company Prosus is grappling with its own communication, its crown jewel Tencent, with its first-quarter 2026 results, shows why it remains the undisputed engine of the group. Tencent was rewarded for a quarter in which its operational strength and the first successes of its AI transformation became clearly visible.
Tencent's financial fundamentals remain undiminished, as is immediately evident from the reported headline figures for the first quarter of 2026. Total revenue rose by 9% to RMB 196.5 billion. Although 9% growth may seem modest at first glance, management noted that this figure was depressed by the unfavourable timing of Chinese New Year. Adjusted for this calendar effect, revenue growth would have come in at a more solid 11%.
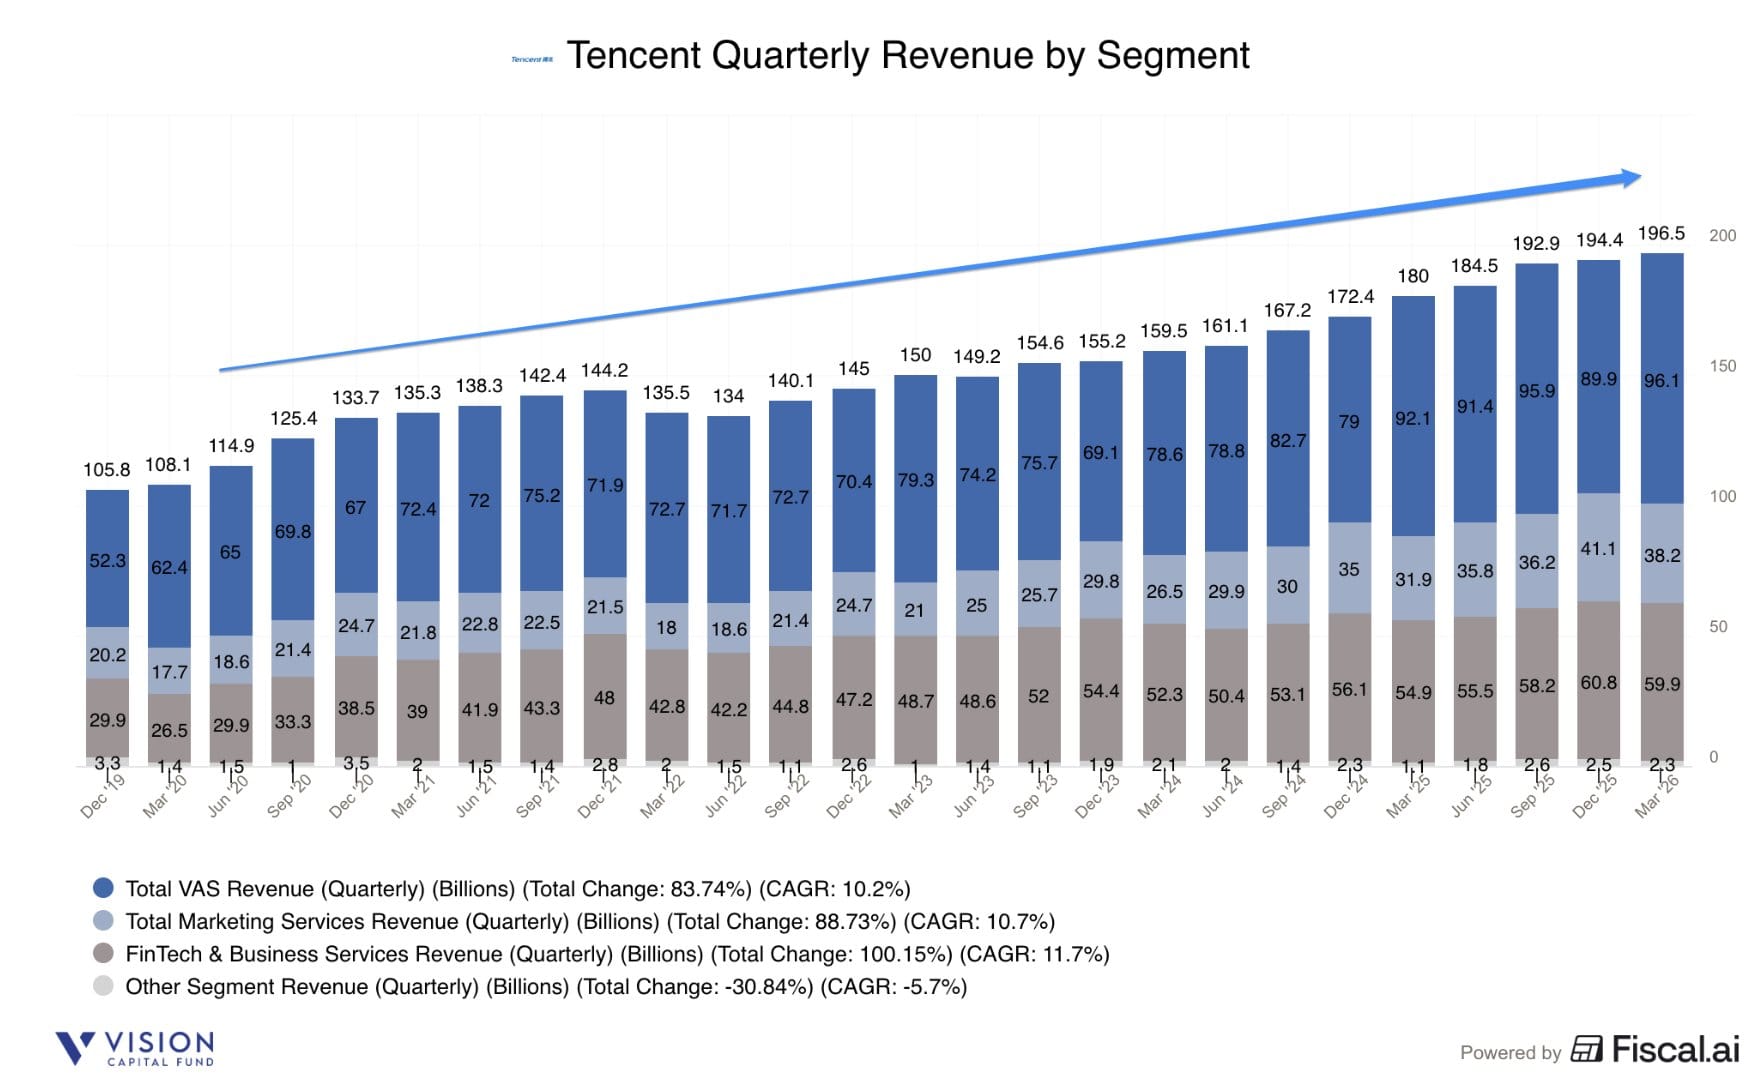
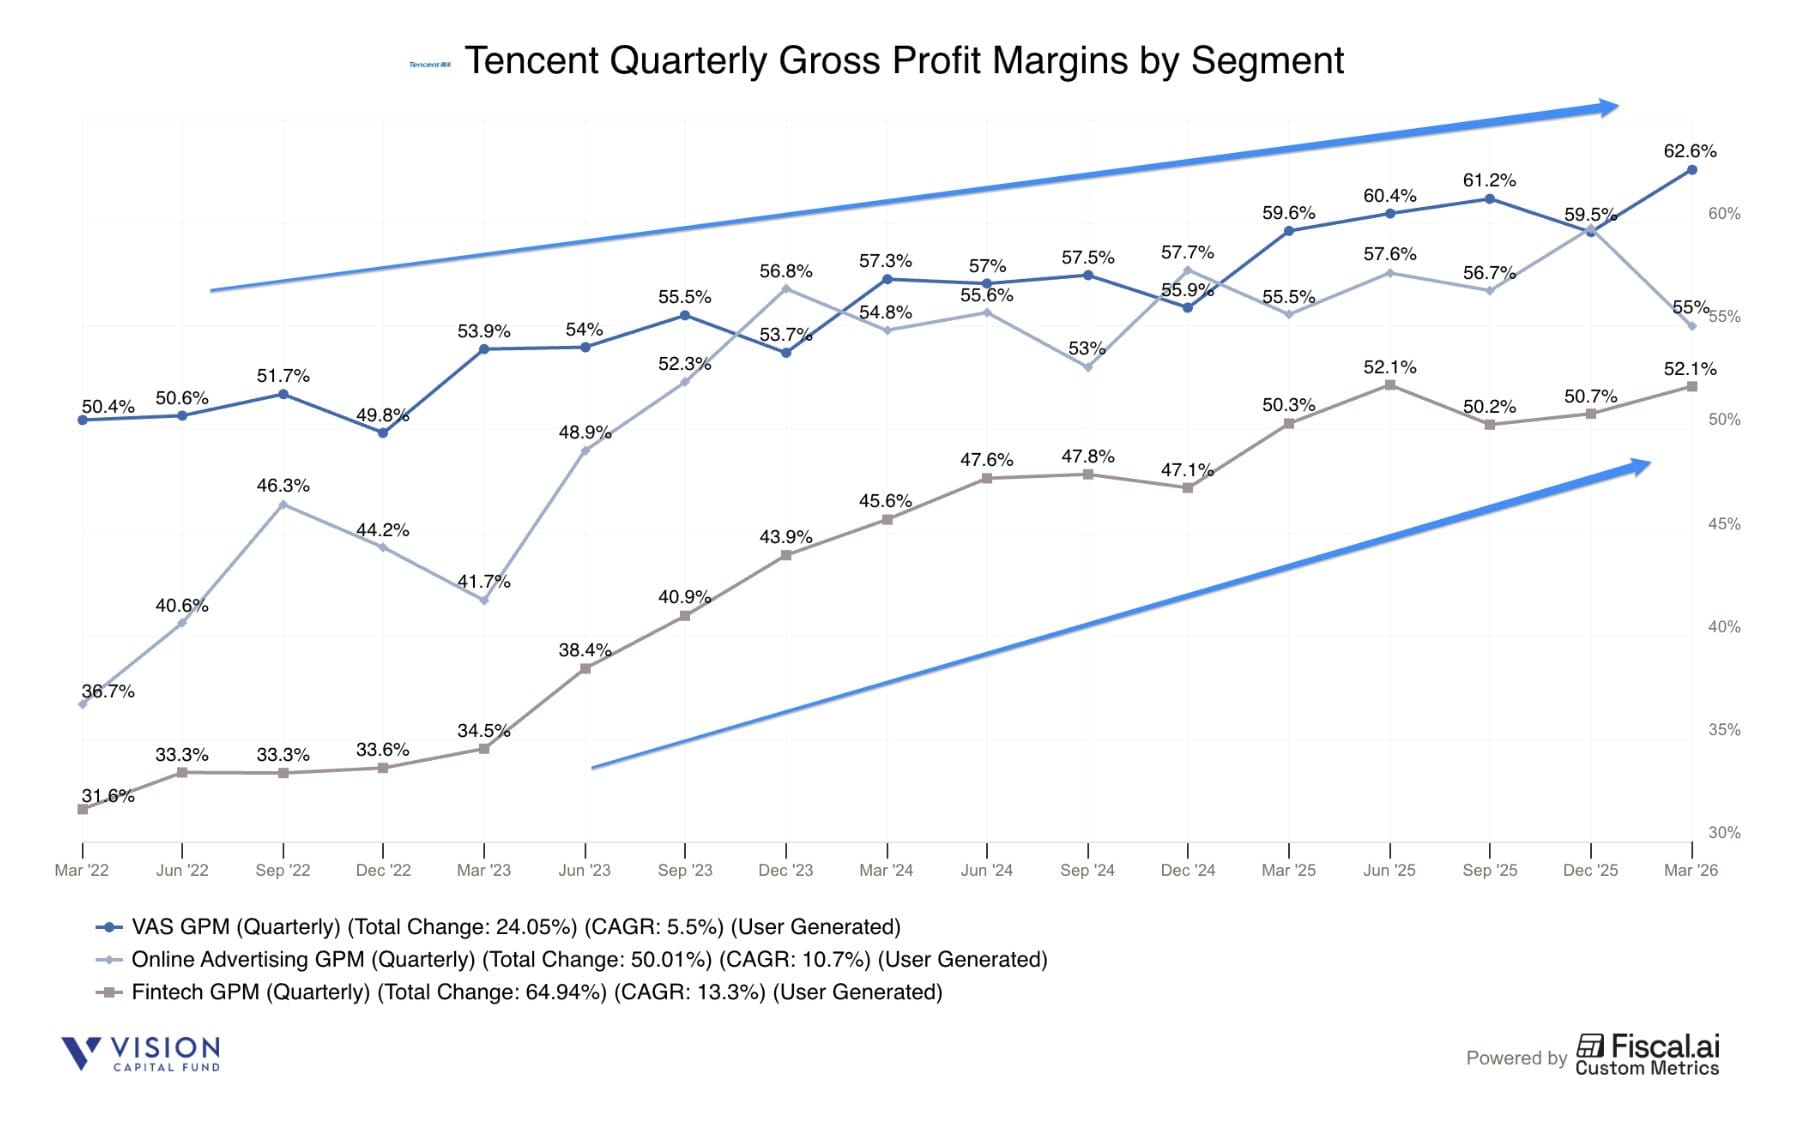
Another notable point was that profitability grew faster than revenue. Gross profit climbed by 11% to RMB 111.3 billion, with the gross margin rising to 56.6%. This operating leverage is clearly visible in net profit (Non-IFRS), which rose by 11% to RMB 67.9 billion. Without the massive investments in new AI products, operating profit would have increased by as much as 17%, underlining the enormous underlying strength of the core business.
As can be seen in the charts above, there is a clear upward trend across all key divisions. The segments performed as follows:
- Gaming (VAS): This segment remains the company's primary engine. Domestic games revenue grew by 6%, while international games revenue rose by 13%. Titles such as Peacekeeper Elite hit records with as many as 90 million daily players at peak moments. The gross margin in the broader VAS division rose to 62.5%, partly thanks to a shift towards in-house developed games with higher margins.
- Marketing Services (Advertising): The absolute standout, accelerating to 20% growth (RMB 38.2 billion). This growth is being driven by improved AI algorithms for ad recommendations and rising demand for Video Accounts. Notably, the 'ad load' (how many adverts users are shown) on these Video Accounts remains extremely low, at just 4% to 5%, compared with Western competitors such as Instagram, pointing to enormous untapped potential for future monetisation.
- FinTech & Business Services: This division grew by 9% to RMB 59.9 billion. Although margins here have historically been lower, the chart shows a strong climb towards 52.1%, up 200 basis points on last year. Growth here was mainly driven by commercial payments and rising demand for cloud services, including AI-related infrastructure.
With a record-high free cash flow of RMB 56.7 billion (+20% YoY) and a net cash position of $18 billion, Tencent has an extremely strong balance sheet. However, this still appears not to be enough to keep fuelling both AI investments and the share buyback programme. Management had previously stated it would prioritise AI at the expense of a somewhat slower pace of share buybacks, but it is now reversing that stance.
James Mitchell (CSO) stressed that Tencent is accelerating the sale of liquid positions in its enormous investment portfolio, currently valued at between $130 and $140 billion. By cashing in stakes, the company is creating the necessary room to finance both the growing demand for AI infrastructure and its aggressive share buyback programme. Management regards the current share price as "dislocated" (out of line with the true value), which makes the share buyback a priority right now. This is therefore a positive development for Prosus shareholders.
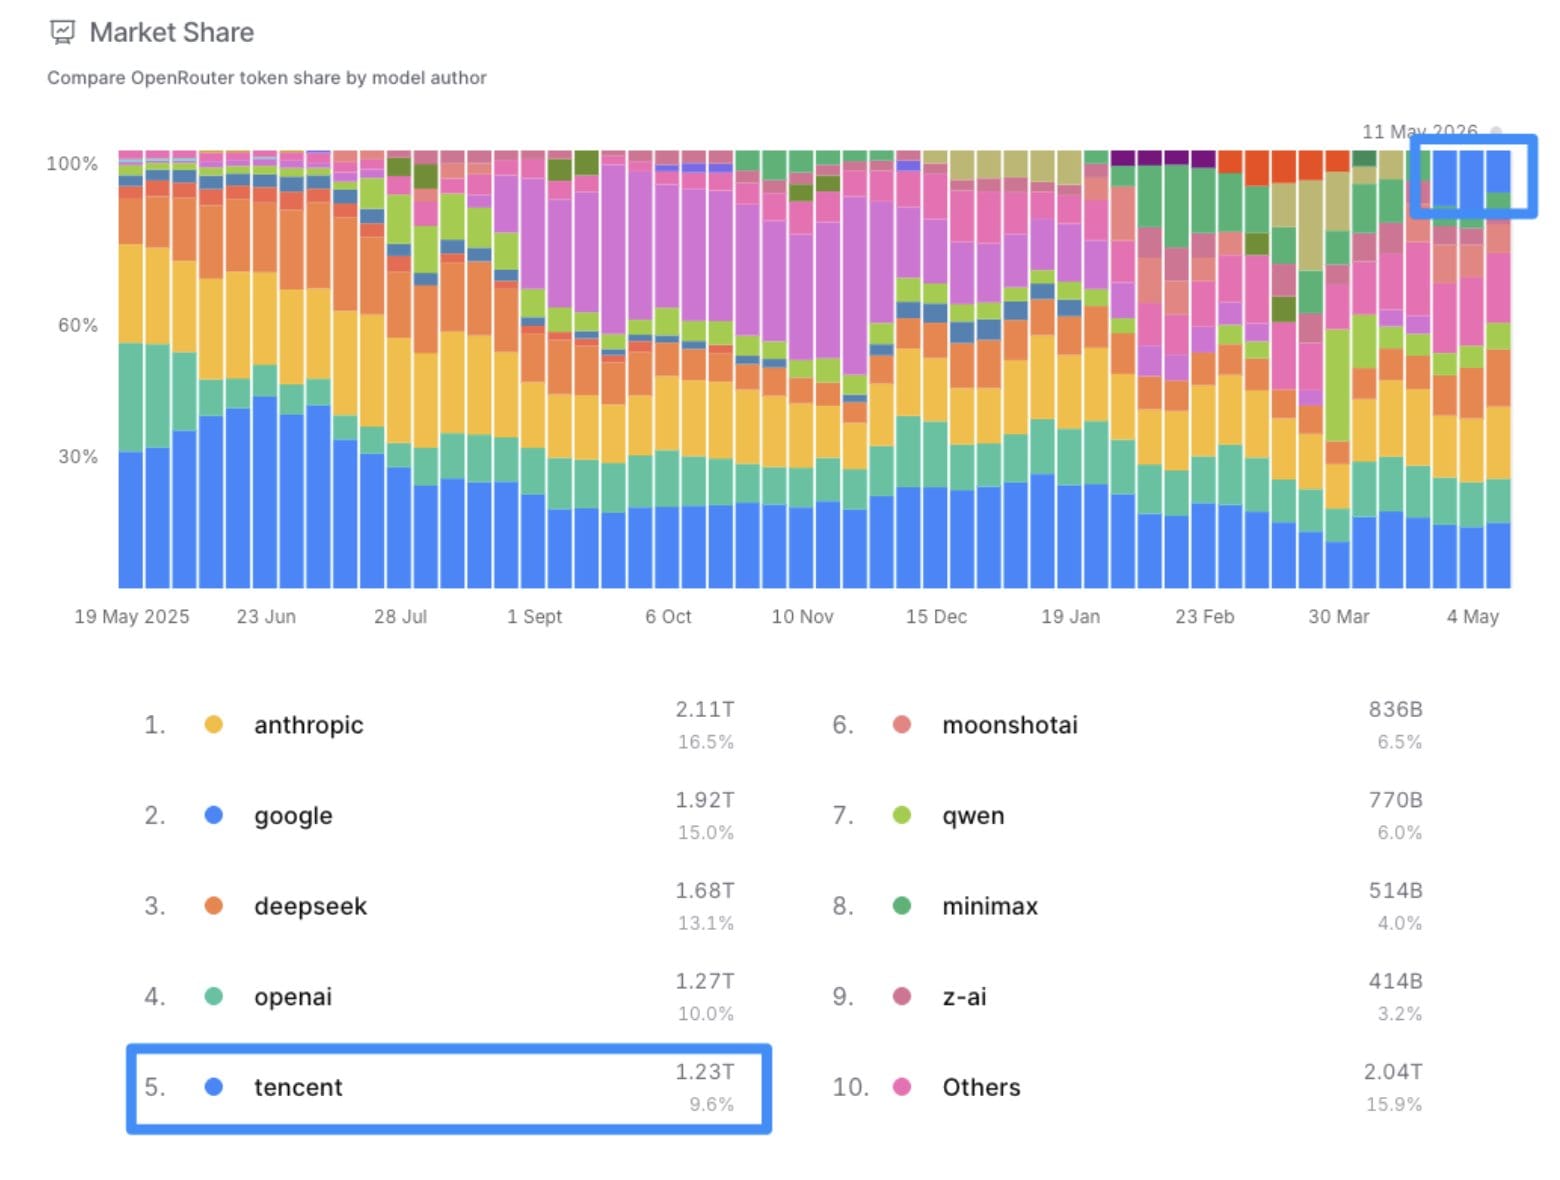
Moreover, this strategic focus on AI is starting to yield tangible results with the introduction of the Hunyuan 3.0 (Hy3) preview. Hunyuan is Tencent's own "Large Language Model" (LLM), built entirely from the ground up by a revamped team of elite AI researchers. Unlike earlier versions, Hy3 has been specifically designed for cost efficiency and practical real-world applicability, with management deliberately shifting the focus away from chasing theoretical public benchmarks and towards superior performance in logical reasoning and coding.
The impact of this is immediately visible: on the OpenRouter platform, the model has climbed to a top position within a short space of time based on token usage, even coming close to established Western models. Within its own ecosystem, the model has now been integrated into 131 internal products, including QQ and Yuanbao, creating a "virtuous feedback loop" in which user data continuously improves the model. In particular, the productivity assistant WorkBuddy has made a flying start with this; this AI agent helps users with daily tasks and is now the most widely used business AI service in China based on daily active users.
Prosus ended the trading week on Euronext Amsterdam at a price of EUR 39.10 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Sofina shareholders' meeting
At Sofina's (Brussels: SOF) annual shareholders' meeting, CEO Harold Boël painted a picture of a holding company that, after a difficult period from 2022 to 2024, has returned to calmer waters. "In a sense, 2025 was once again a normal year", said Boël, referring to the fact that investments and divestments in the preceding years were 40 to 60 percent below the historical average. Last year, the group was once again able to seize a normal number of opportunities and wind down some positions.
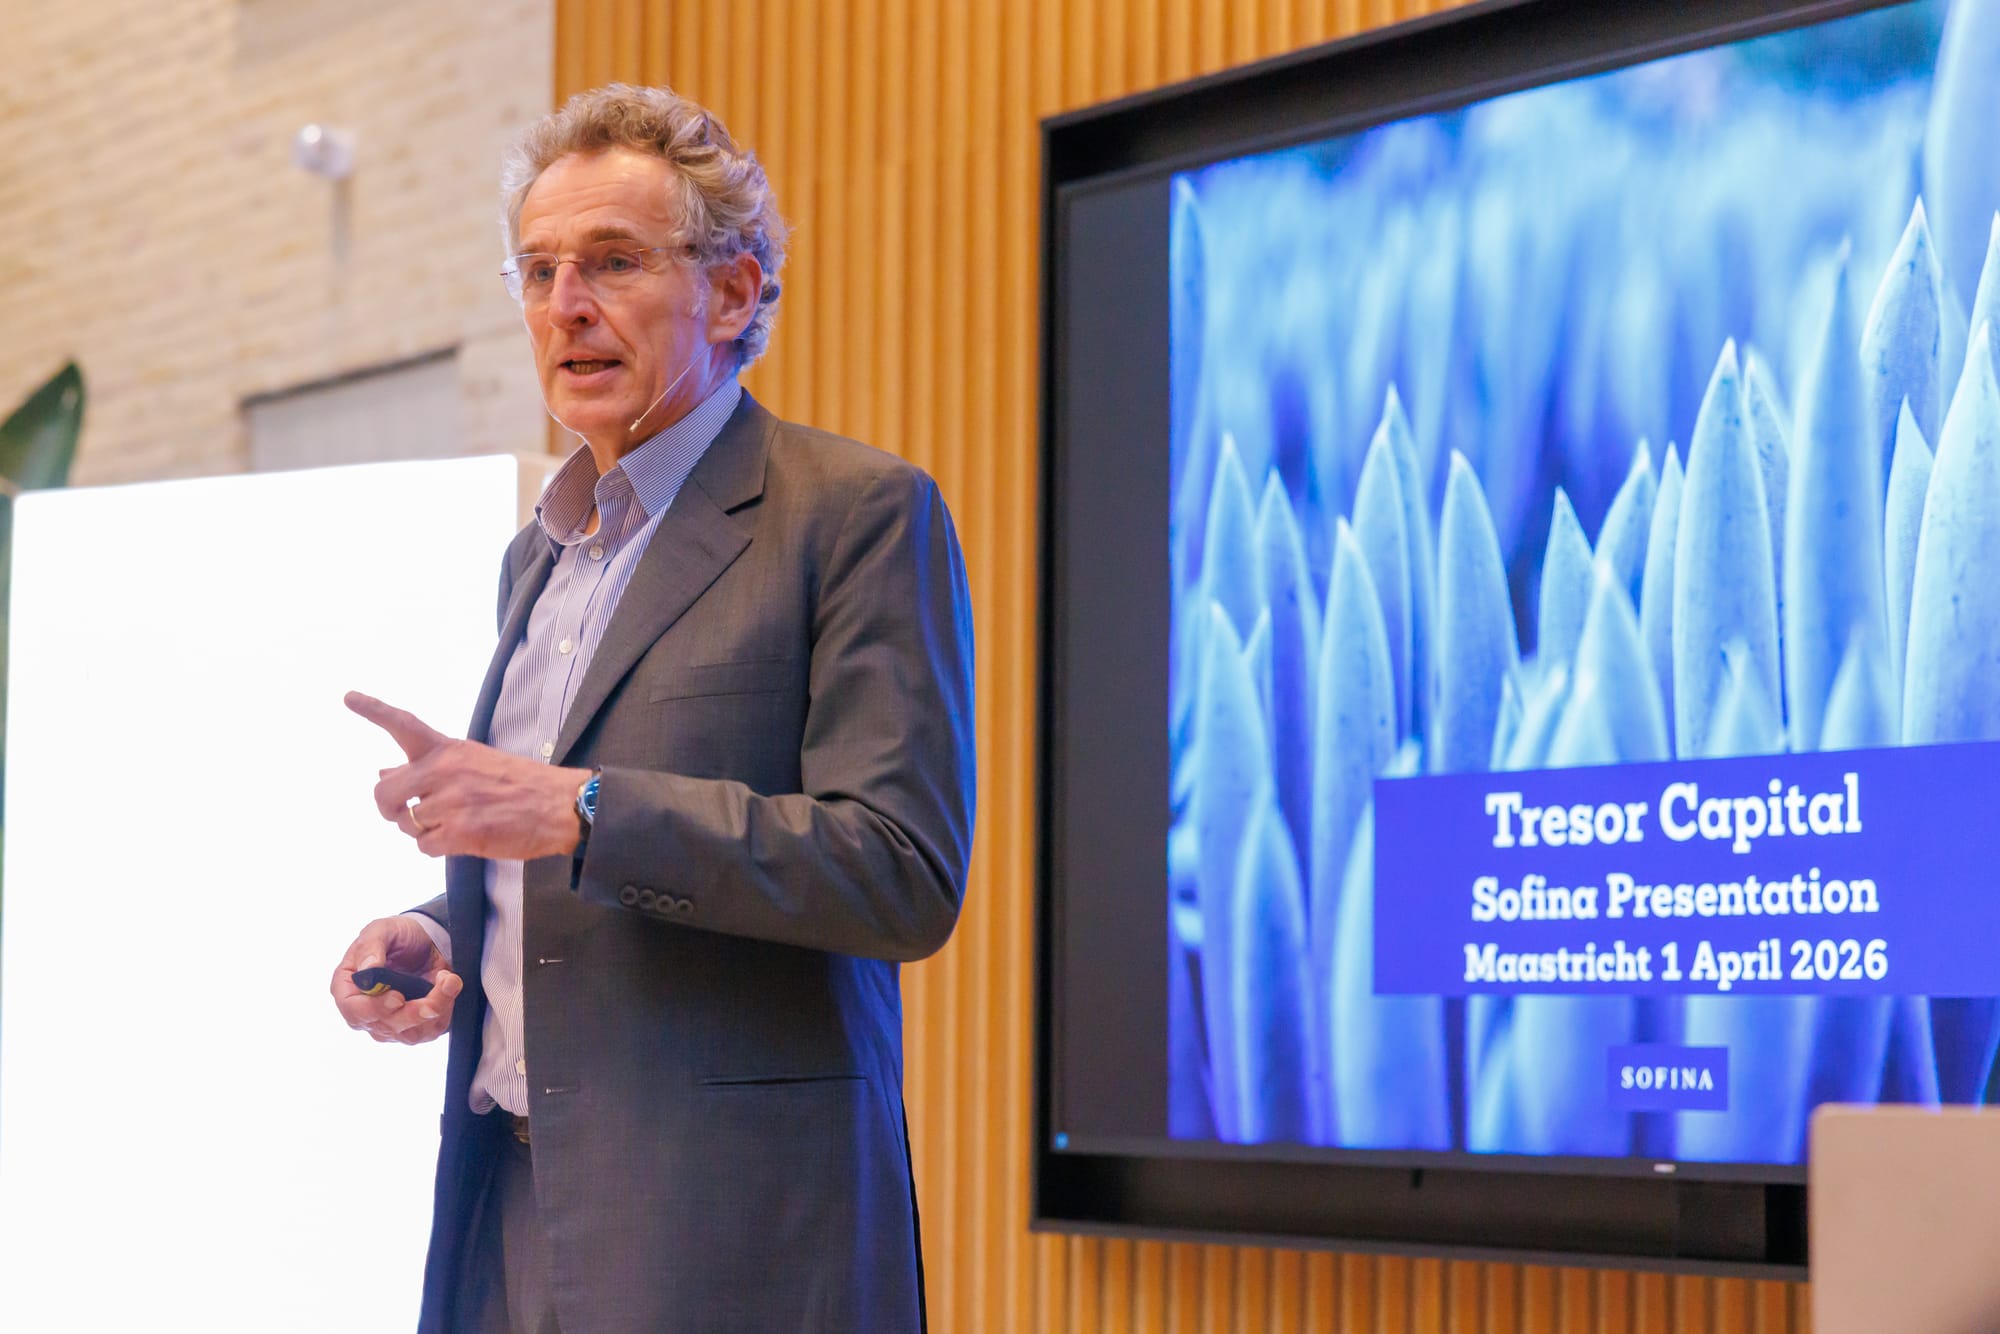
Equity per share was estimated at EUR 304.86 on 31 March 2026, virtually stable compared with the end of December 2025 (-0.30%). That stability is not surprising, given that the NAV calculation currently only takes into account exchange rate effects and movements in listed positions, not revaluations of the private portfolio. The figures therefore still reflect the old valuations from Sofina's private funds. Meanwhile, the share trades at a discount of more than 30 percent to intrinsic value, partly due to the weak dollar, which lost around 12 percent against the euro in 2025.
 Michael Gielkens
At the shareholders' meeting, the question was raised of what the venture capital market looks like outside AI. Boël was clear on this point. A very large share of current VC investments is directed at AI or AI-related themes. It is the most transformative technology the sector has seen in a long time and calls for enormous capital flows. Outside AI, life sciences and, to a lesser extent, consumer sectors remain relevant. But what stands out is the renewed interest in energy-related themes. The AI revolution is sharply driving up energy consumption and computing capacity, which is once again making energy a strategic investment theme. Sofina is playing into AI through an investment in Xbow, a cybersecurity company that deploys AI agents as ethical hackers, and through exposure to major companies such as OpenAI, Anthropic and SpaceX via its fund portfolio.
Finally, after six years, chair Dominique Lancksweert handed over the chairmanship to Sweden's Charlotte Strömberg. Lancksweert, who has reached the statutory maximum age, has been a director of the holding company since 1997.
Sofina ended the trading week on the Brussels stock exchange at a price of EUR 217.60 per share.
Receive weekly insights in your inbox
Exclusive analyses and updates on family holding companies and global market developments.
Would you like more information about our services?
Get in touch
Disclaimer:
No rights can be derived from this publication. This is a publication of Tresor Capital. Reproduction of this document, or parts of it, by third parties is only permitted after written consent and with reference to the source, Tresor Capital.
This publication has been compiled by Tresor Capital with the greatest possible care. The information is intended in a general sense and is not tailored to your individual situation. The information should therefore explicitly not be regarded as advice, an offer or a proposal to purchase or trade investment products and/or to take up investment services, nor as investment advice. The authors, Tresor Capital and/or its employees may hold positions in the securities discussed, for their own account or for their clients.
You should carefully consider the risks before you start investing. The value of your investments can fluctuate. Past performance offers no guarantee for the future. You may lose (part of) your investment. Tresor Capital disclaims any form of liability for any inaccuracies or errors. This information is purely indicative and subject to change.
Read the full disclaimer at tresorcapitalnieuws.nl/disclaimer .
This article was translated automatically from Dutch using AI. In case of any difference, the Dutch original prevails. Read the original in Dutch.



